TL;DR
BI migration for financial services should run in phased waves with a parallel run, and only small single-tool estates should go big-bang. Regional banks on Microsoft 365 with Crystal or SSRS should move to Power BI in waves by report family. Insurers heavy on Tableau should rebuild priority reports on one governed semantic model rather than copy every workbook. Asset managers running investor reports on Excel and email should start with one fund-reporting pilot. Cut unused reports first, then prove every regulated number across two month-end closes before any user switches. Retire the old tool only after finance, risk and compliance sign off, and keep its archive for audit.
Key Takeaways
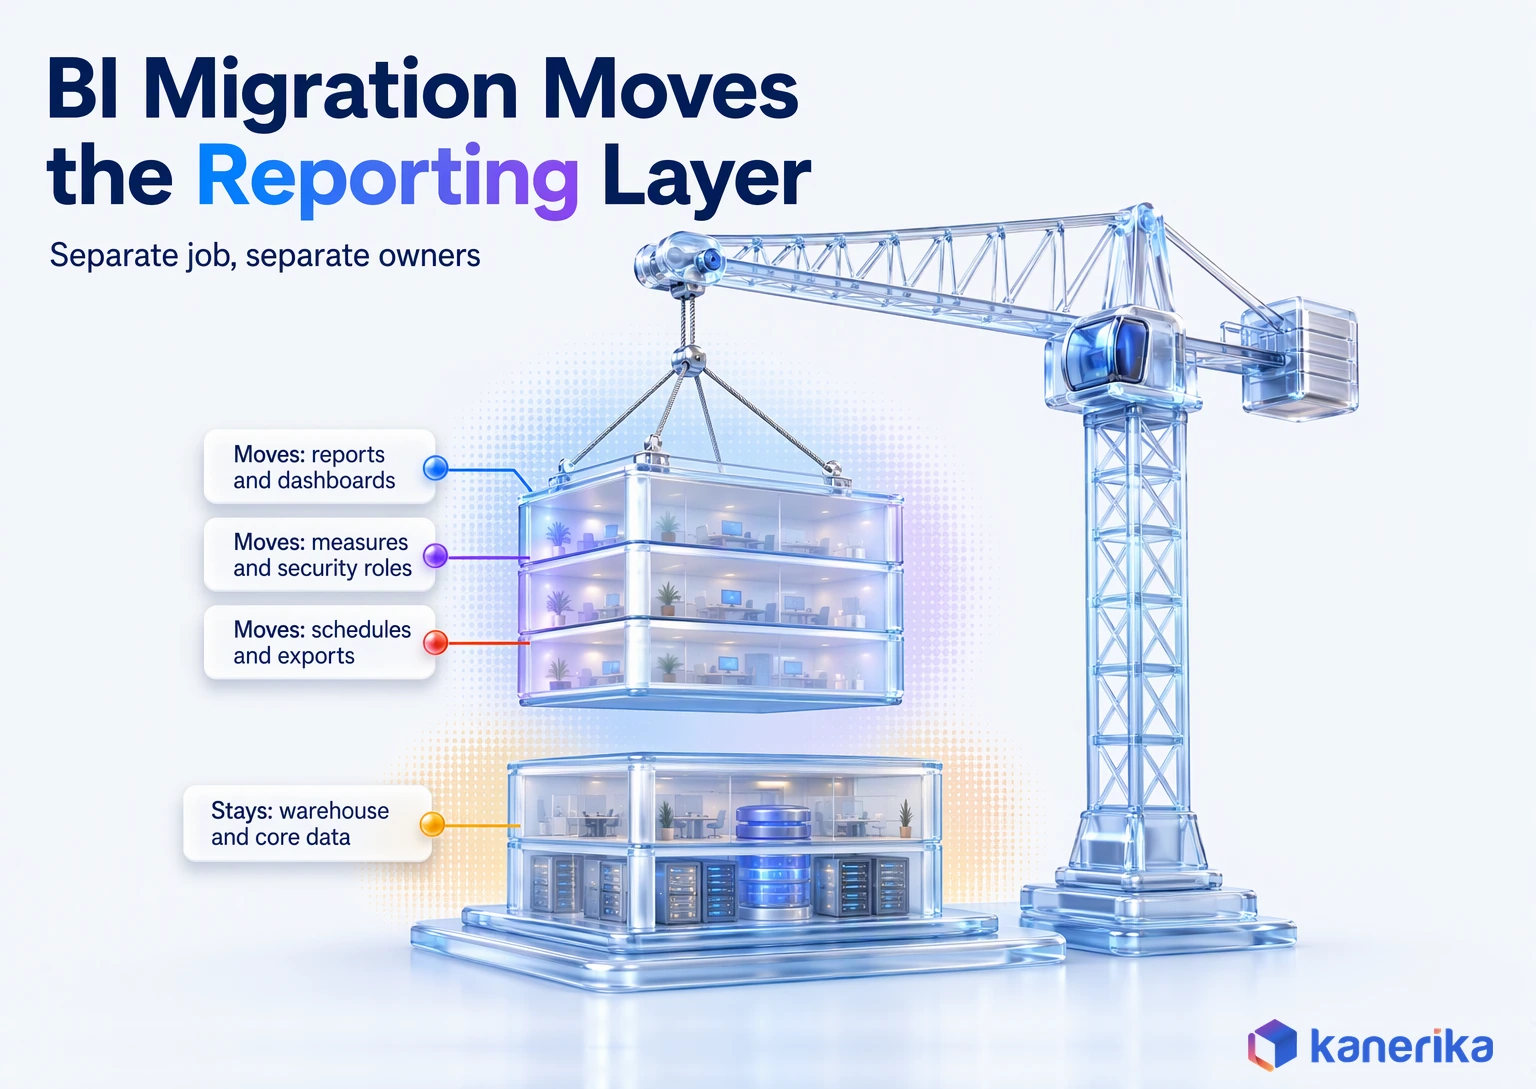
- BI migration for financial services moves the reporting layer, so reports, measures, security roles, schedules and exports all need a plan.
- Usage data decides scope, but reports that feed a regulator stay in scope however rarely they are opened.
- BCBS 239, SOX 404, DORA and SR 26-2 each turn into evidence you keep during the move.
- Phased waves with a parallel run suit most banks, insurers and asset managers better than a single cutover.
- Reconcile control totals and core measures across two month-end closes before any business user switches.
- Decommission the legacy tool last, once sign-off is done, and keep a read-only archive for auditors.
Two Capital Numbers on the Same Morning
It is the second business day after quarter-end at a mid-sized bank. The chief risk officer opens a Tableau dashboard, and it shows one figure for risk-weighted assets. Ten minutes later, the finance director forwards a Cognos report with a different one.
Both numbers come from the same general ledger. Yet one tool applies an exposure filter that the other dropped three years ago, and nobody remembers why. So the team spends the morning tracing logic instead of preparing the board pack.
A scene like this one is the strongest case for a BI migration at a bank, insurer or asset manager. The goal is one governed version of each number, so that the same question always gets the same answer. This guide sets out the plan step by step, from scoping and regulation to reconciliation, cutover and retirement of the old tool.
What BI Migration for Financial Services Covers
BI migration for financial services moves your reporting layer from one business intelligence tool to another. That layer sits on top of your data platform. It holds the reports, the calculations behind them, the security rules and the schedules that push numbers to people.
The distinction matters because many programs blur it. Moving a data warehouse or core banking data is a separate job, which our guide to data migration in fintech covers. A BI move can also run on top of an unchanged warehouse, while still carrying its own risks and owners.
In financial services those risks are sharper than elsewhere. A retail chain can live with a sales chart that looks slightly different after the move. A bank cannot, because the same number may appear in a capital report, a board pack and a regulatory return.
What Must Survive the Move
So the useful definition is practical. Every asset that carries meaning in the old tool must arrive intact, and you must also be able to prove that it did. The table below lists those assets and the proof each one needs.
| Asset | What must survive the move | How you prove it |
|---|---|---|
| Reports and dashboards | Layout, filters, drill paths and totals | Side-by-side screenshots, then control totals |
| Semantic models and measures | Every business rule, such as exposure filters or loss ratios | Measure-level comparison within an agreed tolerance |
| Security roles | Who sees which entity, desk, region or client | Positive and negative access tests per role |
| Schedules and subscriptions | Refresh times, recipients and distribution lists | Delivery log kept until one full close cycle ends |
| Exports and extracts | Files that feed regulators, auditors or other systems | File-level diff against the legacy output |
| Usage and audit history | Who viewed or changed what, and when | Archived logs and a retention owner |
Report Families Banks and Insurers Migrate
Most financial estates group naturally into report families. Planning by family works better than planning by tool, because each family has one business owner who can sign off.
- Regulatory and capital reporting, such as capital ratios, liquidity and large exposures.
- Credit risk, including portfolio quality, provisions and watch lists.
- Asset and liability management and treasury, such as interest rate gaps and funding.
- Fraud and anti-money laundering monitoring, such as alert volumes and case aging.
- Claims and loss ratios for insurers, by line of business and region.
- Fund and investor reporting for asset managers, such as capital accounts and valuations.
- Finance close, from trial balance views through to management accounts.
Why Banks and Insurers Are Migrating BI in 2026
Four triggers push banks and insurers into a BI move, and each one changes the plan. One is about cost, while the other three are about risk, capability and control.
The first is license consolidation. Many firms already pay for Microsoft 365, so Power BI looks like the cheaper home for reporting. Microsoft lists Power BI Pro at $14.00 per user per month, paid yearly, as of November 14, 2026. Paying for a second or third BI tool on top of that is hard to defend when budgets tighten.
The second is AI, since Copilot in Power BI needs paid capacity. Microsoft states that Copilot requires a paid Fabric capacity of F2 or higher, or Power BI Premium P1 or higher. Trial and free SKUs are not supported, so the tool choice now shapes your AI roadmap too.
The third trigger is age. Crystal Reports, Cognos, SAP BusinessObjects and SSRS still run large parts of finance reporting. Over time they collect manual workarounds, such as exports pasted into spreadsheets before a report reaches the board.
The fourth is supervision. Regulators now ask how a number was built, rather than only what it is. That pushes firms toward reporting with clear lineage, owned definitions and controlled change. Notice that only one of these triggers is purely about cost. The others are about control, so a cheap like-for-like copy of the old reports rarely satisfies the people who approved the budget.
Case Study
30% Less Manual Reporting for AMBA Insurance
AMBA, a US insurance association, moved performance reporting onto Power BI and cut manual reporting work by 30%, with more accurate and consistent numbers across its reports.
Read the Case Study →Common BI Migration Paths in Financial Services
Each legacy tool has its own conversion problem, so the path you take depends on where you start. The table maps the usual sources to a target, and it also names the risk that tends to cause rework.
Every row lands in Power BI: interactive reports on Fabric for dashboards, and paginated reports for statements and forms. That target matches the Microsoft 365 estates that many of these firms already run. Looker, or reporting built directly on Databricks or Snowflake, are also common targets when a firm has standardized elsewhere.
| Source tool | Typical FS use | Usual target | Main conversion risk | Kanerika page |
|---|---|---|---|---|
| Tableau | Risk and portfolio dashboards | Power BI on Fabric | Calculated fields and level-of-detail logic, which need DAX rewrites | Tableau to Power BI |
| IBM Cognos | Finance and management reporting | Power BI on Fabric | Framework Manager models and burst schedules | Cognos to Power BI |
| SAP BusinessObjects | Regulatory and operational lists | Power BI on Fabric | Universe joins and contexts, which hide business rules | SAP BusinessObjects migration |
| Crystal Reports | Statements, notices and pixel-perfect forms | Power BI paginated reports | Embedded formulas and subreports | Crystal Reports to Power BI |
| SSRS | Operational and regulatory lists | Power BI paginated reports | Stored procedures and shared data sources | SSRS to Power BI |
| QlikView or Qlik Sense | Sales, branch and claims analysis | Power BI on Fabric | Load scripts and associative logic | Qlik to Power BI migration |
Pixel-Perfect Reports Need a Different Target
Customer statements and regulatory forms built in Crystal or SSRS belong in Power BI paginated reports rather than interactive dashboards. A customer statement, for example, must match the printed form line for line, which a dashboard layout is not built to do. Treating them as dashboards is a common cause of failed sign-off.
Kanerika Service
BI and Reporting Migration Services
Kanerika moves Tableau, Cognos, SAP BusinessObjects, Crystal Reports, SSRS and Qlik estates to Power BI, with inventory, automated conversion, reconciliation and sign-off built into every wave.
Explore Migration ServicesThe deeper detail for each path sits in our dedicated guides. See Tableau to Power BI migration and Cognos to Power BI for dashboard-heavy estates. For list and form reporting, read SSRS to Power BI migration as well as Crystal Reports to Power BI migration.
Regulations That Shape a Financial-Services BI Migration
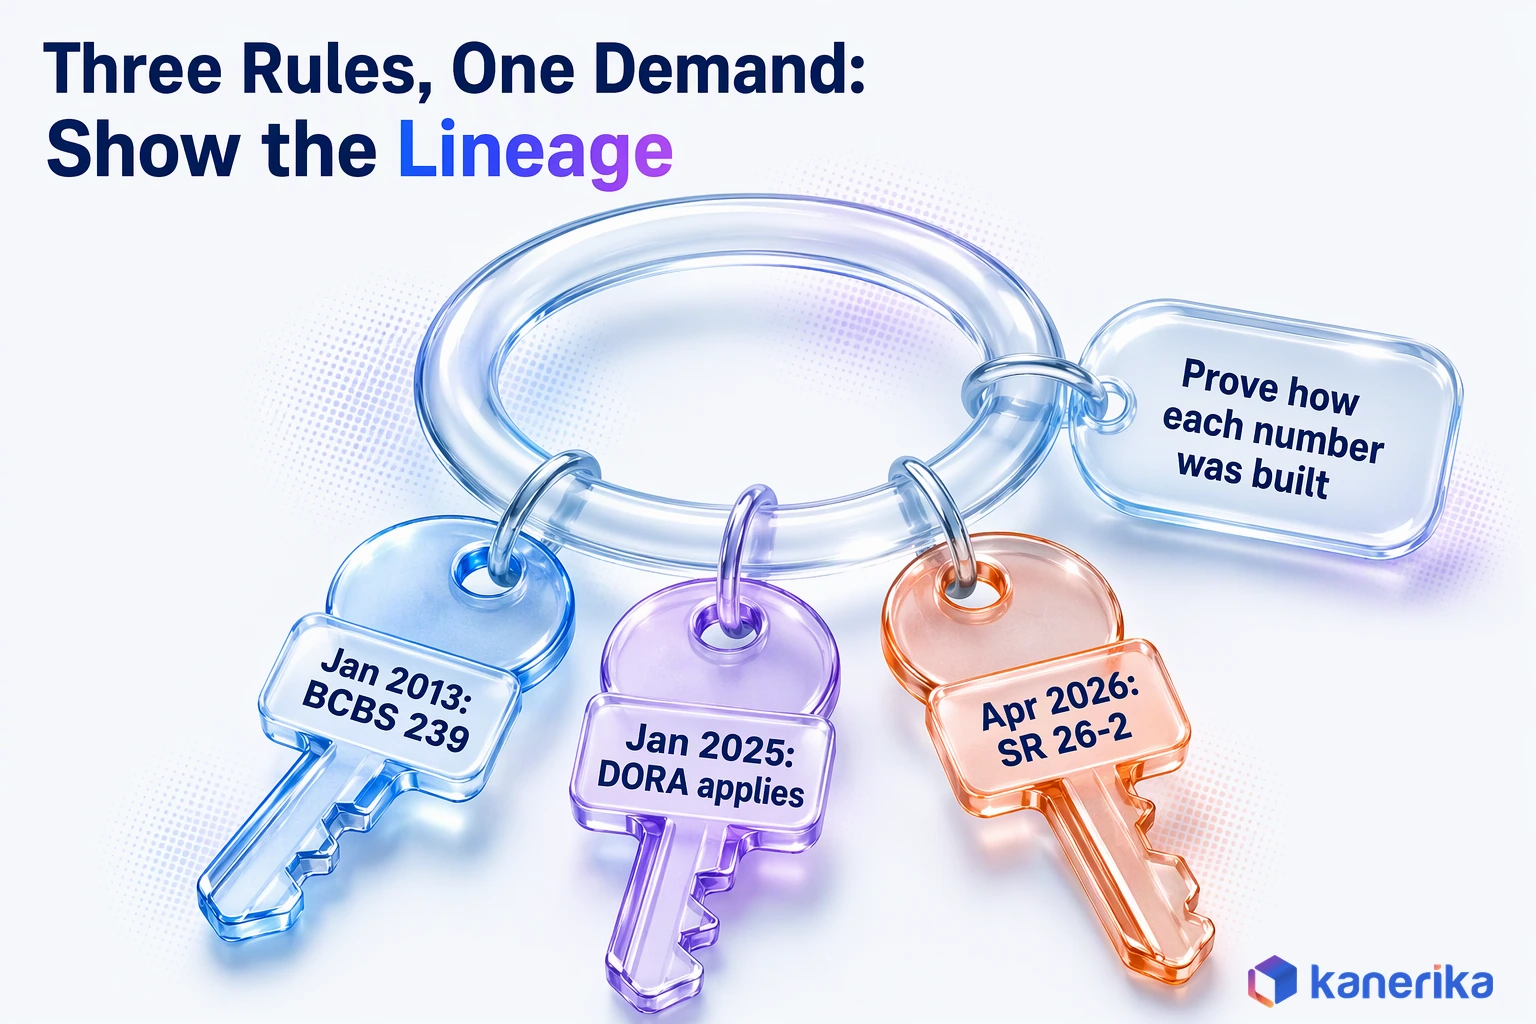
What a regulator cares about after a BI migration is the evidence: lineage, reconciliation, change control and retained records. So the practical step in a financial-services BI migration is to turn each obligation into evidence that the team creates and keeps.
BCBS 239 is the clearest example for banks. The Basel Committee published its principles for effective risk data aggregation and risk reporting on January 9, 2013, and they still apply. They expect accurate, complete and timely risk reports with traceable data, which is exactly what a careless migration can break.
For EU entities, the Digital Operational Resilience Act also adds an ICT angle. EIOPA notes that DORA entered into application on January 17, 2025 and covers banks, insurers and investment firms. As a result, a new BI platform and its vendor fall inside that ICT risk framework.
In the US, model risk guidance matters only when a report embeds a calculation that the firm treats as a model. The Federal Reserve, OCC and FDIC issued SR 26-2 on April 17, 2026, which supersedes SR 11-7 and SR 21-8. If a dashboard computes expected loss, for example, that logic needs the same validation evidence after the move.
Turning Each Rule Into Evidence
| Obligation | What it expects | Migration evidence to keep |
|---|---|---|
| BCBS 239 | Accurate, complete, timely risk reporting with traceable data | Lineage from source to report, reconciliation results and data owner sign-off |
| SOX 404 | Effective internal control over financial reporting | Change tickets, access reviews and approvals for every in-scope report |
| SR 26-2 | Sound model risk management when a calculation is used as a model | Model inventory entry, validation results and change approval |
| DORA (EU entities) | ICT risk management and third-party oversight | Vendor risk assessment, resilience tests, incident procedures |
| SEC record-keeping | Retained, retrievable records for fund and broker reporting | Archive of legacy outputs, retention schedule and a retrieval test |
The evidence list then becomes part of the plan, with an owner and a deadline for each item. Pair it with your lineage tooling, since data lineage is the thread that ties most of these obligations together.
Treat this section as planning guidance rather than legal advice. Your compliance and legal teams decide which rules apply to each entity.
Rationalize the Report Estate Before You Convert
Rationalization means deciding which reports deserve to move before anyone converts a single one. It is the cheapest phase: every retired report is one you never build, test or sign off. Take the example in Kanerika’s State of Enterprise Data Platform Migrations 2026 report: 500 Informatica mappings, 200 Crystal Reports and an SSIS layer. The report puts its manual migration at $3M to $8M over 12 to 18 months.
Start with usage logs from the legacy tool. Most tools record views, refreshes and subscriptions, so you can see which reports nobody has opened in months. Then group near-duplicates, such as ten branch versions of one profitability report that differ only by a filter.
One rule overrides the usage data. A report that feeds a regulator, an auditor or a statutory filing stays in scope, even if it runs once a year. Quarter-end and year-end reports often look unused in a 90-day log, so check the calendar before you retire them.
| Disposition | Rule of thumb | Example |
|---|---|---|
| Retire | No views in 90 days and no regulatory or audit use | A one-off campaign dashboard from an old product launch |
| Migrate as-is | Stable logic, steady use, simple layout | A daily branch cash position list |
| Rebuild on the semantic model | Duplicated logic, or several versions of one metric | Ten regional loan book reports merged into one, then secured with row-level security |
| Retain temporarily | Needed for audit or a filing until the target is proven | A year-end regulatory return kept until two closes reconcile |
The output is a scoped inventory with a disposition, an owner and a wave for every report. That list drives effort, cost and timeline far more than the choice of target tool.
Checklist
Power BI Checklist
A practical checklist for planning, building and governing Power BI, useful when you turn a scoped report inventory into a target design and wave plan.
Get the Checklist →Choose the Approach: Conversion Method and Cutover Pattern
Two separate choices hide inside the question of how to migrate. One is how you convert each report, while the other is how users switch from the old tool to the new one.
Conversion method is about effort per report, whereas cutover pattern is about risk to the business. Mixing them up leads to plans that say “big bang” when they mean “automated”, or the reverse.
| Conversion method | Best for | Watch out for |
|---|---|---|
| Lift and shift | Simple lists and stable reports | It copies old duplication into the new tool |
| Rebuild on a semantic model | Core metrics used across many reports | Definitions must be agreed before build starts |
| Automated conversion with review | Large estates with repeating patterns | Converted logic still needs human validation |
Automation helps most when reports repeat the same patterns, and rates differ by source tool. On Kanerika delivery data, FLIP automated 80% of Crystal Reports to Power BI work, 75% for SSRS and 70% for Cognos. Kanerika’s State of Enterprise Data Platform Migrations 2026 report lists these Kanerika-reported rates by path. Our article on the role of automation in migration explains what tools can convert and where people still have to step in.
Target Architecture: One Governed Semantic Layer
The target that pays back is a shared semantic model, rather than a pile of converted reports. Each core measure, such as exposure, provision or loss ratio, is defined once and then reused by every report. So when a definition changes, it changes everywhere at the same time.
That model sits on a governed data layer, often a warehouse or lakehouse on Fabric, Databricks or Snowflake. Our guide to the lakehouse for financial services covers that storage side in detail.
Some regulated firms still need reports to stay on premises, especially when data residency or network rules apply. In those cases Power BI Report Server is worth testing early, and our guide to Power BI Report Server explains its limits.
Cutover Patterns: Big Bang, Phased Waves, Parallel Run
The cutover pattern decides how much risk users carry on the day they switch. Pick it per report family rather than once for the whole program, because a fraud dashboard and a capital return carry very different stakes.
| Pattern | How it works | Pick it when | Risk level |
|---|---|---|---|
| Big bang | All users switch on one date | The estate is small, uses one tool and has no regulatory reports | High |
| Phased waves | Report families move one wave at a time | Several families have different owners | Medium |
| Parallel run | Old and new run side by side until numbers match | A report feeds a regulator or the board | Low, but costly |
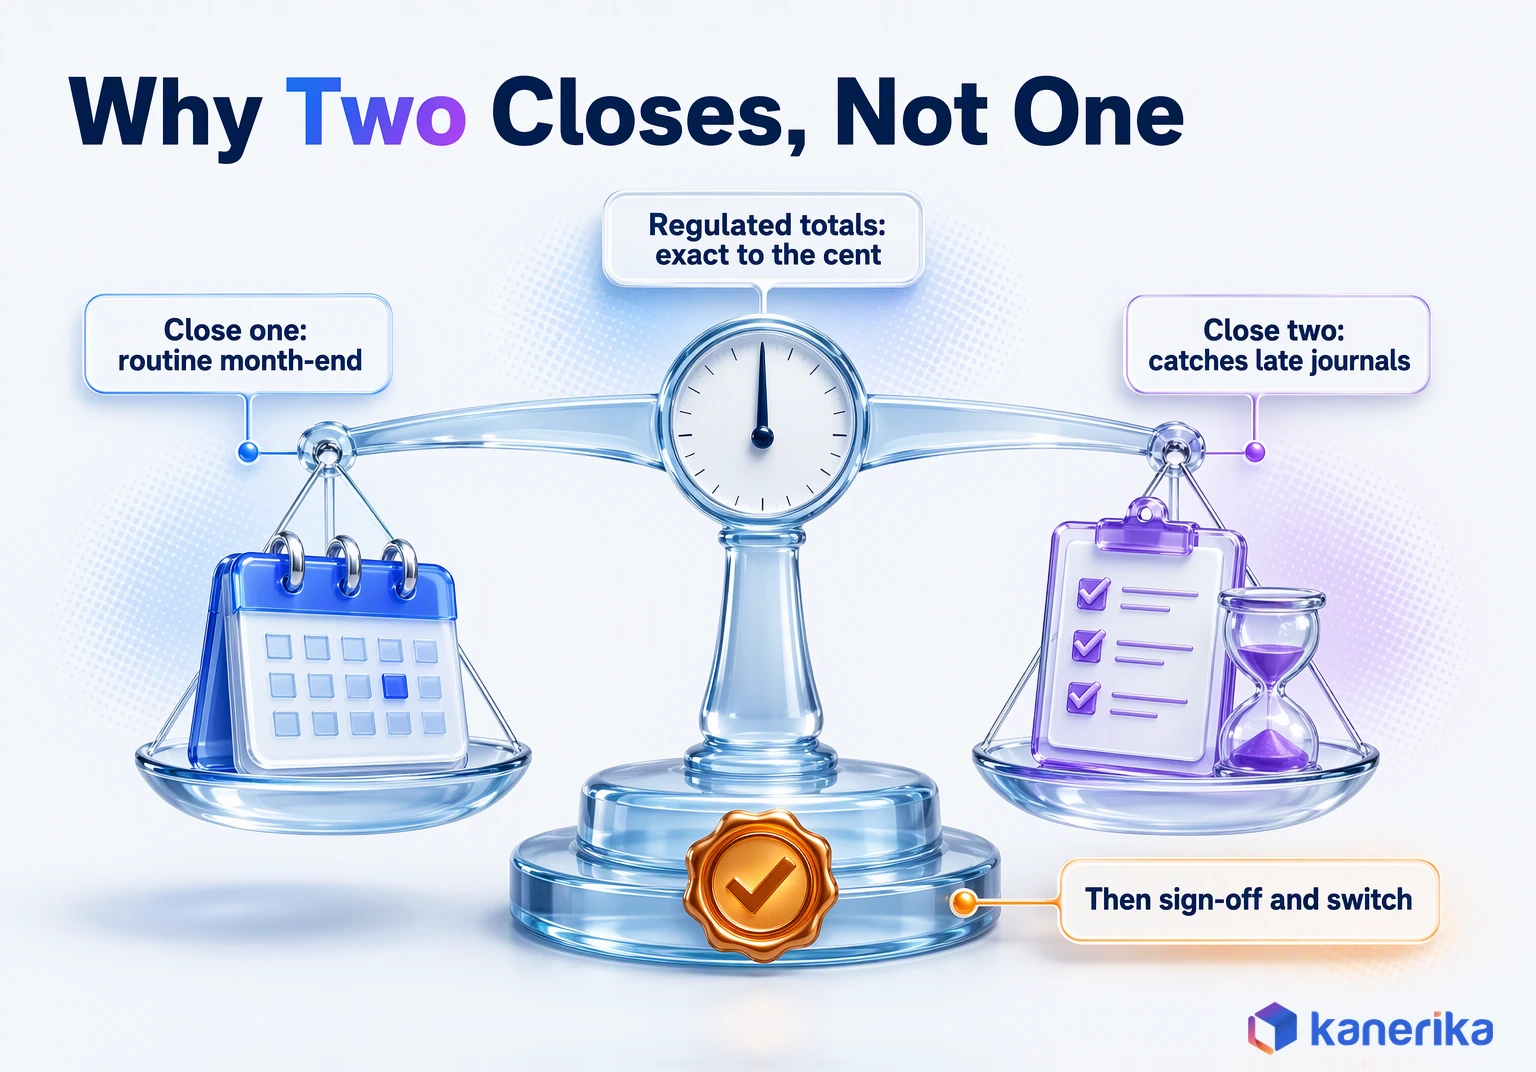
For regulated reporting, combine the last two. Move in waves, and run every wave that touches regulated numbers runs in parallel for at least two month-end closes before users switch.
Decision Framework: Which Approach Fits Your Institution
For a financial institution, the right plan depends on who you are and what you run today. The four scenarios below cover most banks, insurers and asset managers, and each one comes with a clear pick.
| Scenario | Pick | Why | Evidence needed |
|---|---|---|---|
| Regional bank on Microsoft 365, running Crystal and SSRS | Phased waves to Power BI, with paginated reports for statements | Licenses already overlap, and report logic is mostly SQL | Control totals per report and SOX change tickets |
| Insurer with a large Tableau estate | Rebuild priority reports on one semantic model, then convert the rest in waves | Loss ratio and reserve logic repeats across workbooks | Measure comparison per line of business and access tests |
| Asset manager or fund administrator on Excel and email | Pilot one fund-reporting family, then expand fund by fund | The risk sits in manual steps rather than in a legacy tool | Investor report reconciliation and an audit trail |
| Global bank with several BI tools after a merger | Rationalize first, then phased waves with parallel runs | Reports overlap, so definitions conflict | BCBS 239 lineage and sign-off per legal entity |
None of these picks is big bang. A single cutover only makes sense for a small, single-tool estate with no regulated reports, so test your estate against that profile before you choose it.
Worked Example: Credit Risk and Finance Close Reporting
The numbers below are illustrative rather than from a client, but they show how the plan narrows scope. Imagine a bank moving credit risk and finance close reporting from Cognos to Power BI.
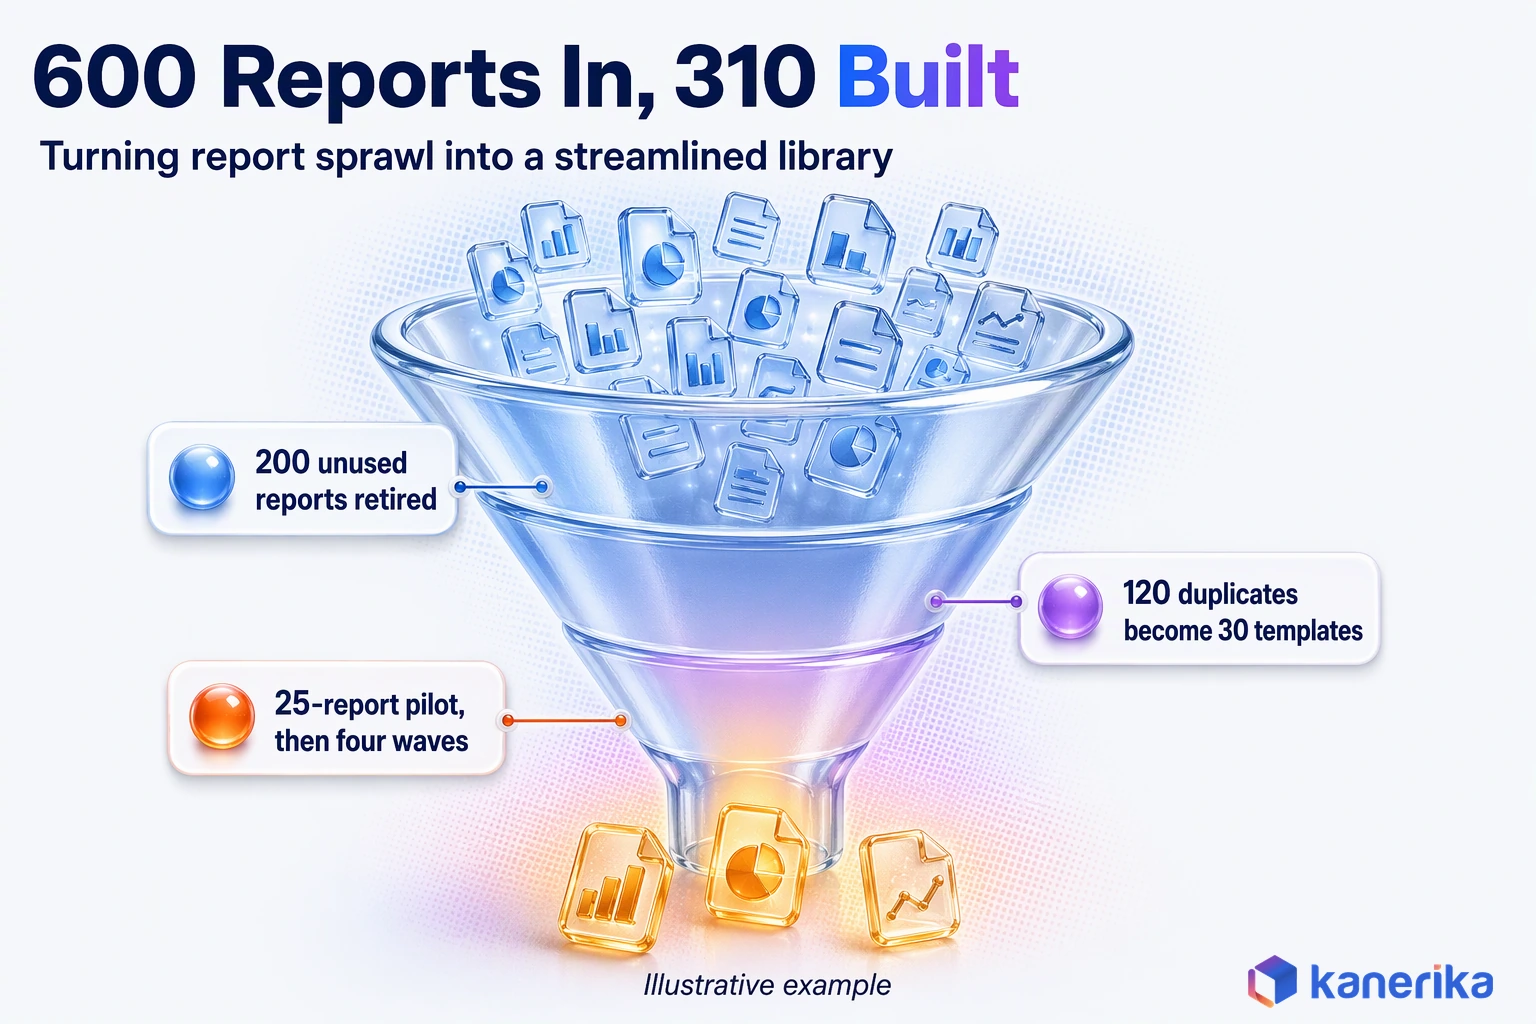
- Inventory finds 600 reports across both families.
- Usage logs show 220 with no views in 90 days. Twenty of those are quarterly or annual regulatory reports, so 200 are retired.
- Of the remaining 400, 120 are near-duplicates that collapse into 30 templates with row-level security. The build list then falls to 310 reports.
- A pilot moves 25 credit risk reports first, so the semantic model and the reconciliation method get tested early.
- The other 285 then move in four waves of roughly 70 reports each.
- Every wave runs in parallel across two month-end closes before users switch.
- Cognos is retired only after the last wave signs off and its outputs are archived.
Cutting 600 reports to 310 removes almost half the build and test work before conversion even starts. That saving usually matters more than any tool choice.
Step-by-Step BI Migration Plan
A runbook turns the migration strategy into gates that someone owns. Each step below has an owner and an exit gate, so the program cannot move on until the gate is met.
The gates also depend on each other. The pilot gate proves the reconciliation method that every later wave reuses, so a weak pilot slows every wave after it. Validate cannot pass without the two-close parallel run, and cut over waits on validate.
Decommission comes last for a reason, since the archive is what auditors will ask for once the old tool is gone.
| Step | Owner | Exit gate |
|---|---|---|
| 1. Inventory | BI lead | A complete list of reports, models, roles, schedules and exports |
| 2. Rationalize | Business owner of each report family | A disposition and wave for every report |
| 3. Target design | Data architect | An approved semantic model, workspace layout and security design |
| 4. Pilot | Migration lead | One report family reconciled and signed off |
| 5. Convert in waves | Delivery team | Each wave built, peer reviewed and deployed to test |
| 6. Validate | Finance or risk, per family | Reconciliation within tolerance across two closes |
| 7. Cut over | Program sponsor | A signed go decision and a tested rollback |
| 8. Decommission | IT operations | An archived legacy estate, then canceled licenses |
Promote changes through Power BI deployment pipelines rather than editing in production. That gives you the change trail SOX auditors expect, and it also keeps test and live content apart.
Reconciliation and Parallel Run for Regulated Numbers
Reconciliation is how you prove that the new report says what the old one said. For regulated numbers it is the gate that matters most, so design it before the first report is converted.
Run old and new side by side for two month-end closes, because one close can hide a problem. Some breaks only appear with a quarter-end adjustment or a late journal. Two closes, by contrast, give finance and risk enough evidence to sign off with confidence.
| Check | What you compare | Tolerance | Sign-off owner |
|---|---|---|---|
| Control totals | Total exposure, balances or premiums per entity | Exact to the cent for regulated figures | Finance controller |
| Row counts | Accounts, policies or positions per report | Exact, since a missing row is a missing customer | Data owner |
| Measure-level checks | Ratios, averages and derived metrics | Agreed rounding tolerance per measure | Risk or actuarial lead |
| Spot checks | Ten to twenty sampled records, traced end to end | No unexplained difference | Internal audit observer |
A simple query catches most breaks early. The example below compares month-end totals per legal entity from the legacy extract and the new model export. It then returns only the rows that differ.
-- Compare month-end totals per legal entity, legacy vs migrated
WITH legacy AS (
  SELECT legal_entity, SUM(exposure_amount) AS total
  FROM legacy_report_extract
  WHERE close_date = DATE '2026-10-31'
  GROUP BY legal_entity
),
migrated AS (
  SELECT legal_entity, SUM(exposure_amount) AS total
  FROM new_model_export
  WHERE close_date = DATE '2026-10-31'
  GROUP BY legal_entity
)
SELECT
  COALESCE(l.legal_entity, m.legal_entity) AS legal_entity,
  l.total AS legacy_total,
  m.total AS migrated_total,
  COALESCE(m.total, 0) - COALESCE(l.total, 0) AS difference
FROM legacy AS l
FULL OUTER JOIN migrated AS m
  ON m.legal_entity = l.legal_entity
WHERE ABS(COALESCE(m.total, 0) - COALESCE(l.total, 0)) > 0.005
   OR l.legal_entity IS NULL
   OR m.legal_entity IS NULL;
Log every difference with a cause and an owner, even when it turns out to be a legacy bug. Those logs then become audit evidence. For deeper validation methods, see our guides to data reconciliation and how to ensure data quality during data migration.
Security, Entitlements and PII
Security is a common place for a financial BI migration to slip, because legacy tools enforce access in ways that do not copy across. A Cognos or BusinessObjects role rarely maps one to one onto a Power BI role, so it has to be rebuilt and tested.
Build row-level security into the semantic model early, rather than in the last wave. Our guide to Power BI row-level security covers the patterns. Then test it from both sides, since proving that the right people see data is only half the job.
- Rebuild row-level security by legal entity, desk, region or client book.
- Run negative tests, such as a branch manager who must not see another branch’s customers.
- Control exports and subscriptions, because a scheduled email can leak data that a role hides.
- Apply sensitivity labels to reports that hold customer PII, for example with Microsoft Purview Information Protection.
- Review workspace access and service accounts before go-live.
Cutover, Rollback and Decommission Gates
Cutover is a decision rather than a date on a plan. So each gate below needs a named person who can say yes or no.
- Reconciliation is within tolerance for two closes, and the data owner has signed.
- Access tests pass, including negative tests, and the security owner has signed.
- Subscriptions and exports are re-pointed, then the first deliveries are checked.
- A rollback trigger is agreed, with the person who can call it and a deadline.
- Users are trained, and the support desk has a runbook for the first close.
- The legacy tool moves to read-only, then into an archive with a retention owner.
- Licenses are canceled only after the archive passes a retrieval test.
Cost, Effort and Timeline Drivers
The cost of a financial-services BI migration is set mostly by the shape of your estate rather than by the target tool. So a bottom-up estimate starts from the scoped inventory and adds effort for each driver below.
Migration ROI Calculator
Estimate Your BI Migration ROI
Use Kanerika’s migration ROI calculator to compare effort, cost and timeline for an automated BI migration against a manual rebuild of every report.
Calculate Migration ROI →| Driver | Raises effort when | Lowers effort when |
|---|---|---|
| Report count after rationalization | Every legacy report moves | Unused and duplicate reports are cut first |
| Logic complexity | Business rules live inside report formulas | Rules move into a shared semantic model |
| Pixel-perfect output | Statements and forms must match exactly | Dashboards can be redesigned instead |
| Security model | Access differs by entity, desk and client | Roles are simple and well documented |
| Regulated reports | Many reports need two-close parallel runs | Regulated scope is small and well defined |
| Automation | Every report is rebuilt by hand | Tooling converts repeating patterns, then people review them |
Power BI License Prices
Licenses are the easier part to size. The prices below are Microsoft’s published US list prices, checked November 14, 2026, although your agreement may differ.
| Power BI license | List price | Typical user |
|---|---|---|
| Power BI Pro | $14.00 per user per month, paid yearly | Report authors and viewers in Pro workspaces |
| Premium Per User | $24.00 per user per month, paid yearly | Analysts who need larger models and more frequent refreshes than Pro allows |
| PPU add-on for Pro, Microsoft 365 E5 or Office 365 E5 users | $14.00 per user per month, paid yearly | Users who already hold Pro through E5 |
As a simple illustration, 1,000 Pro users at $14.00 cost $14,000 a month, or $168,000 a year, before any capacity. Firms that want Copilot also need F2 or higher Fabric capacity, or Premium P1 or higher, so price that separately. Then compare it against your current BI tool’s own quote.
Our breakdowns of Power BI Premium vs Pro and Microsoft Fabric capacity cover the details.
Timelines follow the same drivers as cost. A single-family pilot moves much faster than a multi-tool estate after a merger, yet neither escapes the close cycle. The worked example above is a pilot plus four waves, and each wave runs in parallel across two month-end closes before users switch. That is why a regulated estate is measured in quarters rather than weeks. The two-close parallel run alone sets a floor of roughly two months for any regulated wave.
Talk to Kanerika
Planning a BI Migration at a Bank or Insurer?
Kanerika helps finance, risk and IT teams scope the report estate, map regulatory evidence and design the reconciliation before the first wave. A short working session turns the plan into dates and owners.
Schedule a Demo →Risks, Governance and Common Mistakes
The mistakes that sink financial-services BI migrations are ordinary ones, and each has a simple fix if it is planned early. Kanerika’s State of Enterprise Data Platform Migrations 2026 report puts Kanerika-reported post-go-live remediation at 10% of FLIP projects, against a 65% industry average. The table below pairs each mistake with what happens and how to prevent it.
| Mistake | What happens | Fix |
|---|---|---|
| Converting unused reports | Effort and testing balloon | Rationalize with usage logs before conversion |
| Rebuilding row-level security late | Data exposure, or a delayed go-live | Design security during the pilot |
| Skipping the close-cycle parallel run | Breaks surface in a regulatory return | Run two closes side by side |
| Measure drift between reports | Two versions of one number again | Define measures once in the semantic model |
| No data owner sign-off | Nobody owns a disputed number | Name an owner per report family |
| Shutting the legacy tool before archiving | Auditors cannot retrieve old outputs | Archive, then test retrieval first |
| Ignoring subscriptions and exports | Downstream teams and regulators miss files | Inventory and re-point every delivery |
| Migrating spreadsheet workarounds silently | Manual risk moves to the new platform | Log end-user tools, then replace them deliberately |
Governance holds these fixes together. A small steering group with finance, risk, compliance and IT should own the evidence list, the wave plan and the go decisions. When that group meets every two weeks, problems surface while they are still cheap.
How Kanerika Runs BI Migration for Financial Services
Kanerika’s approach follows the same gates described above, while tooling shortens the slow parts. The work moves in five stages.
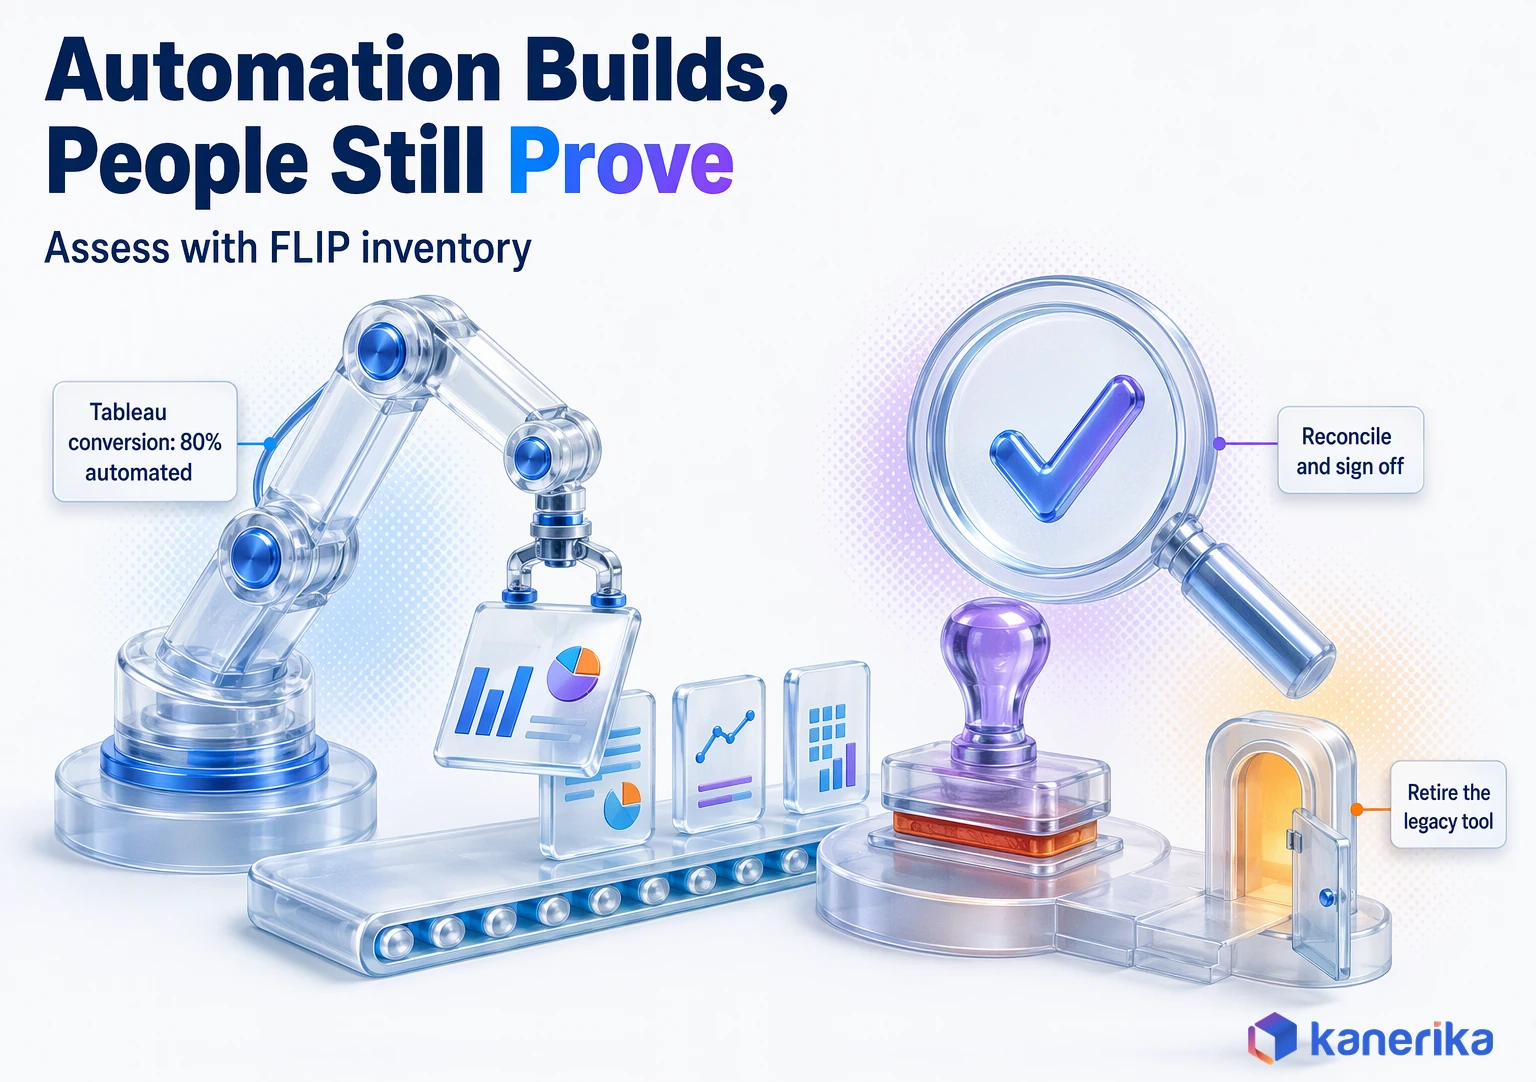
- Assess the estate with an automated inventory from FLIP, Kanerika’s migration accelerator.
- Pilot one report family, so the semantic model and the reconciliation method are proven first.
- Convert the remaining families in waves, especially where patterns repeat and automation helps.
- Reconcile and collect sign-off from finance, risk and compliance for each wave.
- Retire the legacy tool once its outputs are archived.
On Tableau estates, Kanerika states on its Tableau to Power BI service page that FLIP automates 80% of the conversion work. The switch still happens only after reports pass validation and sign-off, so automation shortens the build without skipping the proof.
Some work stays manual by design. Business owners still agree measure definitions, review security roles and sign each reconciliation, because that accountability cannot sit with a tool. The team plans those reviews into every wave, so they never become a queue at the end of the program.
Results From Kanerika Engagements
A private equity fund administrator, unnamed on the case study page, shows what this looks like in practice. The firm moved quarterly investor reporting off Excel and email and onto Power BI. As a result, it reported a 70% reduction in manual reporting hours per quarter. It also kept 100% report and data integrity across funds, with data trails on demand for SEC review.
Insurance follows a similar pattern, with AMBA cutting manual reporting by 30% as noted earlier. Outside financial services, a Cognos to Power BI move for a global retail enterprise saw a 65% increase in operational performance. BI-related costs also fell by 27%, and the case is a useful reference because the worked example above is a Cognos move too.
Financial institutions planning this work can find the wider offer on Kanerika’s banking and financial services page. Teams weighing a broader platform decision can also start with our data platform migration decision framework.
Bottom Line: A Controlled BI Migration Plan for 2026
A good BI migration plan in financial services is controlled rather than fast. Banks, insurers and asset managers should cut the report estate first, then rebuild core numbers on one governed semantic model and move in phased waves. Every regulated number also runs in parallel across two closes before anyone switches.
Before you approve the program, check that the plan covers each point below.
- A scoped inventory with a disposition and owner for every report.
- An evidence list mapped to BCBS 239, SOX 404, DORA and SR 26-2 where they apply.
- One semantic model design, so that each measure is defined once.
- A pilot report family with a named business owner.
- A reconciliation method with tolerances and two-close parallel runs.
- Row-level security designed during the pilot, with negative tests.
- A rollback trigger, plus a legacy archive that passes a retrieval test.
For a 2026 BI migration plan at a bank, insurer or asset manager, start with the inventory and one pilot family. The rest of the plan follows from what that pilot proves.
Frequently Asked Questions
What is BI migration?
BI migration is the move of a reporting layer from one business intelligence tool to another. It covers reports, dashboards, semantic models, calculations, security roles, schedules and exports. In financial services the move also needs proof that every number survived intact, so reconciliation and sign-off are part of the job, not an optional extra at the end.
Why is BI migration important for financial services companies?
Banks, insurers and asset managers depend on reports that reach boards, auditors and regulators. Legacy BI tools often carry duplicated logic and manual workarounds, so the same figure can differ between reports. A planned migration gives one governed version of each number, clearer lineage for supervisors and a single license estate that is easier to control.
How long does a BI migration take in financial services?
Duration depends on report count after rationalization, logic complexity, security design and how many regulated reports need parallel runs. A single report family pilot moves far faster than a multi-tool estate after a merger. Any wave that touches regulated numbers needs at least two month-end closes in parallel, which sets a floor of about two months.
How much does a BI migration cost for a bank?
Cost is driven by the scoped report count, logic complexity, pixel-perfect output, security rules, regulated parallel runs and how much conversion is automated. Licenses are easier to size. Microsoft lists Power BI Pro at $14.00 and Premium Per User at $24.00 per user per month, paid yearly, with Fabric capacity priced separately.
Should banks use a phased or big-bang BI migration?
Most banks should use phased waves with a parallel run for regulated reports. Big bang suits only a small, single-tool estate with no regulatory output, because one bad number on cutover day can reach a board pack or a return. Waves let each report family prove its numbers and sign off before users switch.
How do you validate financial reports after a BI migration?
Compare old and new outputs across two month-end closes. Check control totals per entity to the cent, row counts per report, ratios and derived measures within an agreed rounding tolerance, and a sample of records traced end to end. Log every difference with a cause and an owner, because those logs become audit evidence.
How do you preserve row-level security during a BI migration?
Rebuild it in the semantic model during the pilot, not in the last wave. Map each legacy role to entity, desk, region or client rules, then test both sides, confirming that permitted users see the data and that others cannot. Also review subscriptions and exports, since a scheduled email can expose rows a role hides.
Can BI reports be migrated automatically?
Partly. Automated tools convert repeating report patterns, data connections and much of the calculation logic, which shortens the build for large estates. Converted reports still need human review, reconciliation against the legacy output and sign-off from the business owner. In regulated reporting, automation speeds up the work, but it never replaces the proof.
What BI systems are commonly migrated in financial services?
The usual sources are Tableau, IBM Cognos, SAP BusinessObjects, Crystal Reports, SSRS and QlikView or Qlik Sense. Many firms move them to Power BI on Microsoft Fabric because they already run Microsoft 365. Others standardize on Looker or build reporting on Databricks or Snowflake, depending on where their data platform already sits.
Do banks use Power BI?
Yes. Many banks, insurers and finance teams use Power BI for risk dashboards, finance close views, branch performance and regulatory lists. It fits firms already on Microsoft 365, and paginated reports cover statements and fixed-format forms. Banks still need governed semantic models, row-level security and change control around it to meet audit expectations.
How can financial services companies ensure regulatory compliance during BI migration?
Turn each obligation into evidence the team keeps. BCBS 239 calls for lineage and reconciled risk reports, SOX 404 for change tickets and access reviews, and DORA for vendor and resilience checks in EU entities. Assign an owner to every evidence item, and let compliance and legal confirm which rules apply to each entity.
What are the main challenges in BI migration for financial services?
The hardest parts are hidden business logic, security rules that do not map across tools, and reports that must match to the cent. Subscriptions and exports are easy to miss, and spreadsheet workarounds often move silently. Scoping with usage data, early security design and a two-close parallel run deal with most of these problems.
How can organizations minimize risk and downtime during BI migration?
Move in phased waves by report family and keep the legacy tool running until each wave signs off. Run old and new side by side across two month-end closes for regulated numbers, so close is never disrupted. Agree a rollback trigger, a decision maker and a deadline before go-live, then switch users only after sign-off.
What role does data governance play in BI migration success?
Governance decides who owns each number and how it may change. Without owners, disputed figures stall sign-off and old duplication returns in the new tool. A steering group from finance, risk, compliance and IT should own the evidence list, the wave plan and every go decision, while the semantic model defines each measure once.
How do companies measure success after BI migration?
Useful measures include reconciled reports with no unexplained differences, the share of legacy reports retired, license cost removed and fewer manual reporting hours. Audit outcomes matter too, such as clean change and access evidence. Adoption counts as well, so track active users and confirm that teams have stopped exporting data into private spreadsheets.
Is BI replaced by AI?
No. AI features sit on top of BI rather than replacing it. Copilot in Power BI, for example, needs a paid Fabric capacity of F2 or higher or Premium P1 or higher, and it works best on a clean semantic model. Governed measures and reconciled numbers remain the foundation that any AI answer depends on.