AI Underwriting Intake Agent for Insurance
Submission intake that reads broker emails, ACORD forms, loss runs, and SOVs, then hands underwriters a complete, triaged file.
Broker emails read and structured
Missing information chased for you
Underwriters make every decision
Type II certified delivery
Certified security practices
Technology certifications
Submission intake that reads broker emails, ACORD forms, loss runs, and SOVs, then hands underwriters a complete, triaged file.
Brokers judge carriers on speed to quote, yet underwriters still spend hours re-keying submission data before they can assess a single risk. An AI underwriting intake agent extracts risk data from every submission document, checks appetite and completeness, and routes the file to the right underwriter with the gaps already listed. Kanerika builds and runs this insurance underwriting automation inside your environment, and your underwriters keep every decision.
How Underwriting Process Automation Works in Your Environment
Deployed on Your Stack
Kanerika deploys the agent on your Azure, AWS, GCP, or on-premise infrastructure, connected to the submission inbox and policy systems you already run.
Governed and Secure by Design
Kanerika holds SOC 2 Type II, ISO 27001, and ISO 9001:2015 credentials. The agent inherits your access controls and audit requirements.
Works Where Underwriting Works
Triage summaries, appetite flags, and follow-up drafts arrive in Teams, Slack, or the shared submission inbox your desk already uses.
Data Stays in Your Tenant
Submission documents, extracted fields, and broker correspondence remain in your tenant and are never used to train outside models.
Underwriters Keep the Decision
The agent prepares and prioritizes files. Quoting, declining, and referring stay with your underwriters, with every recommendation open to review.
Source-Traced Extractions
Every extracted field links back to the page and document it came from, so checking a number takes one click, not a document hunt.
Reinventing Insurance Operations With Data and AI
See how Kanerika applies data and AI across insurance operations, the setting where an underwriting intake agent sits.
KlarityIQ Document Intelligence in Action
The document-intelligence agent behind extraction of broker submissions, loss runs and SOVs.
Document Automation for Underwriting on Every Submission
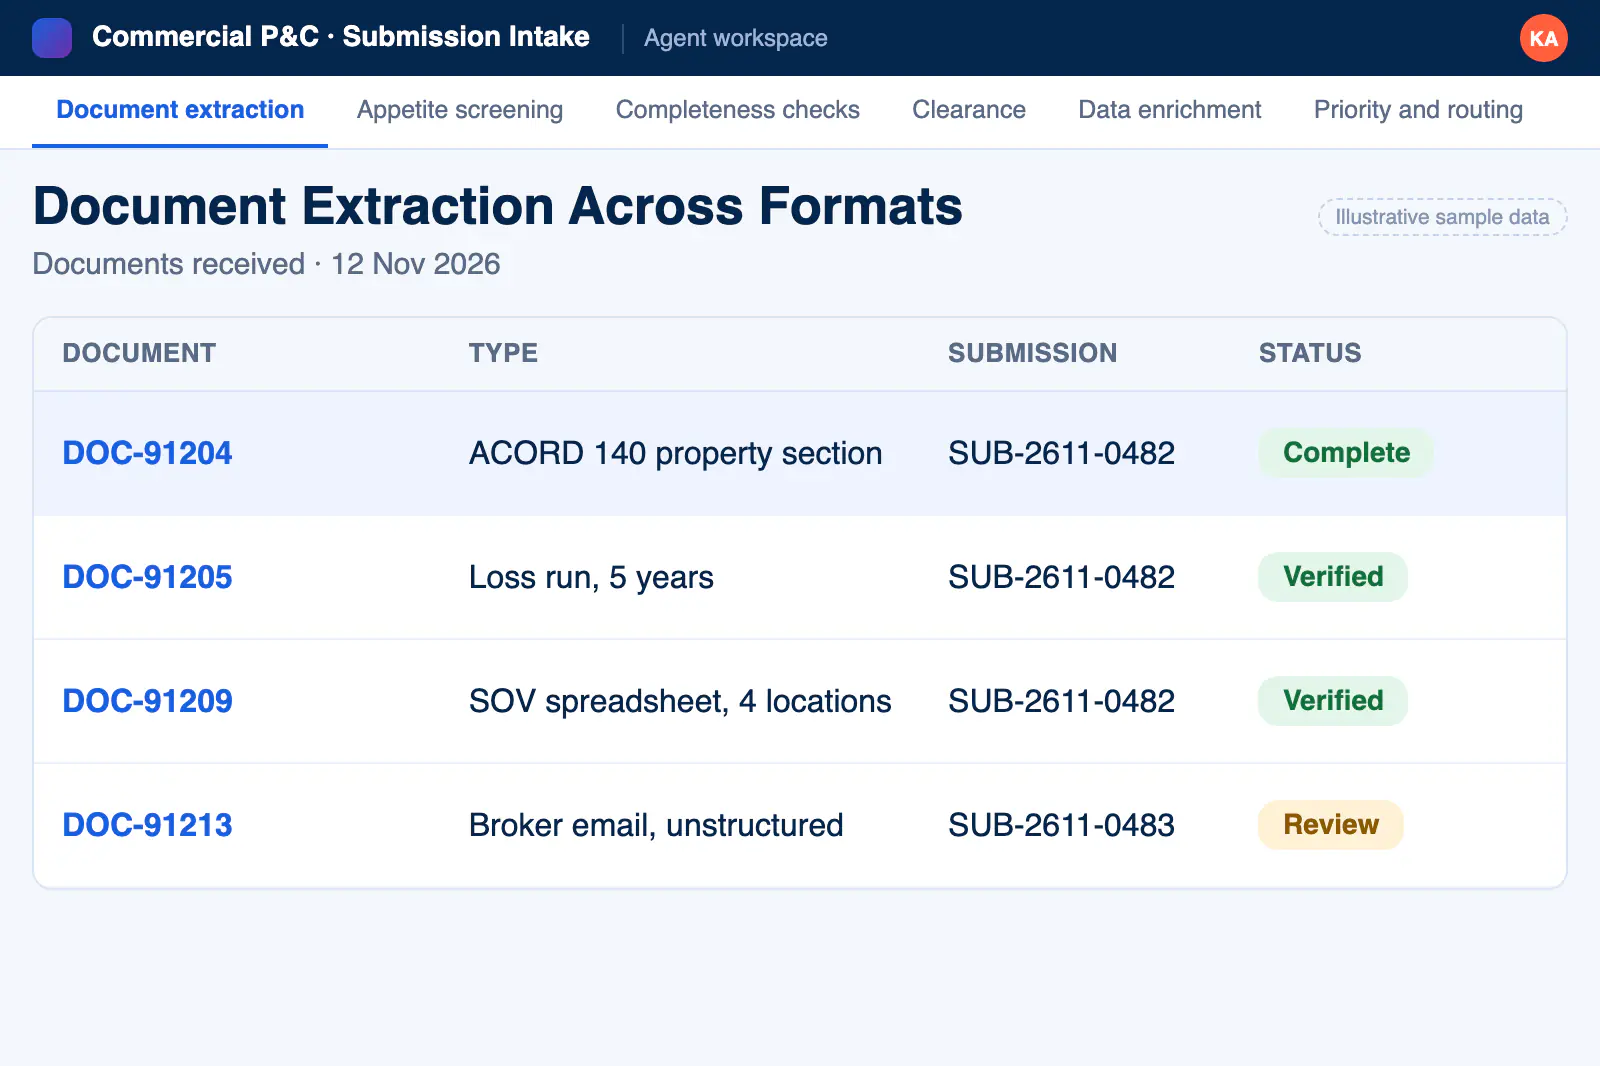
Document Extraction Across Formats
ACORD applications, loss runs, schedules of values, and unstructured broker emails are read and converted into structured risk data.
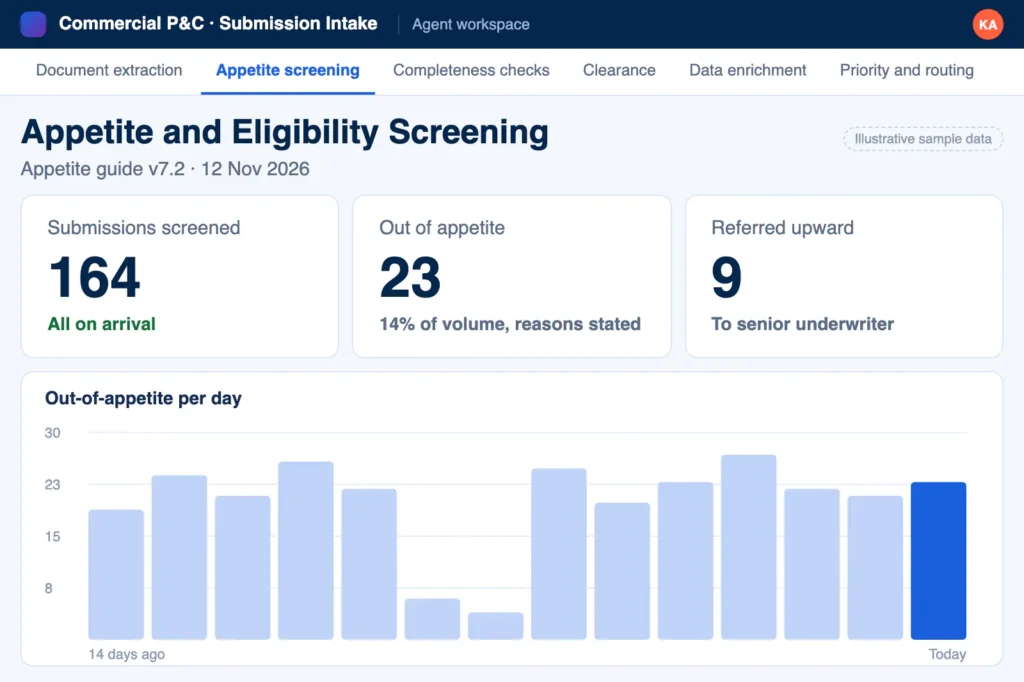
Appetite and Eligibility Screening
Class of business, geography, limits, and exclusions are checked against your appetite rules, with out-of-appetite submissions flagged and the reason stated.
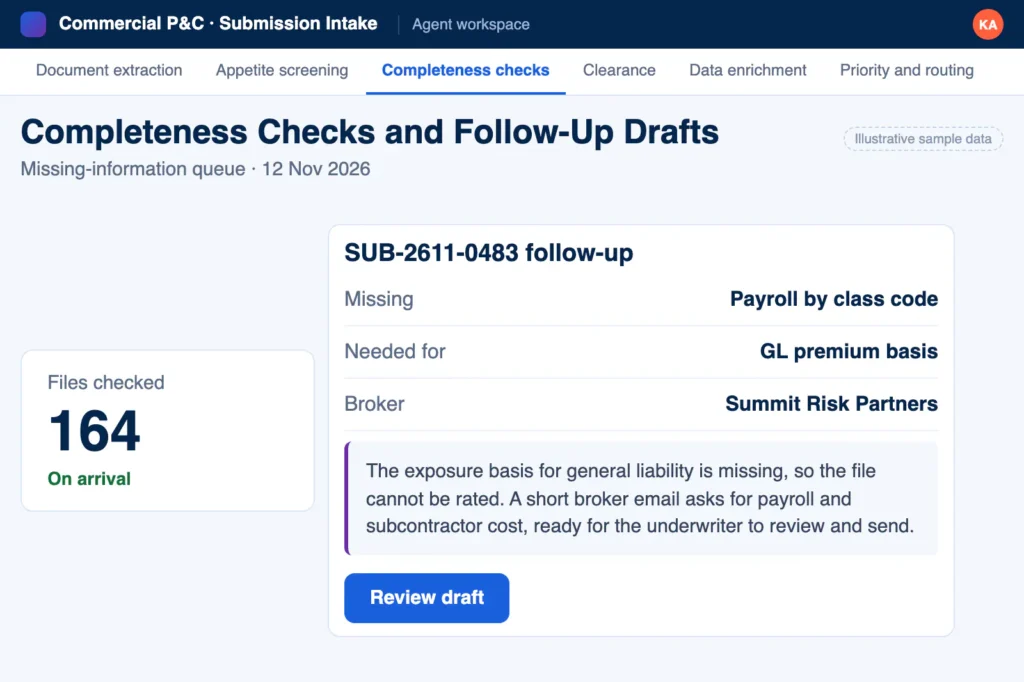
Completeness Checks and Follow-Up Drafts
Missing exposure data is identified on arrival, and a broker follow-up email is drafted for the underwriter to review and send.
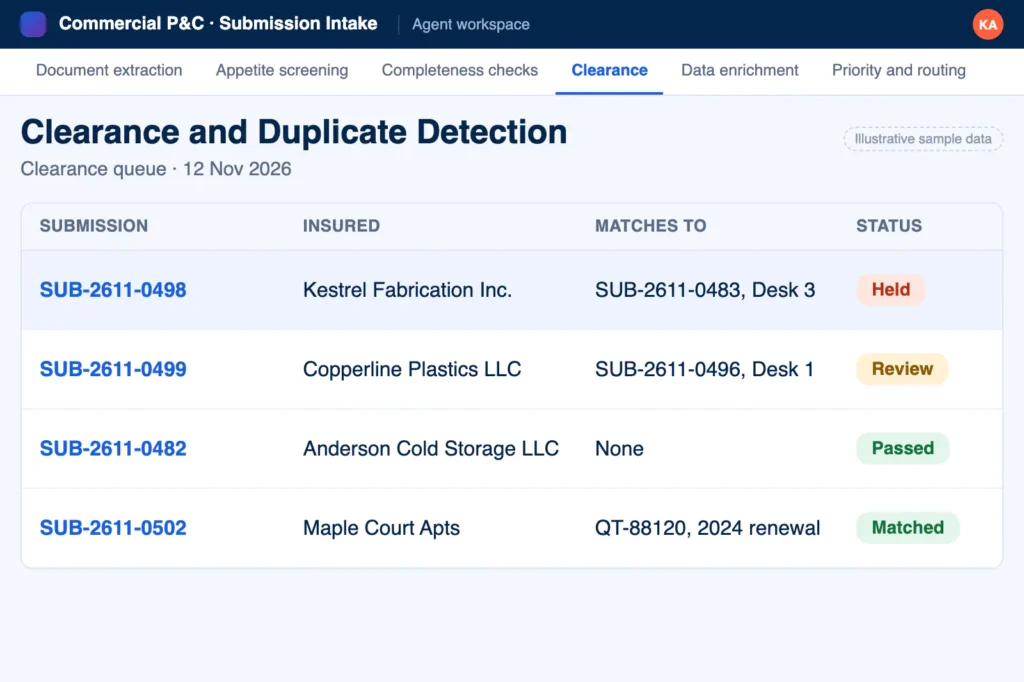
Clearance and Duplicate Detection
New submissions are matched against in-flight and historical records so two desks never work the same risk unknowingly.
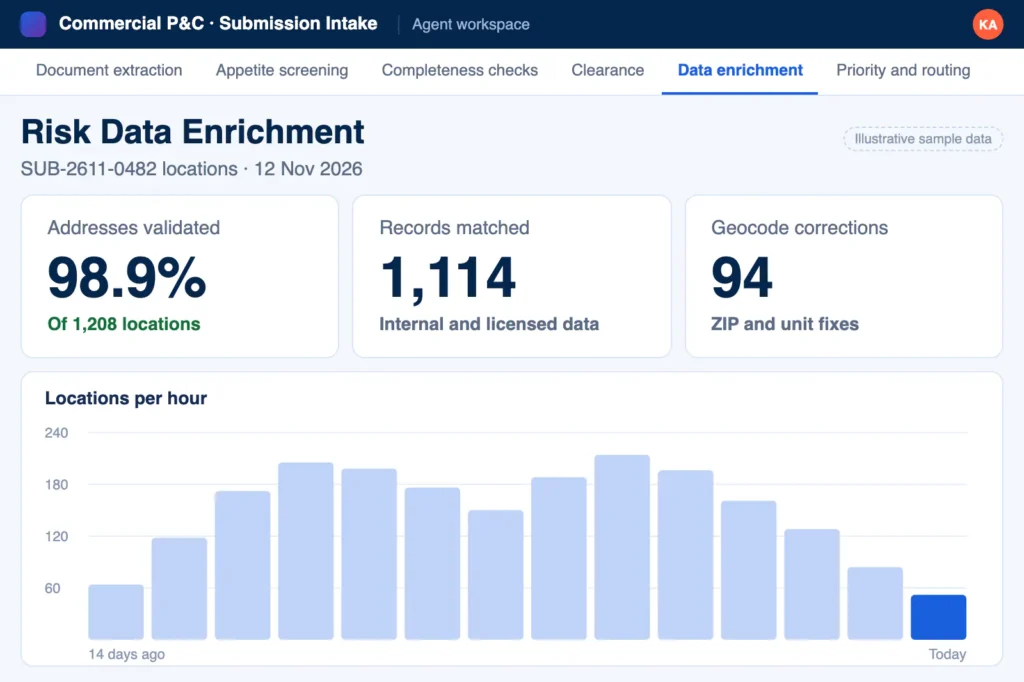
Risk Data Enrichment
Addresses are validated and exposure records are matched against the internal and licensed data sources your team already uses.
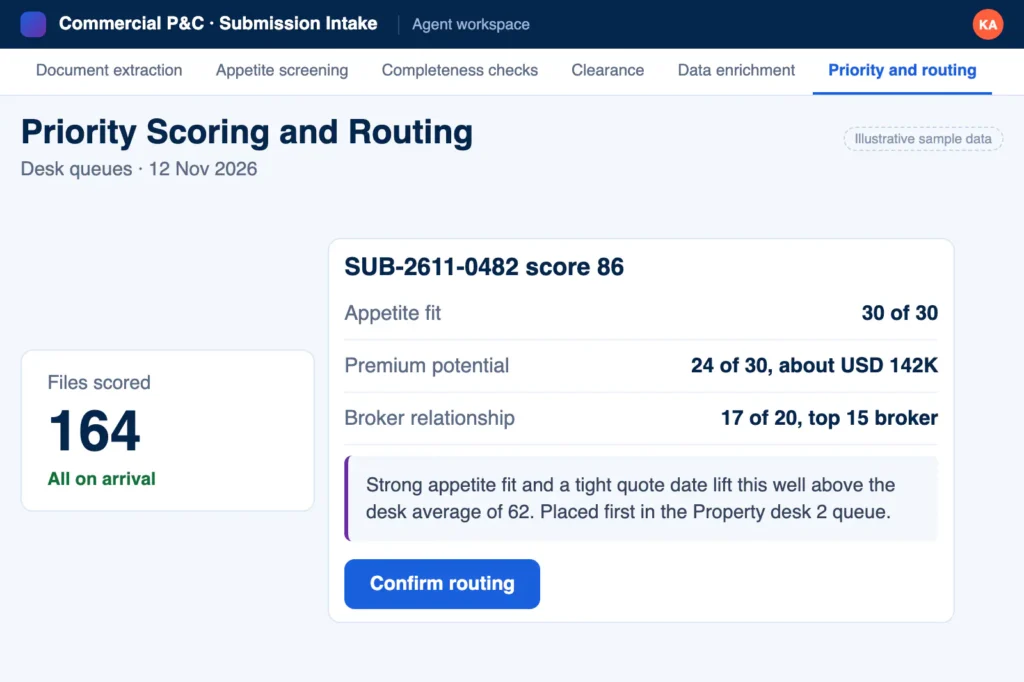
Priority Scoring and Routing
Each submission is scored on appetite fit, premium potential, broker relationship, and due date, then routed to the right desk in order.
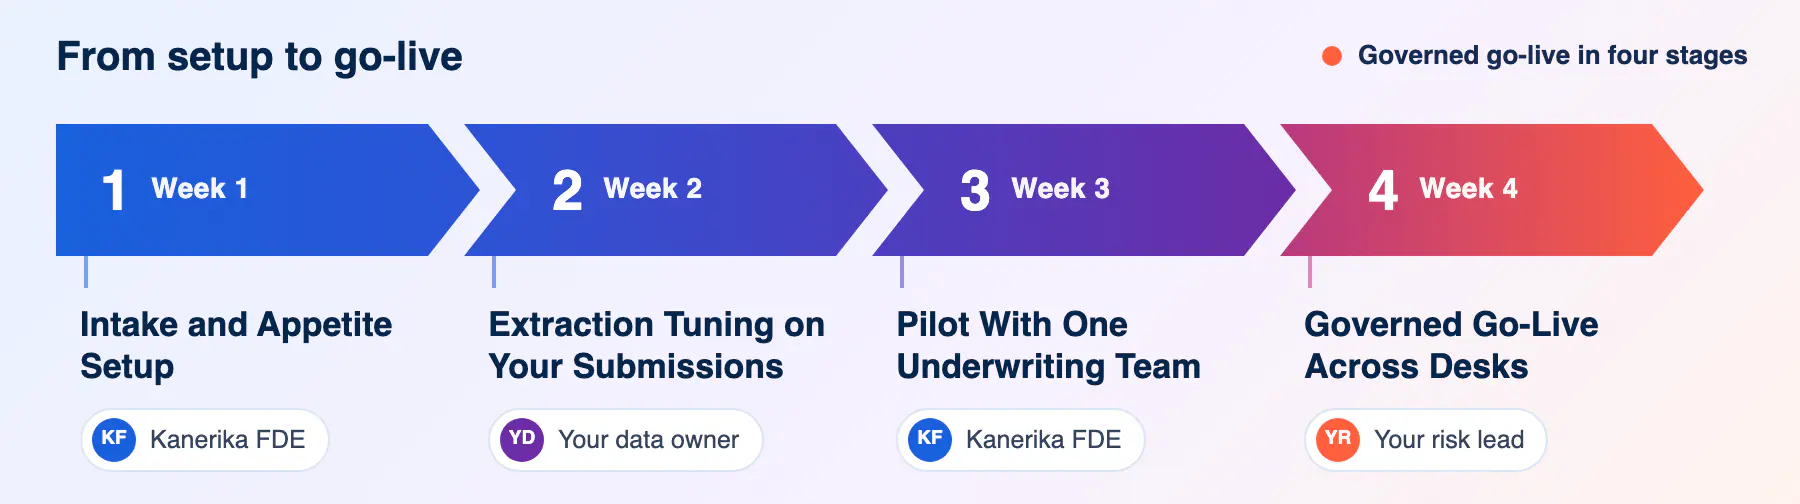
Deploy an Underwriting Intake Agent in Weeks
Intake and Appetite Setup
We connect the submission inbox and document stores, then encode your appetite guide and completeness rules with your underwriting leaders.
Extraction Tuning on Your Submissions
Models are tuned on your historical submissions, broker formats, and lines of business, then validated against files your team already worked.
Pilot With One Underwriting Team
One desk runs live intake with underwriters reviewing every output. Scoring and routing rules tighten from real submissions.
Governed Go-Live Across Desks
The agent rolls out across lines and regions with access controls, audit trails, and performance reporting in place.
Where Underwriting Automation Pays Off First
New Business Submission Triage
Every inbound submission is extracted, screened, and scored the day it arrives, so the best risks get quoted before competitors respond.
Renewal File Preparation
Expiring terms, updated exposures, and loss history are assembled ahead of the renewal date instead of in a last-week scramble.
Loss Run Summarization
Multi-carrier, multi-format loss runs are consolidated into a single loss history with frequency and severity patterns laid out.
SOV Standardization
Schedules of values in any spreadsheet layout are normalized into your data model, with missing COPE fields called out per location.
Appetite Pre-Screening at the Front Door
Clearly out-of-appetite risks are flagged on arrival with a drafted decline, so underwriters spend their time on business you actually want.
Broker Follow-Up Drafting
Requests for missing information go out the same day, in your house style, instead of waiting for an underwriter to find a free hour.
Segment Fit Across Insurance
Commercial P&C Carriers
High submission volumes across property, casualty, and package business, where triage speed decides which risks you even see.
MGAs and MGUs
Lean teams writing on delegated authority, where intake capacity caps premium growth more than appetite does.
Specialty and E&S Lines
Unusual risks arriving as unstructured broker narratives that standard intake tooling cannot read.
Workers Compensation Writers
Payroll schedules, class codes, and loss runs extracted and checked before the file reaches an underwriter.
Group Benefits and Life
Census files and plan documents structured on arrival, with gaps chased early enough to keep effective dates.
Reinsurance Teams
Cedent submissions and bordereaux summarized so treaty underwriters start from exposure facts, not PDF archaeology.
Why Underwriting Teams Choose Kanerika
Built by Kanerika's 300+ engineers, who have delivered for 100+ enterprise clients. Live in weeks, on your own data.
Applications, loss runs and broker emails are read and turned into structured risk data.
Missing information is spotted on arrival, with a follow-up email ready for the underwriter to send.
Addresses and exposures are checked against the data sources our team already uses.
Proof Points From Kanerika Insurance and Document AI Work
Insurance Reporting Modernization with Power BI
Impact:
- Real-Time Report Availability
- Elimination of Manual Reporting Tasks
- Improved Accuracy and Data Consistency
90% Faster Vendor Selection with LLM Agreement Processing
Impact:
- 82% Reduction in manual processing time
- 75% Increase in cloud integration efficiency
- 90% Boost in vendor selection
36% Cost Savings with AI/ML-Powered RPA in Insurance
Impact:
- 20% Reduction in claim processing time
- 25% Improvement in operational efficiency
- 36% Increased cost savings
FAQs
An underwriting intake agent reads inbound submissions, extracts risk data from forms, loss runs, SOVs, and broker emails, checks appetite and completeness, and routes a triaged file to the right underwriter. It drafts broker follow-ups for missing information and logs every step. Kanerika builds and runs the agent inside your own environment.
The agent handles ACORD applications, loss runs in carrier-specific formats, schedules of values in varied spreadsheet layouts, financial statements, and unstructured broker emails with attachments. During setup, Kanerika tunes extraction on your actual submission history, line by line of business, so the formats your brokers really send are covered rather than an idealized sample.
No. The agent brings automation in insurance underwriting to the intake work, while risk judgment stays with people. It prepares, screens, and prioritizes submissions, and it drafts communications for review. Quoting, pricing, declining, and referral decisions stay with your underwriters. Appetite flags come with the rule and the evidence behind them, so an underwriter can override any recommendation, and every override is logged for audit and later tuning.
Your appetite guide is encoded as explicit rules covering class of business, geography, limits, exposures, and exclusions. Each submission is checked against those rules on arrival, and the result states which rule matched and why. When your appetite changes, the rules change with it, in your control, without retraining or vendor tickets.
The agent lists exactly which fields are missing against your completeness standards, then drafts a broker email requesting them in your house style. The underwriter reviews and sends it, and the file is parked with a follow-up reminder rather than lost in an inbox. Response documents are extracted and merged into the same file automatically.
Everything stays in your environment. Submissions, extracted fields, scores, and broker correspondence remain in your tenant on Azure, AWS, GCP, or on-premise infrastructure, and nothing trains outside models. Kanerika holds SOC 2 Type II, ISO 27001, ISO 27701, and ISO 9001:2015 credentials, and the agent inherits your existing access controls.
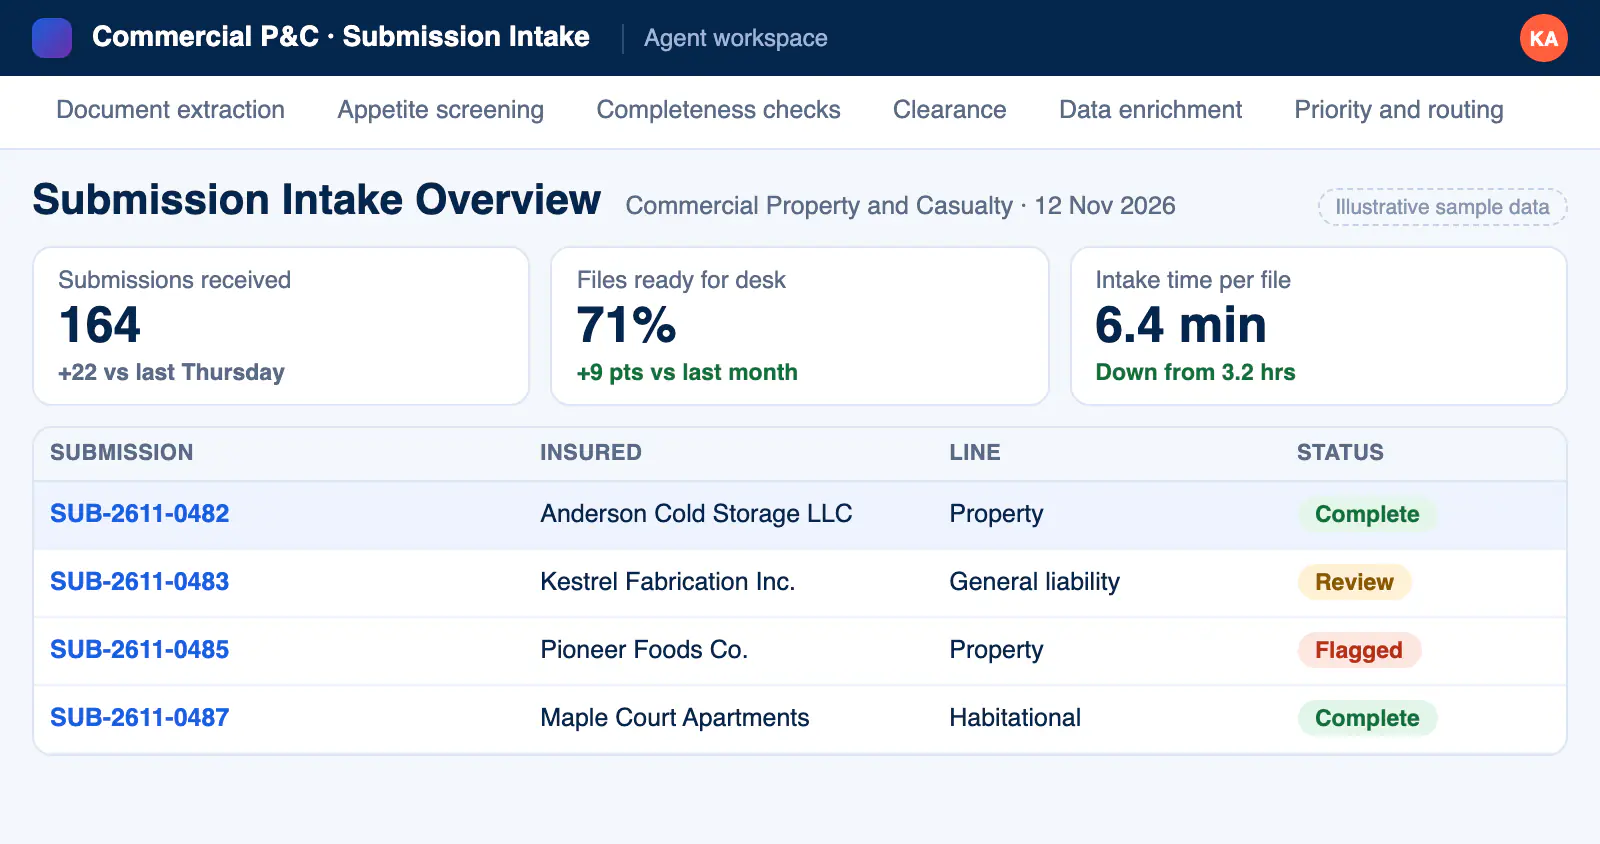
Intake happens before a policy exists. This agent works the front of the funnel, turning raw submissions into triaged, quote-ready files for underwriters. Kanerika’s insurance coverage verification agent answers a different question, whether an existing policy covers a specific situation, during service and claims conversations. Many insurers deploy them separately.
Most teams reach a live pilot within weeks. Kanerika connects the submission inbox, encodes your appetite and completeness rules, tunes extraction on your historical submissions, and then runs a pilot with one desk reviewing every output. Go-live across other lines follows once accuracy and routing hold up on real broker traffic.
Look for software that reads the documents brokers actually send, from ACORD applications and loss runs to SOVs and unstructured emails, and links every extracted field to its source page. It should check appetite with stated reasons, list missing data on arrival, catch duplicate submissions across desks, and route files by priority. Kanerika’s agent does this inside your environment, tuned on your own submission history, with underwriters keeping every decision.
Let’s Transform Your Business