TL;DR
Data migration in fintech works best when live payment and ledger systems load history early and sync changes until cutover. A single cutover window suits only small, bounded systems that pass rehearsal. Reconcile every balance to the cent before you switch. Map each US rule, such as GLBA and PCI DSS, to the evidence you must keep. Rehearse the full cutover at least twice and agree in advance when you would roll back. Automation speeds up mapping and checks, but finance and compliance still sign off.
Key Takeaways
- Scope the move by data class, because ledgers, transaction history, card tokens, KYC records, loan books and model features carry different risks.
- Treat every regulation as a list of evidence to keep, so each item has one named owner.
- Move card tokens through the vault or processor export so the cardholder data environment never grows.
- A bulk reload rarely fits a payment platform’s outage window, so preload history and stream changes until the freeze.
- Write the reconciliation design and sign-off owners first, because it decides when cutover is allowed.
- Parallel runs and reconciliation are the two cost lines that plans undercount most often, so budget them first.
When the Sponsor-Bank Contract Has an End Date
Picture a card and lending fintech that has outgrown its processor, so it must move. The new processor and partner bank are signed, while the old contract ends on a fixed date. Every ledger balance, card token and KYC file must be live on the new stack before then.
The deadline is fixed, but the data plan is not. Nobody yet knows how long the history takes to load or how the two ledgers will be proven equal. The team also has not decided who signs off for the auditors.
That gap is where a fintech migration goes wrong. Nearly every one of the common data migration challenges starts there. The plan has to answer three questions at once: can we prove compliance, can we contain the risk and can we finish on time? The sections below build that plan one decision at a time, starting with scope.
What Data Migration in Fintech Covers
At its core, data migration in fintech is the move of financial records from one system to another while money keeps flowing. The records include ledgers, payments, card tokens, identity files and loan books. Each one must arrive complete and correct, and the team must also be able to prove it.
What sets it apart from a generic database move is the proof. For example, a retailer can tolerate a missing product description for a day. Lenders cannot tolerate one missing repayment, because that error reaches a customer statement, a regulator report or both.
That is why a clear strategy comes before the first extract. Without one, teams move data first and look for proof later, which is how a missing repayment reaches a customer statement. With one, each decision about approach, timing and evidence follows from the same few rules, and every sign-off has a home.
The Data That Moves
Start the scope with data classes rather than systems. One core platform often holds four classes at once, and one class, such as KYC records, may sit across three tools. The table shows what makes each class hard and who usually owns it, so you can assign owners early.
| Data class | What makes it hard | Usual owner |
|---|---|---|
| General ledger and sub-ledgers | Balances must match to the cent; posting rules live in code | Finance and controllership |
| Payment and transaction history | High volume, in-flight items, years of retention | Payments operations |
| Card data and tokens | PCI DSS scope; tokens are tied to a vault or processor | Security and the card program team |
| KYC and AML records | Documents, screening results and audit trails must stay linked | Compliance |
| Loan books and servicing data | Accrual, fee and payment schedules depend on stored logic | Lending operations |
| Analytics and model features | Fraud and credit models break if feature definitions drift | Data and risk analytics |
Core-System Migration vs Analytics and AI Platform Migration
Two kinds of project share the same name, but they carry different risks. A core-system migration moves the records that run the business, so a mistake changes what a customer owes. An analytics or AI platform migration moves copies of that data, so a mistake changes a report or a model score.
| Factor | Core-system migration | Analytics and AI platform migration |
|---|---|---|
| Downtime tolerance | Minutes to a few hours, often overnight | Hours to days, with reports frozen |
| Reconciliation standard | Zero difference on balances and ledger totals | Agreed tolerance on aggregates |
| Regulator exposure | Direct: statements, notices, safeguarding | Indirect: regulatory reports built on the data |
| Typical approach | Initial load plus CDC, rehearsed cutover | Phased by domain, parallel reports |
This guide focuses on the data layer underneath both, since that is where balances live. If the reporting layer is your next step, the guide to BI migration for financial services covers dashboards, semantic models and report sign-off.
Checklist
Data Migration Checklist
A step-by-step checklist for scoping, mapping, validating and cutting over a data migration, so nothing in the ledger or payment estate is missed.
Get the Checklist →Why 2026 Raises the Stakes
Money now moves around the clock, so the overnight batch window that once hid a migration is shrinking. Instant payment rails, open-banking data access and a single active card security standard all raise the cost of a messy cutover. Here are the points that change a fintech migration plan, so check each one against yours.
- According to the Federal Reserve, FedNow settled 6,376,467 payments worth $370.9 billion in 2026:Q3, with value up 35.0% on the prior quarter.
- The Clearing House’s RTP network carries payments of up to $10 million, 24/7/365, and has handled over 1.8 billion transactions since 2017.
- On Oct 22, 2024, the CFPB released its personal financial data rights rule. It opened a reconsideration on Aug 22, 2025, and its compliance dates are on hold while that review runs.
- PCI DSS v4.0.1 is the only active version of the card standard, since v4.0 was retired on Dec 31, 2024.
For a migration team, each point also has a direct effect. Instant rails remove the quiet night, so the cutover window shrinks. Most fintechs also rely on secure payment getaways to process transactions across digital channels and third-party services. Each gateway and its API keys are one more integration to retest at cutover. Open-banking access is still coming, so build the new platform so data-sharing APIs can be added without another migration. Finally, the card standard means tokens and the tooling that touches them stay inside a tightly scoped environment.
Case Study
60% Faster Analytics with Informatica to Alteryx
A global fintech firm moved legacy Informatica workflows that fed fraud analysis and regulatory reporting to Alteryx with FLIP, gaining 45% faster reporting cycles and 38% lower maintenance costs.
Read the Case Study →US Regulations and Controls That Shape the Migration
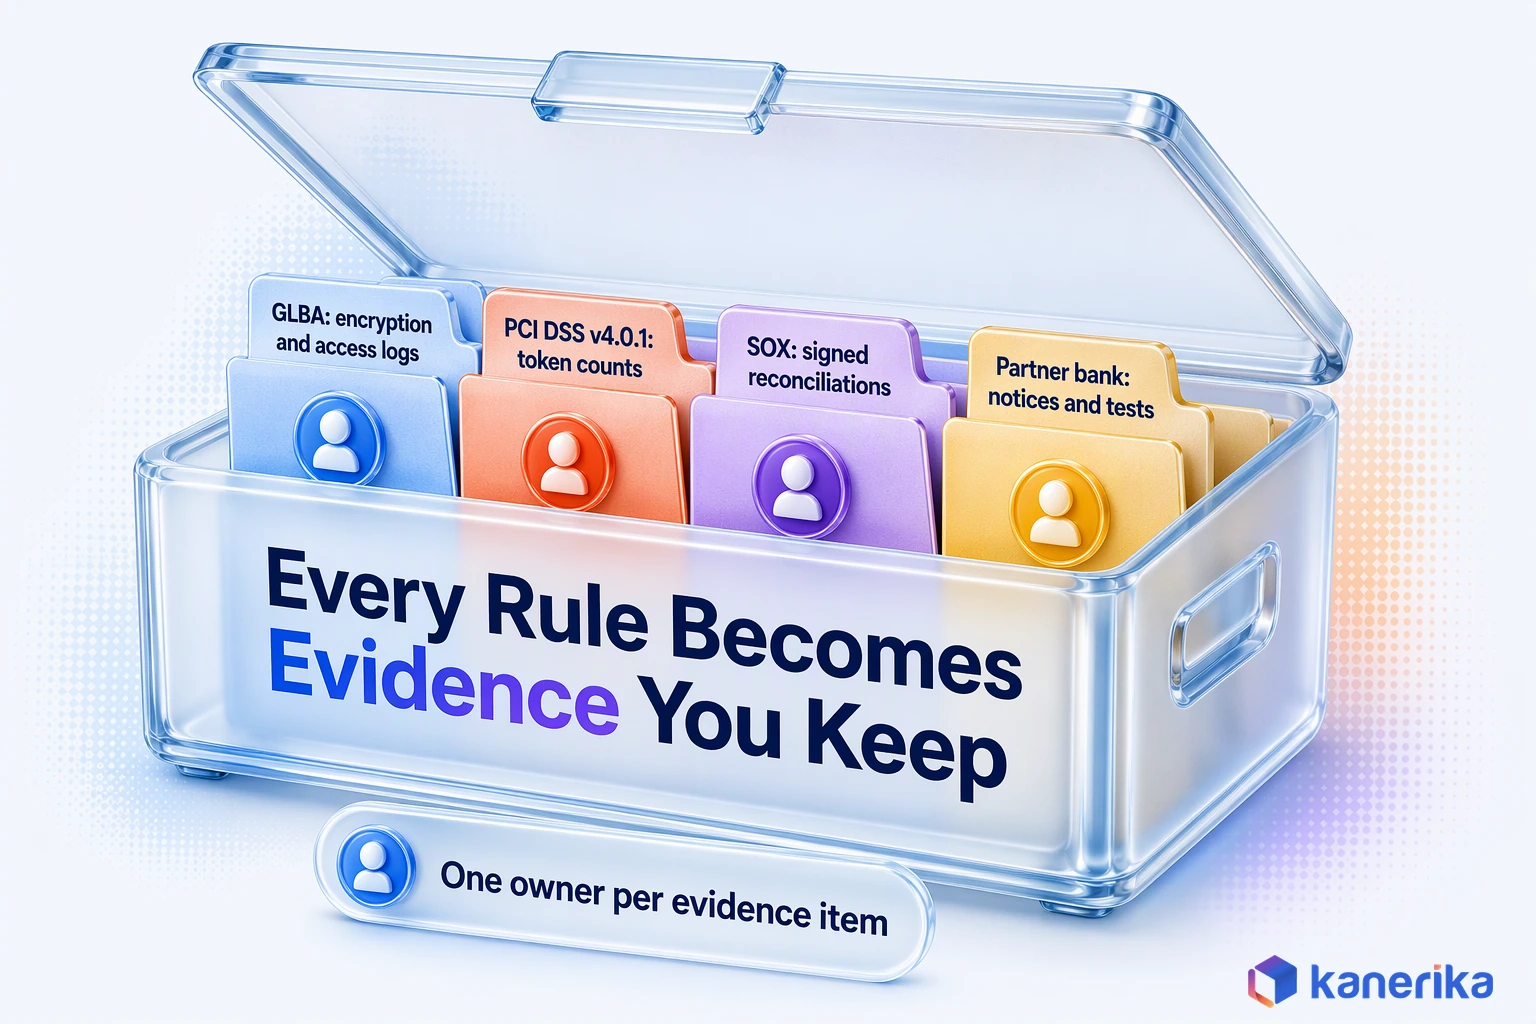
Every regulation that touches a fintech migration comes down to the proof you keep. Each obligation turns into a short list of evidence: an access log, a reconciliation report, a signed approval or a notice. When you plan that evidence first, the audit becomes a filing exercise.
A neobank moving its deposit ledger shows how this works. GLBA asks how customer data was protected in transit and at rest. SOX asks who approved the change and who reviewed the balances. Then the partner bank asks how its third-party risk team was kept informed.
Obligation Map
Use the map below as a starting point, then confirm scope with counsel. Not every row applies to every fintech, and license conditions can also add duties that are not listed here.
| Obligation | Applies to | What it means during migration | Evidence to keep |
|---|---|---|---|
| GLBA Safeguards Rule | Non-bank financial institutions | Encrypt customer data in transit and at rest; report to the FTC if 500 or more consumers are affected | Encryption settings, access logs, incident runbook |
| PCI DSS v4.0.1 | Anyone storing, processing or transmitting card data | Keep the cardholder data environment small; never detokenize to move data | Scope diagram, token counts, tool inventory |
| SOX IT general controls | Public companies and their key systems | Change approval, access review and reconciliation sign-off | Change tickets, signed reconciliations |
| Interagency Guidance on Third-Party Relationships | Banks and their fintech partners | The partner bank oversees how your migration affects its customers | Notices, due diligence answers, test results |
| NYDFS 23 NYCRR Part 500 | Entities licensed in New York | Cybersecurity program covers the new systems | Risk assessment, access controls |
| SEC Regulation S-P | Broker-dealer and adviser fintechs | Customer records stay protected through the move | Policies, incident response records |
| GDPR | Firms holding EU personal data | Transfers and storage locations stay lawful | Data map, transfer records |
Dates That Matter and the Partner-Bank Row
Two rows deserve dates. Under GLBA, the FTC amended the Safeguards Rule notification requirement, effective May 13, 2024, for events affecting 500 or more consumers. The Fed, FDIC and OCC issued final joint guidance on third-party relationships on June 6, 2023, and it names relationships with fintech companies.
Of the two, the partner-bank row often surprises teams because it reaches beyond your own walls. Your migration is a change in a critical third-party service for the bank, so its risk team may want test results before you cut over. The governance owners behind this work, such as data stewards, are described in the guide to data governance in banking.
Card Data and Tokens: Keep the CDE Small
Card data is where a migration can quietly expand audit scope if nobody watches it. The safe pattern is to move tokens, not card numbers. Use the token vault or processor bulk export when one exists. That way, raw card numbers never pass through your migration tooling.
Detokenizing to move data is the mistake to avoid. It pulls ETL servers, staging tables and logs into the cardholder data environment, often for months. Keep migration tools outside that boundary where possible, count tokens on both sides and have the security lead sign the count.
KYC and Identity Records: Keep the Trail Intact
KYC files are more than a customer table. Each record links an identity document, a screening result and a risk rating, together with an audit trail of who reviewed what. A migration that moves the table but drops those links leaves compliance unable to answer an examiner.
Treat each customer’s KYC history as one unit, so it moves together. Carry the original timestamps and reviewer names rather than the migration date. Then sample a set of files in both systems and ask a compliance analyst to confirm that the full story still reads the same way.
Sanctions screening needs the same care, especially at go-live. If the new platform rescreens every customer on day one, alert volumes can spike and swamp the team. Agree in advance whether to carry prior results forward or rescreen in planned batches.
Who to Notify Before Cutover
Notices take longer than code, so start them early. Below is the usual order for a US fintech with a partner bank.
- Your sponsor or partner bank, under its third-party risk process.
- The card network and processor, if card programs or BIN routing change.
- Internal and external auditors, so they can agree the evidence plan in advance.
- Regulators, where a license condition requires notice of a system change.
- Customers, if account numbers, statements or login steps will change.
Each notice needs an owner and a date on the cutover plan before work starts. A missed bank notice can delay go-live by weeks, even when the data is ready.
Talk to Kanerika
Planning a Fintech Platform Move?
Kanerika helps fintech teams map obligations to evidence, design reconciliation and size the cutover window before the first load. A short working session turns the plan into dates and owners.
Talk to a Migration Expert →How a Fintech Data Migration Works, Step by Step
A fintech data migration runs as a sequence of gated steps, and each step ends with evidence someone signs. The order matters because later steps depend on earlier proof. Here is the sequence at a glance, and then what happens inside each step.
- Inventory sources, consumers and financial dependencies.
- Profile, cleanse and map the data.
- Load history, then sync changes with change data capture (CDC).
- Reconcile every balance and control total.
- Rehearse, cut over, run hypercare and retire the old system.
Inventory Sources, Consumers and Financial Dependencies
The inventory lists every system that holds data, as well as every process that reads it. Teams usually find the sources quickly. The consumers take longer, because a nightly file to a regulator or a fraud model’s feature feed is easy to forget.
| System | Downstream consumers | Owner |
|---|---|---|
| Core ledger | Regulatory reports, month-end close, statements | Finance |
| Payments hub | Daily reconciliations, ACH returns, fraud scoring | Payments operations |
| Card processor feeds | Disputes, rewards, settlement files | Card program team |
| KYC platform | Onboarding, sanctions screening, audit requests | Compliance |
| Loan servicing system | Credit bureau reporting, collections, investor reports | Lending operations |
Profile, Cleanse and Map
Profiling shows what the data looks like. For instance, you find null dates, duplicate customers and currency codes nobody remembers adding. Cleansing fixes what can be fixed in the source, and the rest then goes on a signed exceptions list.
Mapping is also where hidden logic surfaces, often late. Interest accrual on a loan book, for example, often lives in a stored procedure rather than a table. If the new platform calculates accrual differently, balances drift a few cents per account per month, and nobody notices until a customer complains.
The fix is to write the business rule down, then test it on real accounts in both systems and compare results. Fee logic, rounding rules and day-count conventions need the same treatment. Our guide to data migration techniques covers the mapping methods in more depth.
Data quality rules should travel with the data. Write each rule once, such as “every loan has a valid next payment date.” Then run it on the source, the staging copy and the target. A rule that passes in all three places is evidence; a rule checked only at the end is a surprise waiting to happen.
Load History, Then Sync Changes with CDC
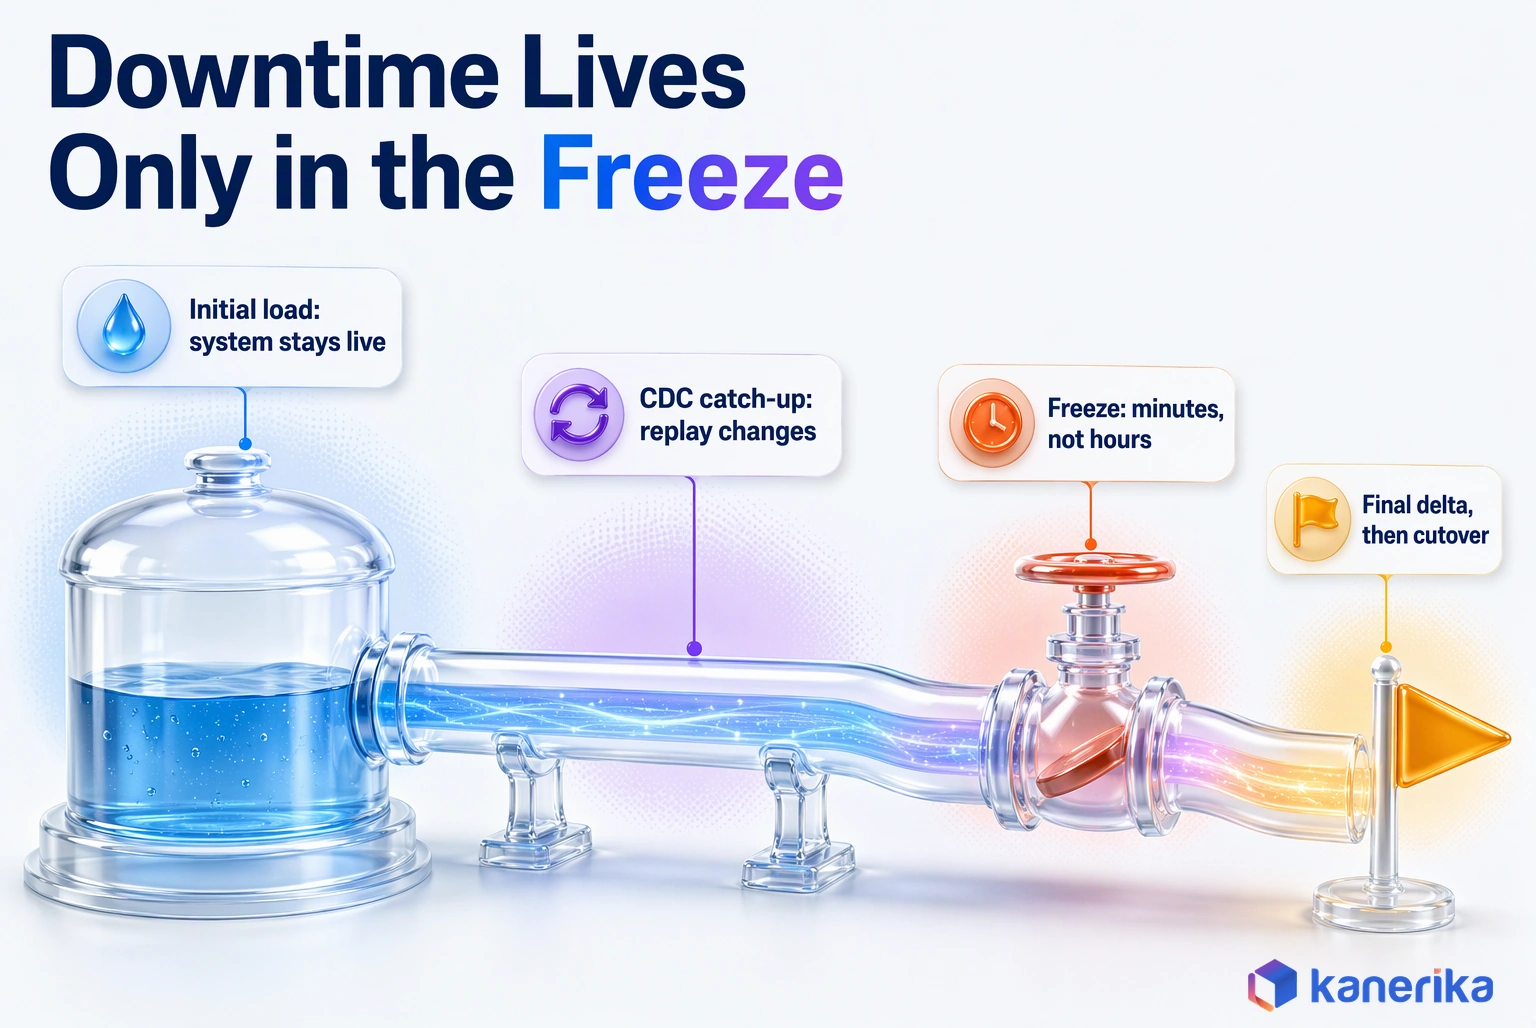
Fintech systems rarely stop long enough for a full reload, so teams split the move in two. First they load history while the old system stays live, then CDC streams every new change into the target until the freeze.
The pattern runs in four stages. First, an initial load copies the history, often over several days. CDC catch-up replays the changes made since that load began. A short freeze stops new writes, and the final delta applies the last changes before cutover.
Scale is the reason this pattern exists in the first place. Transaction tables in a growing fintech can hold years of records, and the volume rises every day the project runs. Loading history early spreads that weight over quiet days, so cutover night only carries the last few minutes of change.
The freeze is the only true downtime, and it is measured in minutes when CDC lag is small. That is why the CDC lag figure is the number that decides whether a cutover fits its window.
Reconcile to the Cent
Reconciliation proves the new system holds the same money as the old one before anyone signs. It is the step auditors read first, so design it before any data moves. Each check also needs a tolerance and a named person who signs it.
| Check | Tolerance | Who signs |
|---|---|---|
| Record counts by table and product | Zero difference, or explained exceptions | Data lead |
| Ledger control totals | Zero | Controller |
| Balance by account | Zero | Finance operations |
| Open items (pending authorizations, returns, disputes) | Zero unmatched | Payments operations |
| Token counts by card program | Zero | Security lead |
Run these checks in every rehearsal rather than only on cutover night. A reconciliation script that has passed three times is evidence. By contrast, a script run for the first time at 2 a.m. is a gamble.
Mock Runs, Cutover, Hypercare and Decommission
The last step turns a tested plan into a live system. It follows a fixed order so that nobody improvises under pressure.
- Run at least two full dress rehearsals on production-sized data, timed against the real window.
- List in-flight items at cutover, such as pending card authorizations and ACH returns, and decide which system settles each one.
- Write the rollback trigger and the person who calls it.
- Staff a hypercare window with finance, payments and support on call.
- Keep the legacy system read-only for the retention period your record rules require, then retire it.
Decommissioning is easy to postpone and costly to forget. A legacy system kept “just in case” still needs patches, access reviews and licenses. So put a retirement date in the plan from day one.
Migration Approaches Compared
There are four common ways to move fintech data, and they trade downtime against risk and cost. No approach wins everywhere, so the choice is a trade. The right one depends on how live the workload is and how much the business can tolerate a pause.
A payments switch that settles around the clock sits at one extreme. By contrast, an analytics store that refreshes nightly sits at the other. Most programs combine two approaches, for example a phased move by product with CDC inside each phase.
| Approach | Downtime | Risk | Cost | Fits |
|---|---|---|---|---|
| Big bang | One long window | High: everything moves at once | Lowest if it works | Small, bounded systems that pass rehearsal |
| Phased by product or segment | Several short windows | Medium: each phase is smaller | Medium, with temporary interfaces | Lenders and multi-product platforms |
| Parallel run | Near zero | Low for accuracy, high for effort | Highest: two systems run at once | Ledgers that need side-by-side proof |
| CDC trickle or strangler | Minutes at the freeze | Low to medium | Medium, with CDC tooling | Live payment and card platforms |
Parallel runs deserve a note, since they look safest. They give the strongest proof because both systems process the same day’s activity. They also double the operational load, so most teams cap them at one or two close cycles.
Cloud Platform Choice Comes After the Pattern
Teams often start by picking a cloud platform and then design the move around it. However, the better order is the reverse. Choose the migration pattern from the workload’s downtime and proof needs. Then choose the platform that supports that pattern well, which is the core of any data modernization plan.
Where the data lands still matters for analytics, governance and AI use. The guide to lakehouse architecture for financial services covers that target design in detail. For the wider platform picture, see our post on data platform migration.
Decision Framework: Which Approach Fits Your Workload
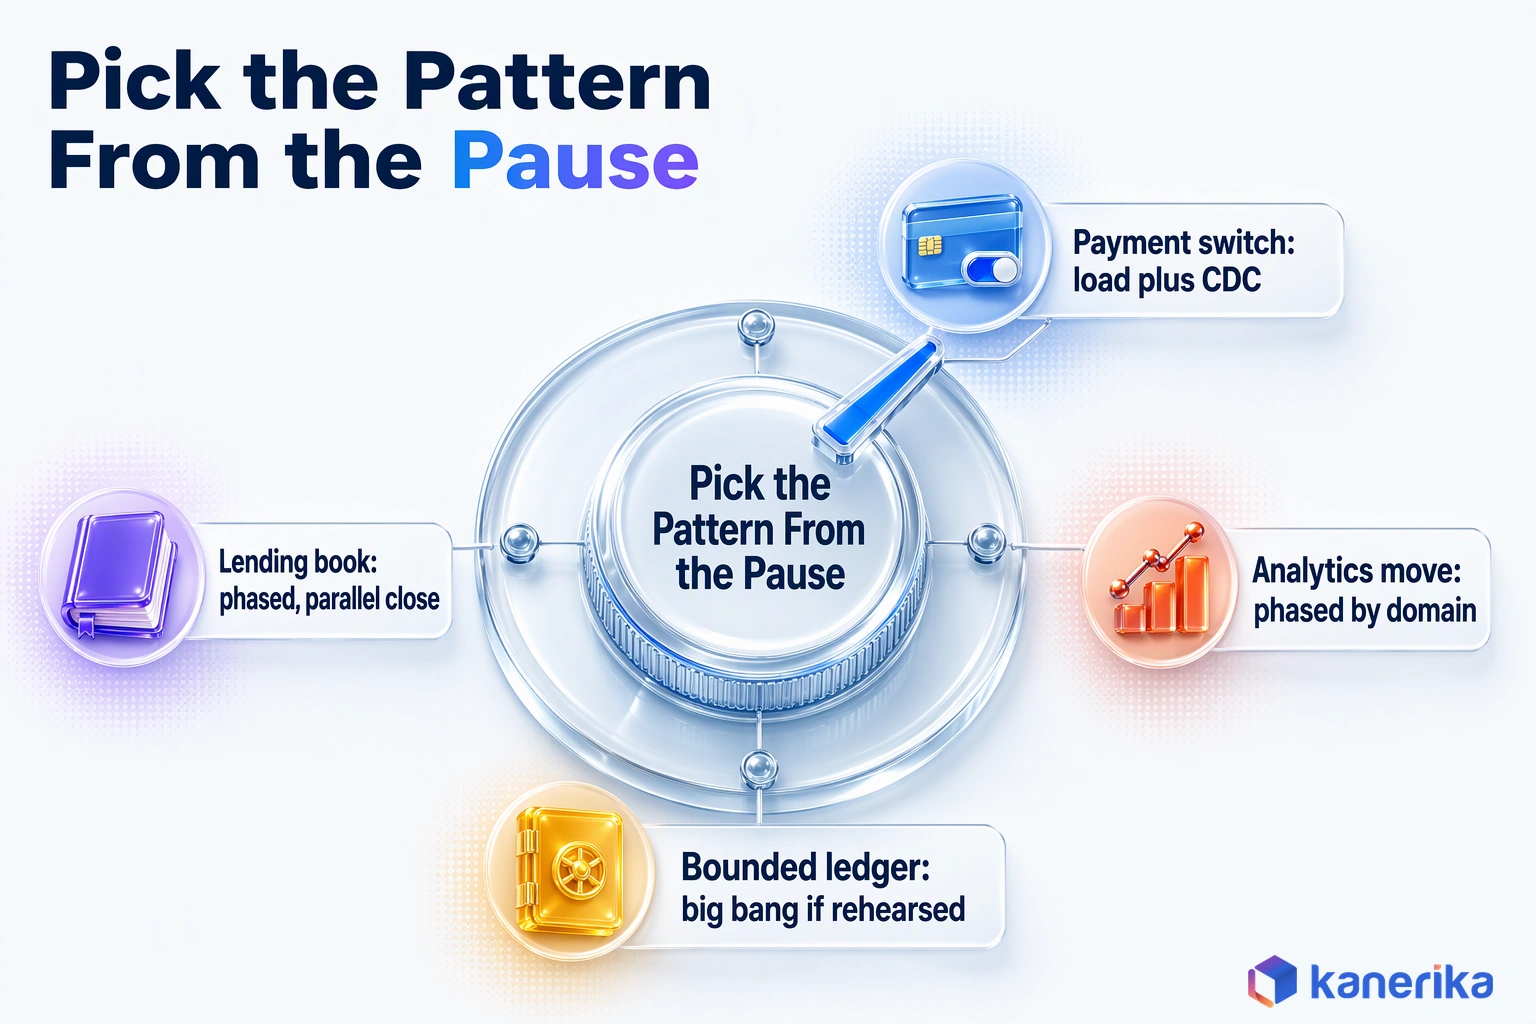
Choosing an approach is easier when you start from the workload, not the tool. Ask two questions: how long can this system pause, and how will you prove the result? Together, the answers point to one pattern in nearly every case.
| Scenario | Approach | Why |
|---|---|---|
| Live payment switch or card platform | Initial load plus CDC, rehearsed cutover | No safe long window; the freeze must be minutes |
| Lending book move to a new servicer | Phased by product, with a parallel close | Accrual logic needs side-by-side proof |
| Analytics or AI platform move | Phased by domain, parallel reports | Copies of data, so a longer window is acceptable |
| M&A consolidation of two ledgers | Phased by entity, then a single cutover per entity | Charts of accounts must be merged first |
A single-window cutover is still a valid choice, but only for bounded workloads. If a back-office ledger with modest volume passes two rehearsals inside its window, a big bang can be simpler and cheaper. Even so, live payment and ledger systems should not take that bet.
Five Gates Before You Approve the Approach
An approach is only approved when it has passed five gates. Each one is a yes or no question, and each has a document behind it.
- The reconciliation design is written, with tolerances and signers.
- A full rehearsal has finished inside the real window.
- Rollback has been tested on a rehearsal run.
- Every obligation is mapped to evidence and an owner.
- Partner, network and auditor notices have been sent.
Worked Example: A Four-Hour Cutover Window
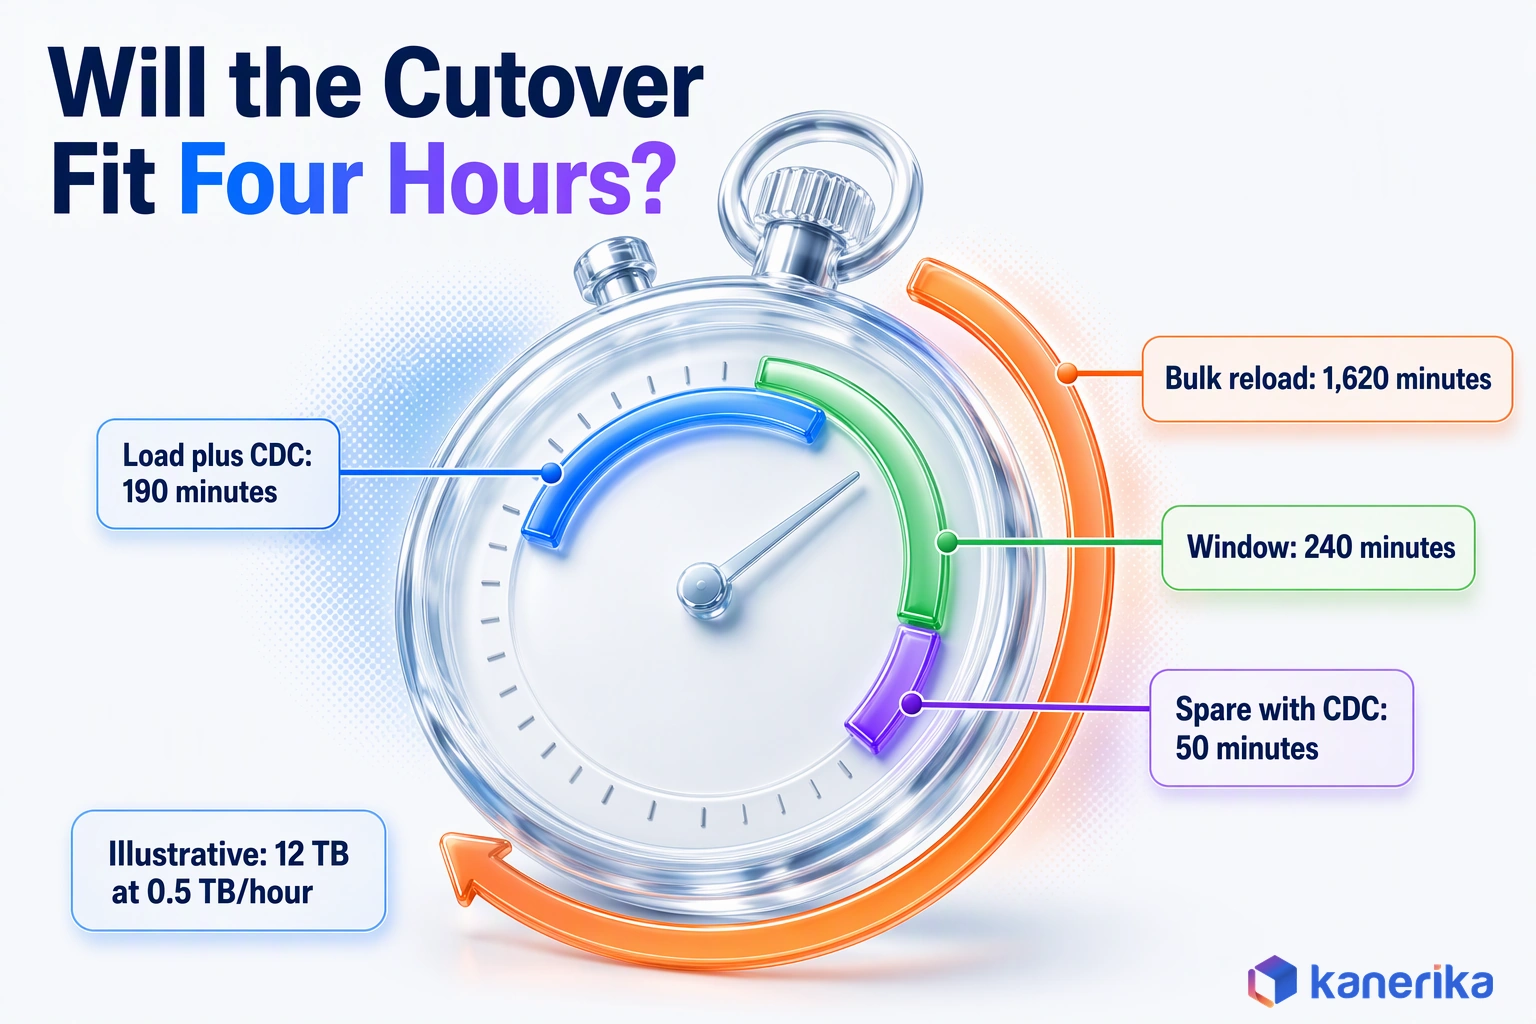
Numbers make the choice clear, so here is one case. The figures below are illustrative round numbers, not vendor benchmarks, so swap in your own rehearsal timings. Assume a card platform with 12 TB of ledger and transaction history and a four-hour overnight window.
Next, assume the team measures a sustained load rate of 0.5 TB per hour in rehearsal. A bulk reload would take 24 hours, which is six times the window. Even before reconciliation starts, the bulk-only plan has failed.
The CDC plan loads history over the prior two weeks while the old system stays live. At the freeze, only the final delta remains. The table then adds up what must happen inside the window.
| Cutover task (illustrative) | Bulk reload only | Initial load plus CDC |
|---|---|---|
| Data load inside the window | 1,440 minutes (12 TB at 0.5 TB per hour) | 10 minutes (final delta) |
| Reconciliation: control totals and balances | 90 minutes | 90 minutes |
| Smoke tests and partner connectivity | 45 minutes | 45 minutes |
| Go or no-go decision | 15 minutes | 15 minutes |
| Rollback reserve | 30 minutes | 30 minutes |
| Total against a 240-minute window | 1,620 minutes: fails | 190 minutes: passes with 50 to spare |
In short, the load step is what breaks the window. Once CDC removes the bulk load from cutover night, the remaining tasks fit with room for a rollback. If your final delta or reconciliation runs longer in rehearsal, the spare 50 minutes is the first thing to go.
Cost, Effort and Timeline: What Drives the Number
A fintech migration budget is driven by effort rather than licenses. The number grows with the count of data classes and the amount of hidden logic. It also grows with the proof each regulator or partner expects. Two plans for the same platform can differ widely because of these drivers.
The table breaks the work into packages so that gaps stand out. Use it to ask where your estimate is thin, rather than to compare dollar figures, which vary too much by scope to be useful here.
| Work package | Effort driver | What inflates it |
|---|---|---|
| Discovery | Number of systems and consumers | Undocumented feeds and spreadsheets |
| Mapping | Fields and business rules | Logic buried in stored procedures |
| Conversion | Volume and transformations | Format changes across product lines |
| Reconciliation build | Checks per data class | Late design, unclear tolerances |
| Rehearsals | Number of dress runs | Failed runs that need a redo |
| Parallel run | Close cycles run side by side | Manual comparison of results |
| Hypercare | Weeks of extra support | Defects found after go-live |
| Decommission | Retention and archive rules | Legacy kept live with no end date |
Plans undercount two lines most often, and both involve people. Parallel runs look cheap on paper, yet each cycle needs people from finance and operations to compare results by hand. Reconciliation looks like a script, but it is really a design task with sign-offs, and it grows with every data class.
What Sets the Timeline
Timelines follow the same logic. A single product on a modern source can move in a few months. In contrast, a multi-product core platform with a partner-bank change usually spans several quarters. Automation can shorten the middle of the plan, as our guide to migration accelerators for enterprises explains. What stretches a few months into several quarters is usually outside the data. A partner bank may open its test environment only in set windows, and each product needs its own parallel month-end close before sign-off.
Migration ROI Calculator
Estimate Your Migration ROI
Use Kanerika’s migration ROI calculator to compare effort, cost and timeline for an automated migration against a manual rewrite.
Calculate Migration ROI →Measure success the same way you approved the plan, against agreed numbers. The core measures are zero unexplained balance differences, on-time cutover inside the window and no missed partner or regulator notices. After go-live, track defects in hypercare and the date the legacy system is retired.
Where Fintech Migrations Fail and How to Recover
Fintech migrations tend to fail in a handful of known places, and each one gives an early signal. The matrix pairs each failure with the signal to watch, the control that prevents it and the trigger that should end the cutover.
| Failure | Early signal | Control | Rollback trigger |
|---|---|---|---|
| Reconciliation break at cutover | Rehearsal totals differ | Reconciliation designed and run in every rehearsal | Any unexplained balance difference |
| Third-party integration breaks | Partner test files rejected | End-to-end tests with the bank and processor | Settlement or authorization failures |
| Compliance finding after go-live | Evidence owner cannot produce a log | Obligation map with named owners | Not a rollback case; fix and report |
| Performance under real load | Slow queries in load tests | Production-sized rehearsal data | Payment latency above the agreed limit |
| Data quality surprises | Profiling exceptions keep growing | Signed exceptions list and quality rules | Exceptions above the agreed threshold |
Third-party breaks are the hardest to rehearse because the partner controls half the test. Book the bank’s and processor’s test windows early, and treat their sign-off as a formal gate. Firms in adjacent sectors face the same issue, as our guide to insurance data migration shows.
Knowing When to Roll Back
Rollback is a decision made before cutover night rather than during it. Write the criteria down, then name the person who calls it and agree the deadline for the call. After that time, the team fixes forward instead.
A good trigger is specific, so nobody can argue about it. “Any unexplained difference in ledger control totals at the go or no-go point” is a trigger. “If things look bad” is not, because tired people under pressure will always find a reason to keep going.
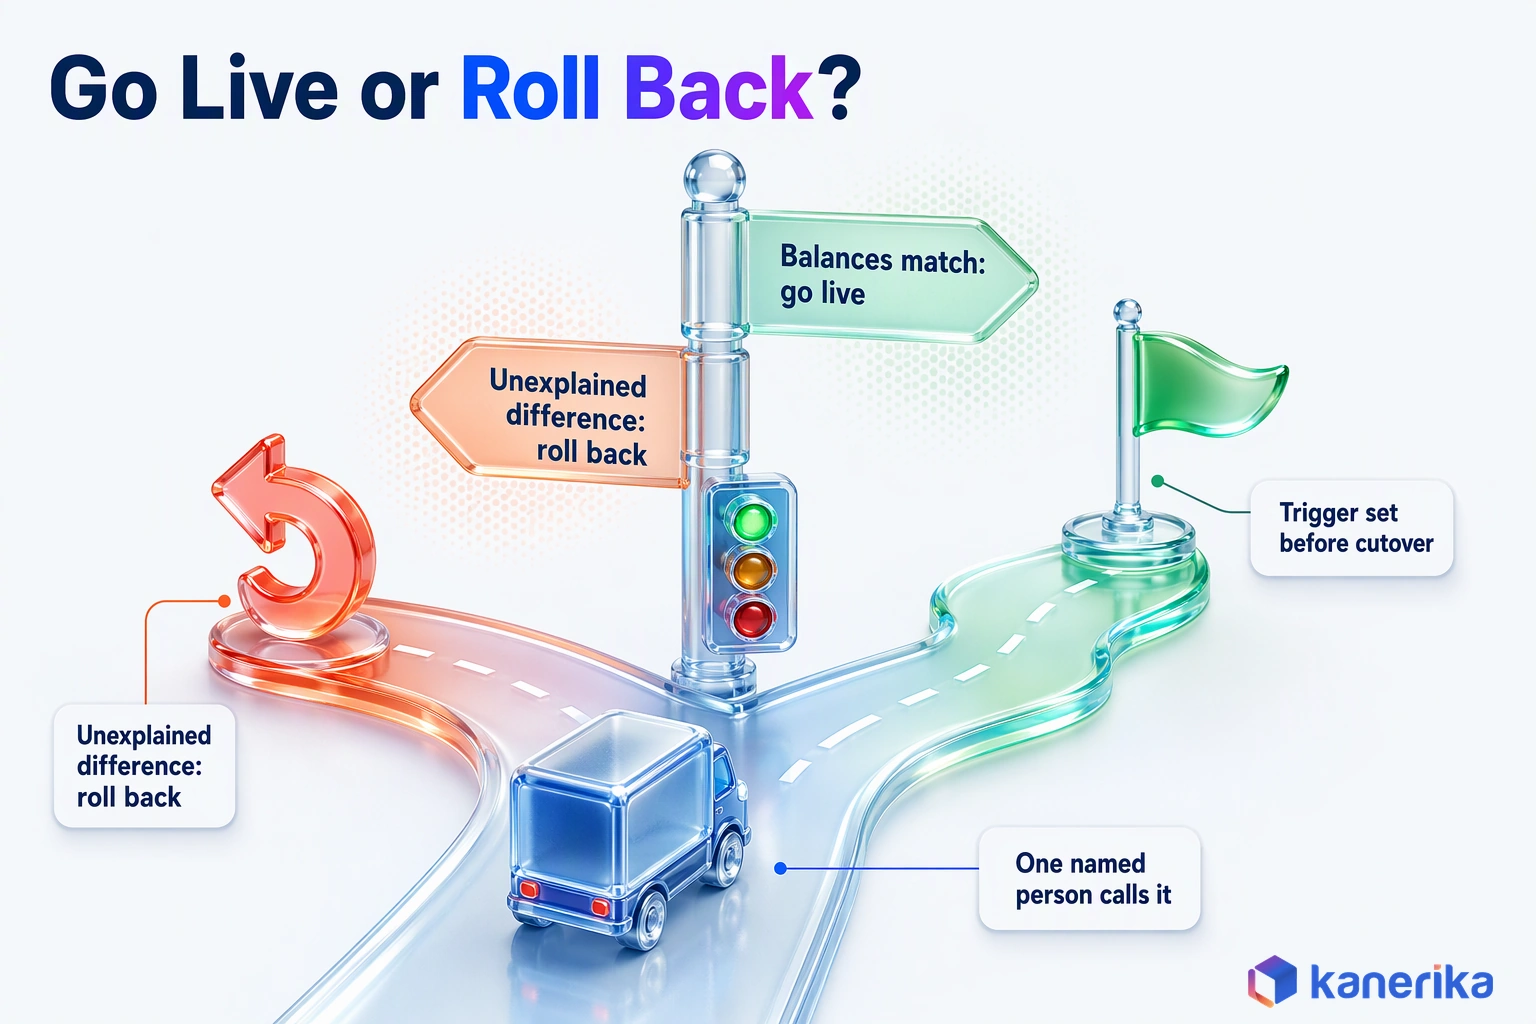
Rollback also needs a clean path back. Keep the legacy system frozen, not deleted, until the go or no-go call is made. Hold the final CDC position so you know exactly which changes landed in the new system. If the call is to roll back, any transactions taken on the new side must be replayed into the old one, so log them carefully.
Automation and AI in Fintech Migration
Automation earns its place in the repeatable parts of a migration, and people keep the judgment calls. Four techniques do most of the work, and each one also has a clear fintech use.
Automated mapping and code conversion read legacy ETL jobs and stored procedures, then produce target code for review. On a lending platform, that can mean converting hundreds of accrual and fee jobs instead of rewriting them by hand. Reviewers then focus on the logic the tool could not convert.
Automated reconciliation compares counts, totals and balances on every rehearsal run, so the evidence pack builds itself. Anomaly checks then scan migrated balances for odd patterns, such as one branch where every account is a cent higher. Data-quality rules finish the set by blocking a load when a field breaks an agreed rule.
Automation does not replace sign-off, though. A tool can show that two ledgers match, but a controller still signs the reconciliation, and a compliance lead still owns the evidence. The value is that people spend their time on exceptions.
Machine learning helps where fraud teams already use it, such as spotting outliers in large volumes. The post on AI in fraud detection explains that pattern, and the guide to RPA in banking covers the task automation around it.
How Kanerika Delivers Fintech Data Migration
Kanerika runs fintech migrations as a staged program, so every stage ends in signed evidence. The data migration services team pairs consultants with the FLIP migration accelerator, which automates 70-80% of the conversion work. Consultants redesign the 20-30% it cannot. On ETL migrations, the FLIP product page reports 70% less manual effort and 45% lower total cost.
- Assess and inventory with FLIP: catalog sources, jobs, consumers and obligations.
- Pilot one data domain: prove mapping and reconciliation on a bounded scope.
- Convert in waves: move products or entities in sequence, with CDC inside each wave.
- Reconcile and sign off: run the agreed checks and collect signatures.
- Cut over and retire: execute the rehearsed runbook, then decommission the legacy system.
One example shows the method in practice, in a fintech setting. A global fintech firm providing digital financial services across multiple markets ran legacy Informatica workflows that fed fraud analysis and regulatory reporting. Kanerika migrated those workflows to Alteryx with FLIP without disrupting either process.
According to the case study, the hard part was the batch-based Informatica setup, which needed heavy IT involvement for every report change. Alteryx self-service let analysts prepare data on their own, and reporting cycles ran 45% faster after the move. Kanerika’s banking and financial services work applies the same approach to ledgers and payment data.
Kanerika Service
Data Migration Services
Kanerika plans and runs fintech data migrations end to end, from inventory and mapping with FLIP to reconciliation, rehearsed cutover and legacy retirement.
Explore Migration ServicesFintech Migration Readiness Checklist
Use this checklist before you approve a cutover date. It covers compliance evidence, risk controls and the levers that keep the plan fast.
- Every data class has a named owner and a scope decision.
- Each obligation is mapped to evidence, and every evidence item has an owner.
- Card tokens move through the vault or processor export, with counts signed.
- Hidden business logic, such as accrual and fee rules, is written down and tested.
- The reconciliation design lists checks, tolerances and signers.
- History is preloaded and CDC lag is measured in rehearsal.
- Two full rehearsals have finished inside the real window.
- In-flight items have a settlement owner on both sides of cutover.
- The rollback trigger, decision maker and deadline are agreed.
- Bank, network, auditor and customer notices are sent and logged.
- Hypercare is staffed across finance, payments and support.
- The legacy system has a read-only period and a retirement date.
If you are new to the basics, start with what data migration involves. If you are comparing delivery partners for this work, our review of data migration companies lists what to ask them.
The Bottom Line on Data Migration in Fintech
Compliance, risk and speed stop pulling against each other once the plan is built in the right order. Map obligations to evidence, design reconciliation before the first load and rehearse until the cutover fits its window.
For live payment and ledger systems, that means an initial load plus CDC and a short, rehearsed freeze. Meanwhile, a single-window cutover suits only bounded workloads that pass rehearsal. Keeping compliance, risk and speed together comes down to one habit: every step proves itself before the next one starts.
Frequently Asked Questions
What Is Data Migration in Fintech?
Data migration in fintech is the move of financial records from one system to another while payments keep flowing. It covers ledgers, transaction history, card tokens, KYC files, loan books and model features. Each record must arrive complete and correct, and the team must be able to prove it to auditors, partner banks and regulators.
How Long Does a Fintech Data Migration Take?
It depends on scope and proof. A single product on a modern source can move in a few months. A multi-product core platform with a partner-bank change usually spans several quarters. Rehearsals, parallel runs and partner test windows often set the pace more than the data load itself, so plan them first.
How Do You Reconcile Financial Data After Migration?
Compare record counts, ledger control totals, balances by account, open items and token counts between the old and new systems. Set a tolerance for each check, which is zero for balances and ledger totals. Name the person who signs each one. Run the same checks in every rehearsal so cutover night holds no surprises.
Is Change Data Capture Enough for a Fintech Migration?
No. CDC keeps the target in step with the source, but it is only the sync mechanism. You still need mapping, quality rules, reconciliation, rehearsals and a tested rollback path. CDC also needs monitoring, because rising lag can push the final delta past the cutover window. Treat it as one part of the plan.
What US Regulations Apply to Fintech Data Migration?
Common ones include the GLBA Safeguards Rule, PCI DSS v4.0.1 for card data and SOX controls for public companies. Partner banks follow interagency guidance on third-party relationships. New York licensees follow NYDFS Part 500, and broker-dealer fintechs follow SEC Regulation S-P. Confirm which apply with counsel before the first load.
How Do You Migrate Card Data and Payment Tokens Under PCI DSS?
Move tokens, not card numbers. Use the token vault or processor bulk export to the new provider, so raw card data never passes through your migration tools. Never detokenize to move data, because that pulls servers and logs into PCI scope. Count tokens on both sides and have the security lead sign.
When Can You Decommission the Legacy System After Cutover?
Retire it only after hypercare ends, reconciliations are signed and no rollback path is needed. Before that, keep it read-only for the retention period your record rules require, or archive its data in a searchable store. Set the retirement date in the plan from the start, because legacy systems kept running still cost money.
Why Is a Clear Migration Strategy Important for Fintech Companies?
A clear strategy sets the order of decisions. Without one, teams move data first and look for proof later, which is costly in a regulated business. With one, the approach, timing, evidence and sign-off owners follow the same rules. That keeps compliance, risk and speed aligned instead of trading one for another.
How Does Security Impact Fintech Data Migration?
Security shapes how data moves, not just where it lands. Encrypt data in transit and at rest, limit tool access and log every action. Move card tokens through the vault, never as raw numbers. Keep each KYC record linked to its documents, screening results and reviewer history so compliance can still answer an examiner.
What Scalability Challenges Do Fintech Organizations Face During Migration?
Transaction tables grow every day the project runs, so a full reload rarely fits an outage window. Instant payment rails also remove the quiet overnight period. Teams handle this by loading history early, streaming changes with CDC and testing the new platform on production-sized data before cutover, including peak payment volumes.
How Can Fintech Firms Ensure Data Quality During Migration?
Profile the source first to see the real data, not the schema. Write quality rules once and run them on the source, staging copy and target. Fix what you can at the source and keep a signed exceptions list for the rest. Then reconcile balances and control totals on every rehearsal run.
Can Fintech Data Migration Be Done Without Downtime?
Near-zero downtime is possible for most live systems. The team loads history while the old platform stays live, then streams changes with CDC until a short freeze. Only the final delta moves during that freeze, which can take minutes. A true zero is rare, because reconciliation and go-live checks still need time.
How Do Fintech Companies Measure Migration Success?
Success means zero unexplained balance differences, a cutover that finished inside its window and no missed partner or regulator notices. After go-live, teams track defects found in hypercare, customer complaints tied to the move and the date the legacy system was retired. Each measure should be agreed before the first load.
What Is the Best Migration Approach for a Live Payment Platform?
For a live payment platform, use an initial load plus change data capture and a rehearsed cutover. History moves while the platform keeps running, and only a short freeze is needed at the end. A single-window big bang suits only bounded systems that have passed full rehearsals inside the real outage window.
How Much Does a Fintech Data Migration Cost?
Cost is driven by effort rather than licenses. The main drivers are the number of data classes, hidden business logic, reconciliation design, rehearsals and parallel runs. Parallel runs and reconciliation are the lines plans undercount most often. Automation can cut mapping and conversion effort, but sign-off work still needs finance and compliance time.