TL;DR
Of the 10 AI use cases in finance, start with accounts payable automation unless fraud loss is your bigger cost. The full list runs from fraud monitoring, AML and credit scoring to cash forecasting, close, reporting, documents, assistants and portfolio analytics. Document intelligence and FP&A reporting are equally fast alternatives, since Gartner puts data extraction and report creation in its 9-to-10-month payback group alongside AP. If fraud loss is rising, fund real-time transaction monitoring first, and if liquidity swings, fund cash forecasting. Leave credit models and trading signals until model risk management and validation are in place. Score each candidate on value, data readiness, risk, integration effort and time to value, then set pass and stop criteria.
Key Takeaways
- Ten AI use cases in finance hold up in production, split between financial services firms and the corporate finance function.
- AP and invoice processing, document intelligence and FP&A reporting sit in Gartner’s fastest payback group, generally 9 to 10 months.
- Fraud monitoring goes first when fraud loss is the bigger number, and cash forecasting goes first when liquidity is volatile.
- Generative AI drafts narratives and summaries from governed numbers, but it should never compute the numbers itself.
- Credit models and trading signals carry the highest model risk, so fund them after validation and monitoring exist.
- SR 26-2, Reg B adverse action rules, the NIST AI RMF and the EU AI Act set the controls a finance AI system needs.
A Treasury Desk at 7 a.m.
The treasury analyst logs in before the markets open. Her first job is the daily cash position, but it lives in nine spreadsheets exported from four systems. By the time she has reconciled the inflows, chased one missing branch file and checked the totals twice, the funding window is half gone.
Nothing in that routine is especially hard. It is slow, manual and repeated every morning, so it makes a good place for AI to start. A forecast model can predict the day’s inflows and outflows from history, while a data layer pulls the sources into one view. The analyst then keeps the decision and loses the copy and paste.
That is the pattern behind every finance AI project that survives its pilot. In practice, the model matters less than three questions: which decision does it change, what data does it need and who approves the output? This guide walks through 10 AI use cases in finance with those three answers, then shows how to pick the first one to fund.
What AI in Finance Covers: Financial Services vs the Finance Function
AI in finance means two different jobs, so the one that applies to you depends on where you sit. A bank, insurer or lender uses AI on its products and customers, such as payments, loans, claims and accounts. A corporate finance team uses it on its own back office, such as invoices, the close, forecasts and board reporting.
The split matters because the data, the rules and the risk all differ. A credit model at a lender makes decisions about consumers, so fair lending law and model risk guidance apply to it. An AP model at a manufacturer routes supplier invoices, so the main controls there are segregation of duties and a clean audit trail.
Some AI use cases in finance sit in both worlds. For example, fraud detection protects a bank’s card portfolio and a company’s vendor payments alike. Document intelligence also reads loan files at a lender and contracts in a CFO’s office. The table below sorts the common uses by who owns them.
| Financial services uses (banks, insurers, lenders) | Finance function uses (the CFO’s team) |
|---|---|
| Card and payment fraud monitoring | Vendor payment fraud and duplicate checks |
| AML alert triage and KYC reviews | Accounts payable and invoice processing |
| Credit scoring and underwriting | Financial close and reconciliation |
| Customer and advisor assistants | FP&A variance commentary and reporting |
| Portfolio analytics and robo-advisory | Cash-flow and treasury forecasting |
Read the left column when you run a regulated institution and the right column when you report to a CFO. Treasury forecasting and document work show up on both sides, so the next table labels each use case by sector as well as by type.
AI Use Cases in Finance at a Glance
A one-page map makes the choice easier, because the 10 uses differ more in readiness than in ambition. Some need clean invoice data and pay back inside a year. Others need years of labeled history and a validation team before they can touch a real decision.
The time-to-value column follows a Gartner survey of 160 senior finance leaders, run from January to April 2026 and reported by CPA Practice Advisor. Data extraction, AP and AR automation and report creation generally delivered returns within 9 to 10 months. By comparison, data management, insight generation and forecasting took longer.
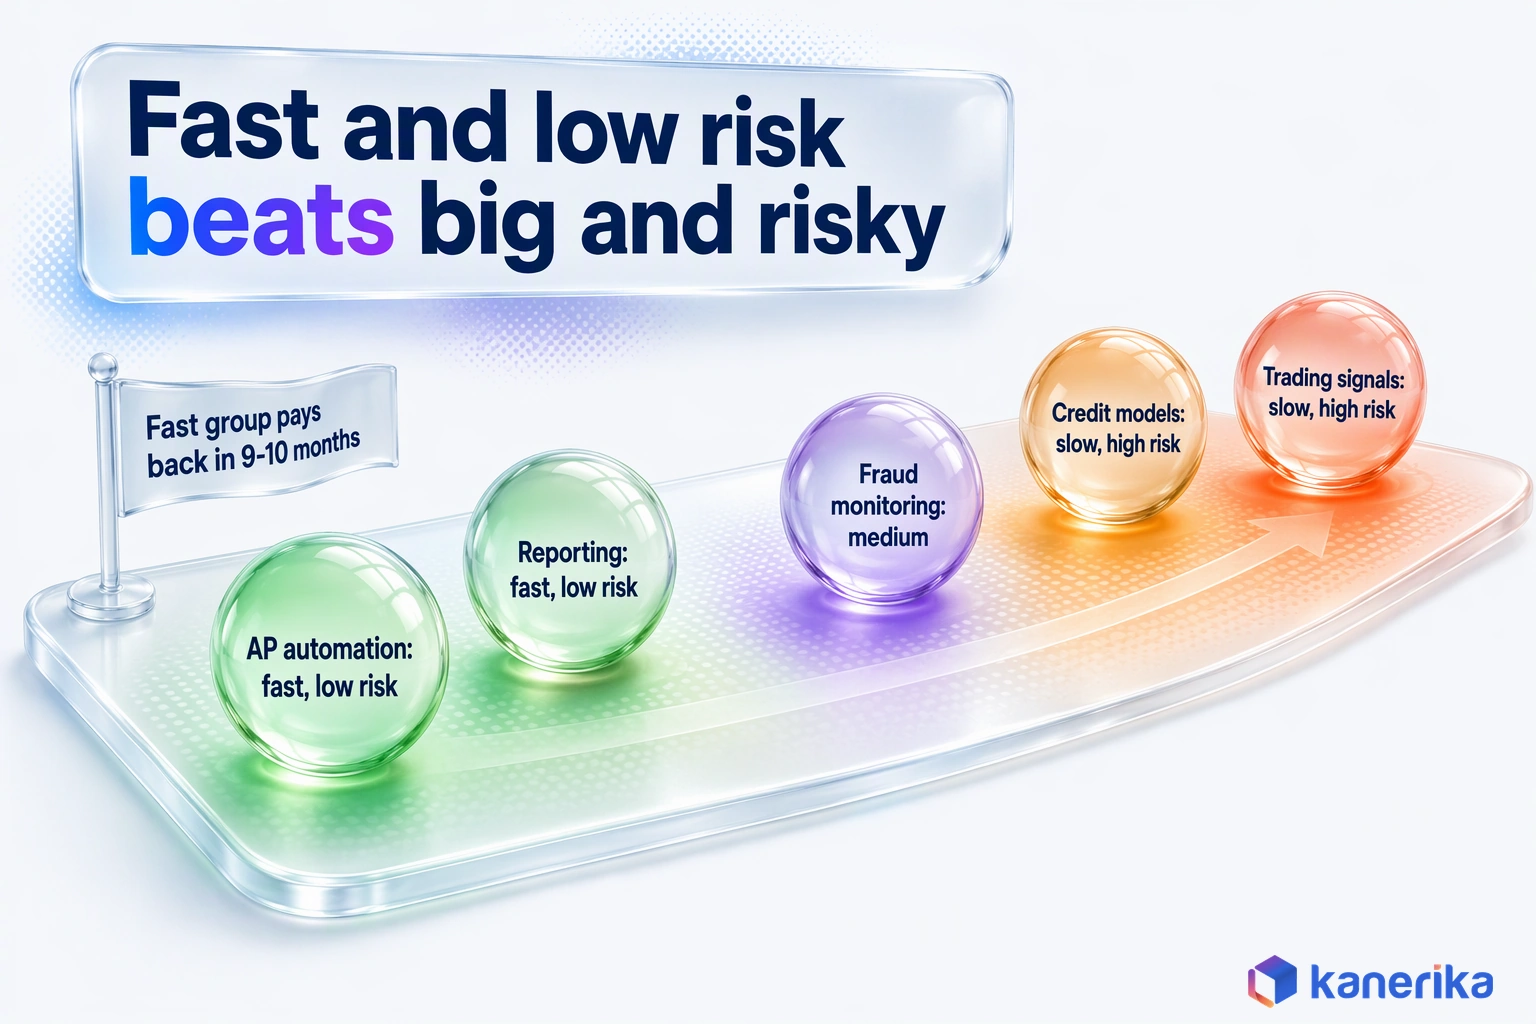
Reading the Time-to-Value and Risk Columns
Risk tier is a separate axis from speed. It reflects how much harm a wrong output can do before a person checks it. A misrouted invoice gets caught in the approval queue, while a biased credit decision reaches a consumer and a regulator.
| Use case | Sector | AI type | Data it needs | Time to value | Risk tier |
|---|---|---|---|---|---|
| 1. Fraud and transaction monitoring | Both | Predictive | Transactions, device and account history | Medium | Medium |
| 2. AML and KYC investigation | Financial services | Predictive and generative | Alerts, customer records, case notes | Medium | High |
| 3. Credit scoring and underwriting | Financial services | Predictive | Application, bureau and repayment history | Slow | High |
| 4. Cash-flow and treasury forecasting | Both | Predictive | Balances, AR and AP schedules, payment history | Slow | Medium |
| 5. AP and invoice processing | Finance function | Generative and predictive | Invoices, POs, receipts, vendor master | Fast | Low |
| 6. Close and reconciliation | Finance function | Predictive and agentic | General ledger, subledgers, bank statements | Medium | Low |
| 7. FP&A commentary and reporting | Finance function | Generative | Governed actuals, budget, driver notes | Fast | Low |
| 8. Document intelligence | Both | Generative | Statements, agreements, loan files | Fast | Medium |
| 9. Grounded assistants | Both | Generative with retrieval | Approved policy and product documents | Medium | Medium |
| 10. Portfolio analytics and robo-advisory | Financial services | Predictive and agentic | Market, position and client data | Slow | High |
Treat the time-to-value labels as planning guides rather than promises. “Fast” marks uses inside Gartner’s 9-to-10-month group, whereas “slow” marks forecasting and data-heavy work that the same research found takes longer. “Medium” marks uses the survey did not rank, which we place between the two because of the data work they need.
The 10 AI Use Cases in Finance and What Each Needs to Work
Each use case below covers what it does, a concrete example, the results it changes and the data it needs before it can run. Read the data needs as a readiness test for your own systems, because that is where most pilots stall.
Checklist
Enterprise AI Checklist
Use this checklist to assess AI readiness, data foundations, governance and business value before you fund a finance AI use case.
Get the Checklist →1. Fraud Detection and Real-Time Transaction Monitoring
Fraud detection is the oldest AI job in finance, and it still returns the most where losses are high. A model scores each payment while it happens, comparing it with the account’s normal pattern, the device and the counterparty. Payments above a threshold go to an analyst queue instead of clearing.
Picture a large card payment from a new device, at an odd hour, on an account that usually makes small purchases. A rules engine would need a separate check for each signal; an anomaly model weighs them together and ranks the payment by risk. The analyst therefore sees it first.
One documented example comes from a US mid-sized insurer rated A+ by AM Best. Isolation Forest and autoencoder models flagged unusual activity in its data. As a result, the insurer recorded a 33% decrease in financial losses and a 25% reduction in overall risk exposure. Our guide to AI in fraud detection also covers the model choices in depth.
A working program shows up in three ways:
- Real-time transaction monitoring detects suspicious activities faster than manual systems
- Ranked alert queues send analyst time to the riskiest cases first
- Fewer false positives mean fewer good customers blocked at checkout
What it needs: labeled fraud history, transaction and device data in near real time and a documented threshold that someone owns. Banks also run predictive analytics in banking models for credit and churn on the same data foundation.
2. AML and KYC Investigation Support
Anti-money laundering teams face a flood of alerts, and much of an investigator’s day goes to gathering evidence rather than judging it. AI helps at two points. First, a triage model ranks alerts by how likely they are to need a case. Then a generative model assembles the evidence and drafts the case narrative.
Take an alert on a business account with a sudden burst of cross-border transfers. It arrives with the customer’s KYC file, past alerts and a transaction timeline already attached. The investigator then reads the draft, checks the sources and decides. A person still files the suspicious activity report (SAR) through FinCEN’s BSA E-Filing System, and the AI never does.
Teams judge the program by time per alert, the share of alerts closed without a case and the quality of SAR narratives. None of that works without clean customer and transaction records. It also needs a case system the model can write drafts into and an audit log of every AI-drafted line.
3. Credit Risk Scoring and Underwriting
A credit model predicts the chance that a borrower repays, so it decides who gets a loan and at what price. Machine learning can use more signals than a classic scorecard, such as cash-flow patterns from bank account data. That extra power, however, brings an extra duty to explain each decision.
Under Regulation B (12 CFR 1002.9(a)), a lender taking adverse action must give specific reasons or tell the applicant of the right to request them. A model that cannot say why it declined someone is not usable for lending, however accurate it looks. Teams therefore pair the model with explanation methods and a reason-code map that compliance signs off.
The gains show up in approval speed, loss rates by segment and manual review volume. The entry price is high, though: years of repayment history, a validation team independent of the builders and a model risk process. Our post on underwriting automation also covers the decision workflow around the model.
4. Cash-Flow and Treasury Forecasting
A cash forecast tells treasury how much money will be where, in which currency and when. AI forecasts each entity and currency separately, learns weekly and seasonal patterns and updates when actuals land. The horizon changes the inputs, since a 13-week liquidity view needs different drivers than a next-day funding view.
Take a 13-week forecast that shows the cash balance dipping below a loan covenant’s minimum in week 9. Treasury then has about two months to draw on a credit line or delay a large payment, rather than finding the breach at quarter end. Companies outside banking can also start the same way, using their receivable and payable schedules.
What it moves: forecast error by horizon, idle cash and short-term borrowing. What it needs: bank balances, AR and AP schedules, payment history and a named owner who reviews each forecast before money moves. Kanerika’s financial forecasting AI agent is one packaged route.
Case Study
20% Productivity Lift for Bank Treasury with AI Forecasting
A leading banking institution replaced spreadsheet cash forecasts with a predictive model inside its Daily Funding Portal, with 20% higher workforce productivity and 35% fewer processing delays.
Read the Case Study →5. Accounts Payable and Invoice Processing
Accounts payable is where many finance teams see AI pay back first. That is because the work is high volume, rule bound and full of documents. A model extracts the vendor, amount, dates and line items from each invoice, then matches them to the purchase order and the goods receipt.
When the three documents agree, the invoice moves straight to payment approval. When they differ, by a price variance or a missing receipt, the system routes the exception to the right person with the mismatch marked. Clerks therefore stop keying data and start clearing exceptions.
What it moves: cost per invoice, cycle time, touchless rate and early-payment discounts captured. What it needs: a clean vendor master, purchase orders in the ERP and approval limits that already work. Our guide to accounts payable automation covers the full workflow and its controls.
6. Financial Close and Reconciliation
The month-end close is a matching problem at scale. Bank lines, subledgers and the general ledger all have to agree, but the gaps eat most of the time. AI suggests matches for items that differ in date, amount or description. It then ranks the leftover exceptions by size and age.
On the receivables side, the same method matches incoming payments to open invoices. It works even when a customer pays three invoices with one transfer and no reference. An accountant approves each suggested match, so the model learns from those approvals.
Success looks like fewer days to close, a higher auto-match rate and smaller unreconciled balances at period end. Getting there takes consistent account mapping, reliable statement feeds and reviewer sign-off recorded in the close tool.
7. FP&A Variance Commentary and Management Reporting
Every month, analysts write the same kind of sentence: revenue came in under plan because volumes slipped in one region. Generative AI is especially good at drafting that commentary. It reads the variance table and the driver notes, then writes a first pass for the analyst to edit.
The rule is simple: the model writes words, while the system computes numbers. Large language models can make arithmetic errors, so every figure in the draft must come from the governed reporting layer. Banks also apply the same rule to client and board reporting, as our post on generative AI in banking explains.
Measure it by the hours spent on commentary and the time from close to board pack. Before the pilot starts, put three things in place: a governed semantic model, approved metric definitions and a reviewer who owns the final text.
AI Assessment
Is Your Finance Data Ready for AI?
Score your data, governance and skills in a few minutes and see which finance use case your organization can support today.
Start Your AI Assessment →8. Financial Document Intelligence
Finance runs on documents: bank statements, loan agreements, leases and tax forms. Document intelligence reads them, extracts the fields that matter and flags clauses or values that need a closer look. In effect, it turns a stack of PDFs into rows a system can use.
Volume is where the value shows. In one bank’s statement project, automation produced about 70,000 PDF statements in one day. The bank also saw an 80% reduction in end-to-end processing time and no manual intervention. The same pipeline thinking applies in reverse when the job is reading inbound documents.
Three numbers tell you whether it works: documents processed per hour, extraction accuracy on a sampled check and rework. Each layout needs sample documents and clear field definitions, and low-confidence fields still go to a person.
9. Customer and Advisor Assistants Grounded in Approved Data
Assistants answer questions for customers, relationship managers and advisors. The safe version uses retrieval-augmented generation (RAG). It searches approved policy, product and pricing documents, then answers only from what it found, with a citation the user can open.
Can AI replace financial advisors? Not for regulated advice. Even so, an assistant can prepare a client meeting, summarize a portfolio and answer product questions in seconds. The advisor still owns suitability and the recommendation, and the assistant should hand off whenever a question turns into advice.
What it moves: call handling time, first-contact resolution and advisor prep time. What it needs: a curated document library with named owners, access controls by role and a log of every answer.
Kanerika Service
AI for Banking and Financial Services
Kanerika builds fraud, forecasting, document and assistant use cases for banks and lenders, with validation, approval gates and monitoring designed in from the start.
Explore AI in Banking10. Portfolio Analytics, Trading Signals and Robo-Advisory
This use case belongs to financial services firms only. Models scan market, position and alternative data for signals, rebalance portfolios to a target and power robo-advisory platforms for retail clients.
Picture a robo-advisor that rebalances a client account whenever an asset class drifts, say, 5 points past its target band. A person approves any trade above a set limit, so speed and scale stay inside agreed bounds.
That rule-following is also the weak point, and it puts this use case in the highest model-risk tier on this list. Markets shift, so a model trained in one regime can fail in the next without warning. Firms that run these models invest in independent validation, limits on automated actions and constant performance monitoring before they scale.
Judge it on risk-adjusted return, tracking error and cost per managed account. It also demands long and clean market history, a validation function and a kill switch that a person controls.
Predictive, Generative and Agentic AI: Which One Fits Which Finance Task
Three kinds of AI show up across these use cases, and each suits a different kind of task. Predictive AI estimates a number or a probability, such as a fraud score, a default risk or tomorrow’s cash balance. Generative AI produces text and pulls meaning out of documents. Agentic AI chains steps together and takes actions in other systems, such as opening a case or posting a match.
The common mistake is asking one kind to do another’s job. A generative model asked to forecast cash will produce fluent but unreliable numbers, while a predictive model cannot draft a SAR narrative. Our comparison of generative AI vs predictive AI goes deeper on the trade-offs.
Matching the Task to the Approach
The table pairs common finance tasks with the approach that fits them best. It also names the human checkpoint, since every row still needs a person somewhere in the loop.
Talk to Kanerika
Planning Your First Finance AI Pilot?
Bring one process, such as AP, the close or cash forecasting. Kanerika will help you baseline it, score it against the alternatives and set pass and stop criteria.
Schedule a Demo →| Task | Best fit | Why | Human checkpoint |
|---|---|---|---|
| Score a payment for fraud | Predictive | Needs a calibrated probability in milliseconds | Analyst reviews flagged payments |
| Draft a SAR or variance narrative | Generative | Turns structured evidence into readable text | Investigator or analyst edits and approves |
| Extract invoice and statement fields | Generative | Reads varied layouts without fixed templates | Clerk checks low-confidence fields |
| Forecast cash by entity | Predictive | Learns from time series and business drivers | Treasurer approves before funding |
| Match, route and post exceptions | Agentic | Chains several steps across systems | Approver signs off before posting |
| Answer policy questions | Generative with retrieval | Grounds answers in approved documents | Hand-off to a person for advice |
Where AI Agents Fit
Agents get the most attention and need the most care. An agent that can post journal entries or release payments needs limits on what it may do alone, plus a person at each approval gate. Our guide to agentic AI in financial services also covers those guardrails in detail.
Most production systems combine two or three of these kinds. An AP workflow, for instance, uses generative extraction, a predictive duplicate check and an agent that routes exceptions. Once you name the kind of AI behind each step, the right controls follow from it.
How a Finance AI Use Case Runs in Production
A model on its own changes nothing, because the workflow around it does the work. Every finance use case that reaches production follows a similar path, from source data to an action inside the system people already use.
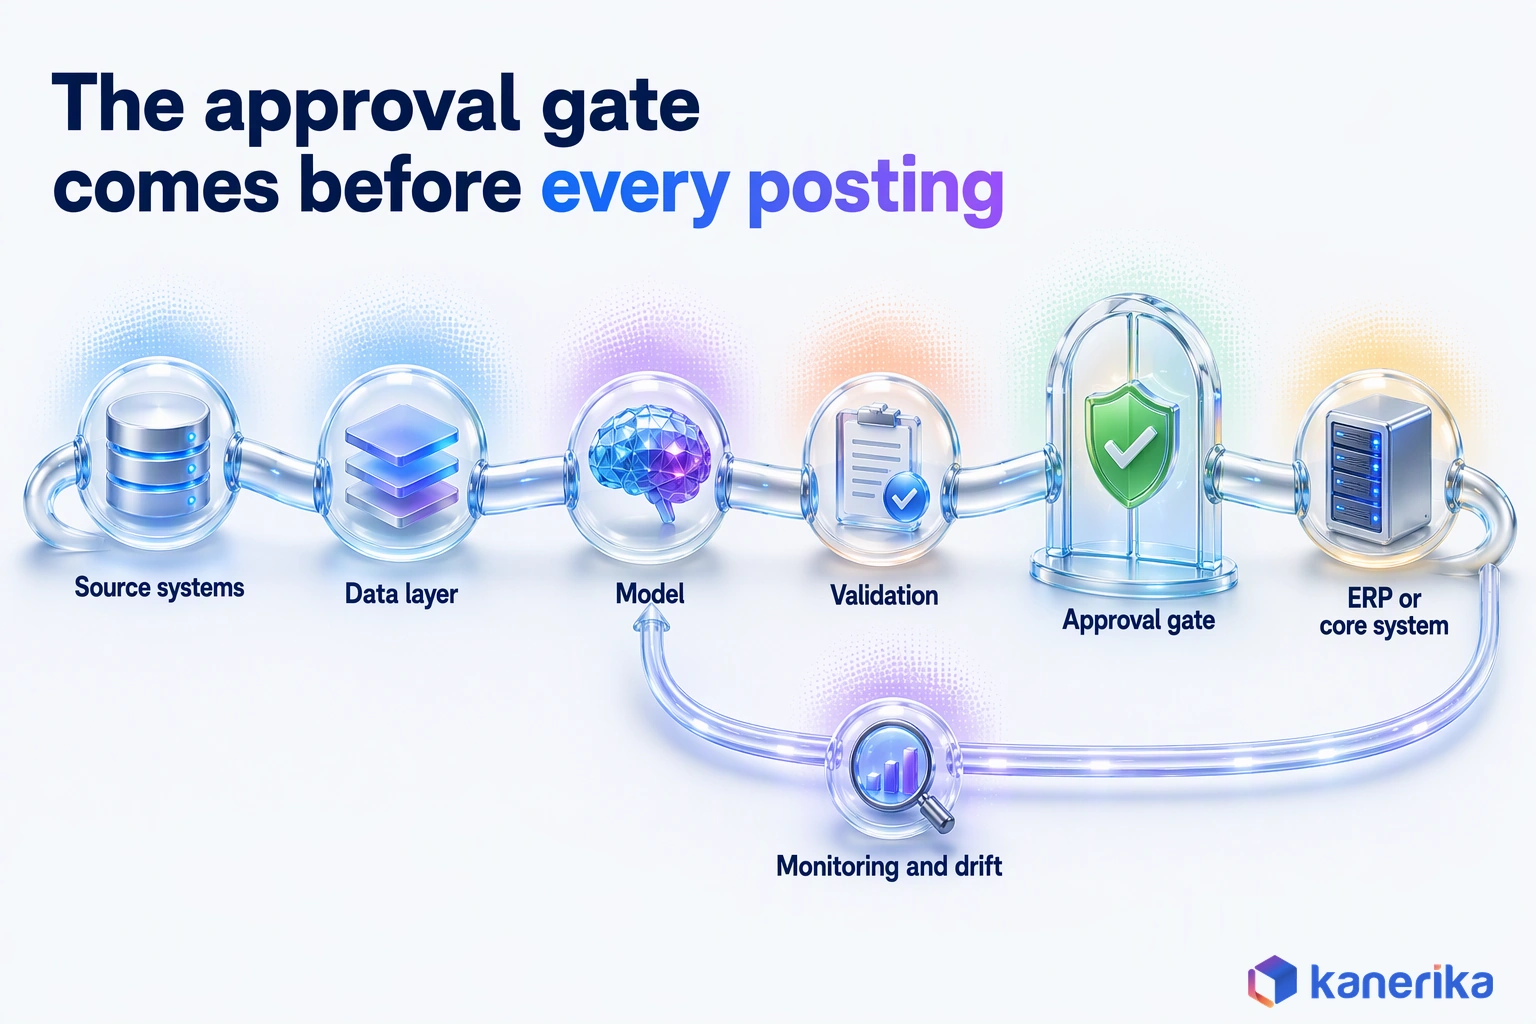
The path has seven stages. Source systems such as the ERP, core banking, bank feeds and document stores feed a governed data layer, where features and shared definitions live. The model then scores, forecasts or drafts, and a validation step checks its output against thresholds and business rules.
Next comes the approval gate, the stage teams skip most often. A person, or a rule that a person owns, approves the action before it posts in the ERP or core system. Our post on human-in-the-loop AI agents shows how to design that gate without slowing the flow.
Following One Invoice Through the Path
Follow one supplier invoice along that path. First, it lands in the document store, and then the data layer links it to the vendor master and the purchase order. After that, the model extracts the fields and checks for a duplicate. Validation flags a price variance above tolerance, so the invoice stops at the approval gate until a buyer accepts the new price. Only then does the ERP post it, and the buyer’s decision becomes a training example.
Monitoring and Audit Logs: An Example Policy for the Invoice Flow
The last stage, monitoring, closes the loop, and it is easiest to see on the same invoice flow. Suppose a large supplier changes its invoice layout, and buyers start correcting the extracted prices far more often. That rise in overrides is the drift signal, so it should open a review before wrong prices reach the ledger.
Teams that run this well write the rules down as a policy the workflow engine reads, not as a slide. The example below shows the shape of such a policy for AP. Its thresholds are placeholders for illustration, so set each one from your own pilot baseline.
# Example monitoring and approval policy for an AP invoice workflow
# Thresholds are placeholders: set each one from your pilot baseline
use_case: ap_invoice_processing
model:
  name: invoice-extraction
  stamp_on_every_output: [model_version, input_pointer]
validation:
  three_way_match: [invoice, purchase_order, goods_receipt]
  price_variance_tolerance_pct: 2      # above this, stop at the gate
  duplicate_key: [vendor_id, invoice_number, amount]
approval_gate:
  route_to: buyer_of_record
  auto_post_only_if: [matched, within_tolerance, high_confidence]
  escalate_after_hours: 48
monitoring:
  owner: ap_process_owner
  open_review_when:
    weekly_override_rate_pct_above: 10
    low_confidence_field_share_pct_above: 15
    new_vendor_layout_detected: true
audit_log:
  fields: [invoice_id, model_version, input_pointer, output,
           approver, decision, timestamp]
Every field in that audit log answers a question an examiner tends to ask. Which model version produced the output, from what input, and who approved it? With that trail, an auditor can trace any posted entry back to the decision that produced it. Over time, the reviewers’ corrections also become labeled data for the next retraining.
The data layer carries more weight than it seems to. The vendor master and purchase orders that the invoice flow cleaned up are the same records a duplicate-payment check or a cash forecast needs next. That reuse is why platform choices such as Microsoft Fabric or a lakehouse sit behind most finance AI programs.
Two numbers tell you whether the workflow is healthy: how often people override the output, and how long items wait at the approval gate. Rising overrides mean the model has drifted or the threshold is wrong. Long waits, on the other hand, mean the gate needs more reviewers or clearer rules.
Decision Framework: Which AI Use Case in Finance to Fund First
The best first project is the one that proves value fastest at the lowest risk, rather than the most impressive one. A short, scored process keeps that choice honest and gives the steering committee a reason it can defend.
- Baseline the process. Measure today’s cycle time, cost per item, error rate and volume before any model exists.
- Score each candidate on five criteria. Rate business value, data readiness, decision risk, integration effort and time to value from 1 to 5.
- Pick the top scorer. Change the order only when a regulator or an open loss forces it.
- Set pass and stop criteria. Write down a target, such as a touchless rate or a false-positive ceiling, and a date to decide.
Weight the criteria to fit your situation. A bank under regulatory pressure might weight decision risk higher, while a fast-growing company might weight time to value. Agree on the weights before anyone scores, so the numbers cannot be bent toward a favorite project.
When the scores land close together, scenario rules make a useful tiebreaker. Each row below gives a pick for a common situation and why.
| Scenario | Pick first | Why |
|---|---|---|
| High invoice volume and manual keying | AP automation | In Gartner’s fastest payback group, with low decision risk |
| Rising fraud loss | Real-time transaction monitoring | Loss avoided is easy to measure against the baseline |
| Volatile liquidity or many entities | Cash forecasting | Slower payback, but the idle cash and borrowing it cuts are large and measurable |
| Slow month-end close | Reconciliation matching | High volume of repeatable matches at low risk |
| Heavy reporting workload | FP&A commentary | Fast to pilot on numbers that are already governed |
| Regulated lending decisions | Credit model, only after model risk management is in place | High value, but the heaviest validation and fair lending burden |
Worked Example: AP Automation vs a Credit Model as the First Project
Take a mid-sized lender that also runs a large internal AP operation. It has budget for one AI project and two candidates. The scores below are illustrative, on a 1-to-5 scale where 5 is always best, so a 5 on risk means the lowest risk.
| Criterion (weight) | AP automation | Credit model |
|---|---|---|
| Business value (25%) | 4 | 5 |
| Data readiness (20%) | 5 | 3 |
| Decision risk, 5 = lowest (20%) | 5 | 2 |
| Integration effort, 5 = easiest (15%) | 4 | 3 |
| Time to value (20%) | 5 | 2 |
| Weighted score out of 100 | 92 | 62 |
The math is simple. Multiply each score by its weight, add the results and divide by 5. So AP scores 460 / 5 = 92, while the credit model scores 310 / 5 = 62. The credit model wins on value alone, but it loses on data readiness, risk and time.
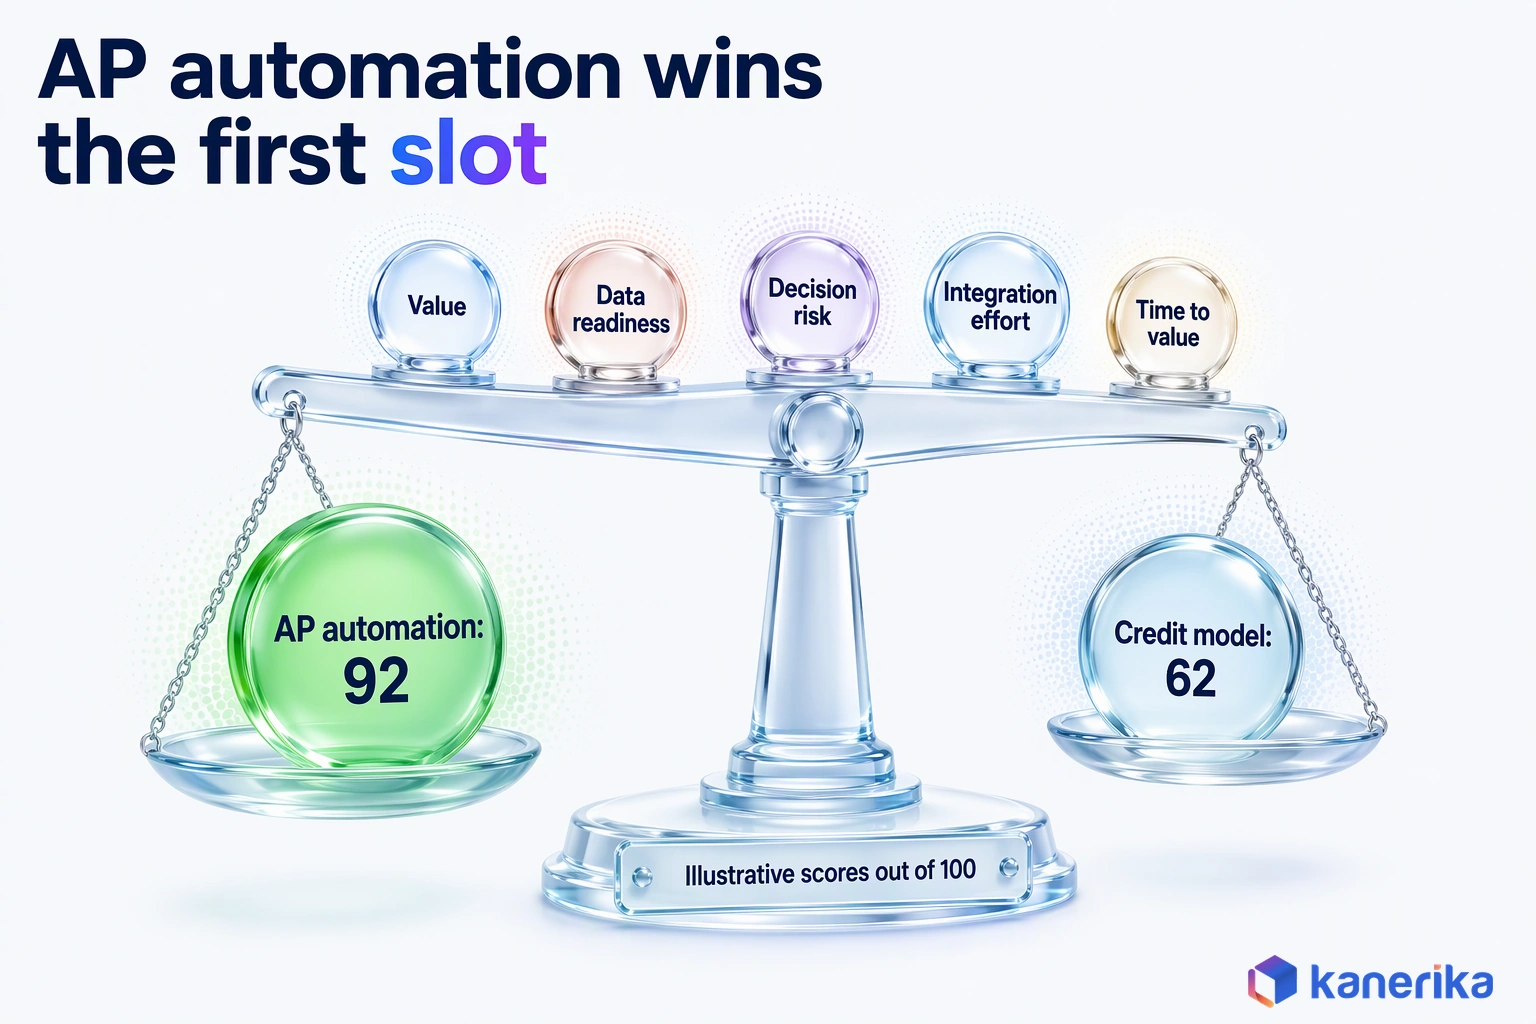
So the lender funds AP first, proves the workflow and the data layer, and starts the credit model once validation capacity exists. Model risk guidance such as SR 26-2 would call for independent validation of that credit model anyway. The second project then reuses the governance built for the first.
What It Costs and How Long It Takes
Cost depends far more on data and integration than on the model itself. Gartner’s finding gives the outer frame. The fast group of finance AI uses generally returned value within 9 to 10 months, while forecasting and data management took longer.
For planning, we use the phase ranges below. They are planning assumptions drawn from typical project shapes rather than benchmarks, so your numbers will move with data quality and the number of systems involved.
- Discovery and baseline: 2 to 4 weeks.
- Bounded pilot on one process: 8 to 12 weeks.
- Integration with approval gates: 6 to 12 weeks.
- Monitoring and expansion: ongoing, with a review each quarter.
Budget for people and run costs as well as licenses. Data engineering, validation, change management and model monitoring often outweigh the software line. Our guide to enterprise AI spending shows how to budget a portfolio of use cases rather than one project at a time.
Build, Buy or Combine
Most finance teams end up combining the two. They buy when the process is standard and build when their own data or rules are the edge.
| Criterion | Buy SaaS | Build on your platform | Combine |
|---|---|---|---|
| Speed to pilot | Fastest | Slowest | Medium |
| Fit to your rules | Vendor defaults | Exact | Exact where it matters |
| Control of data | Leaves your platform | Stays in your platform | Sensitive data stays in |
| Best for | AP, expenses, standard close | Credit, fraud tuned to your book, forecasting | Most enterprise programs |
Compare vendors on how they handle your exceptions rather than on demo accuracy. Our roundup of AI finance tools reviews the main products by use case, so you can shortlist without starting from scratch.
Risks, Governance and the Rules That Apply
Finance AI fails in predictable ways, which means the controls can be planned before launch. Each risk below has a control and an owner, because a control with no owner is a policy nobody runs.
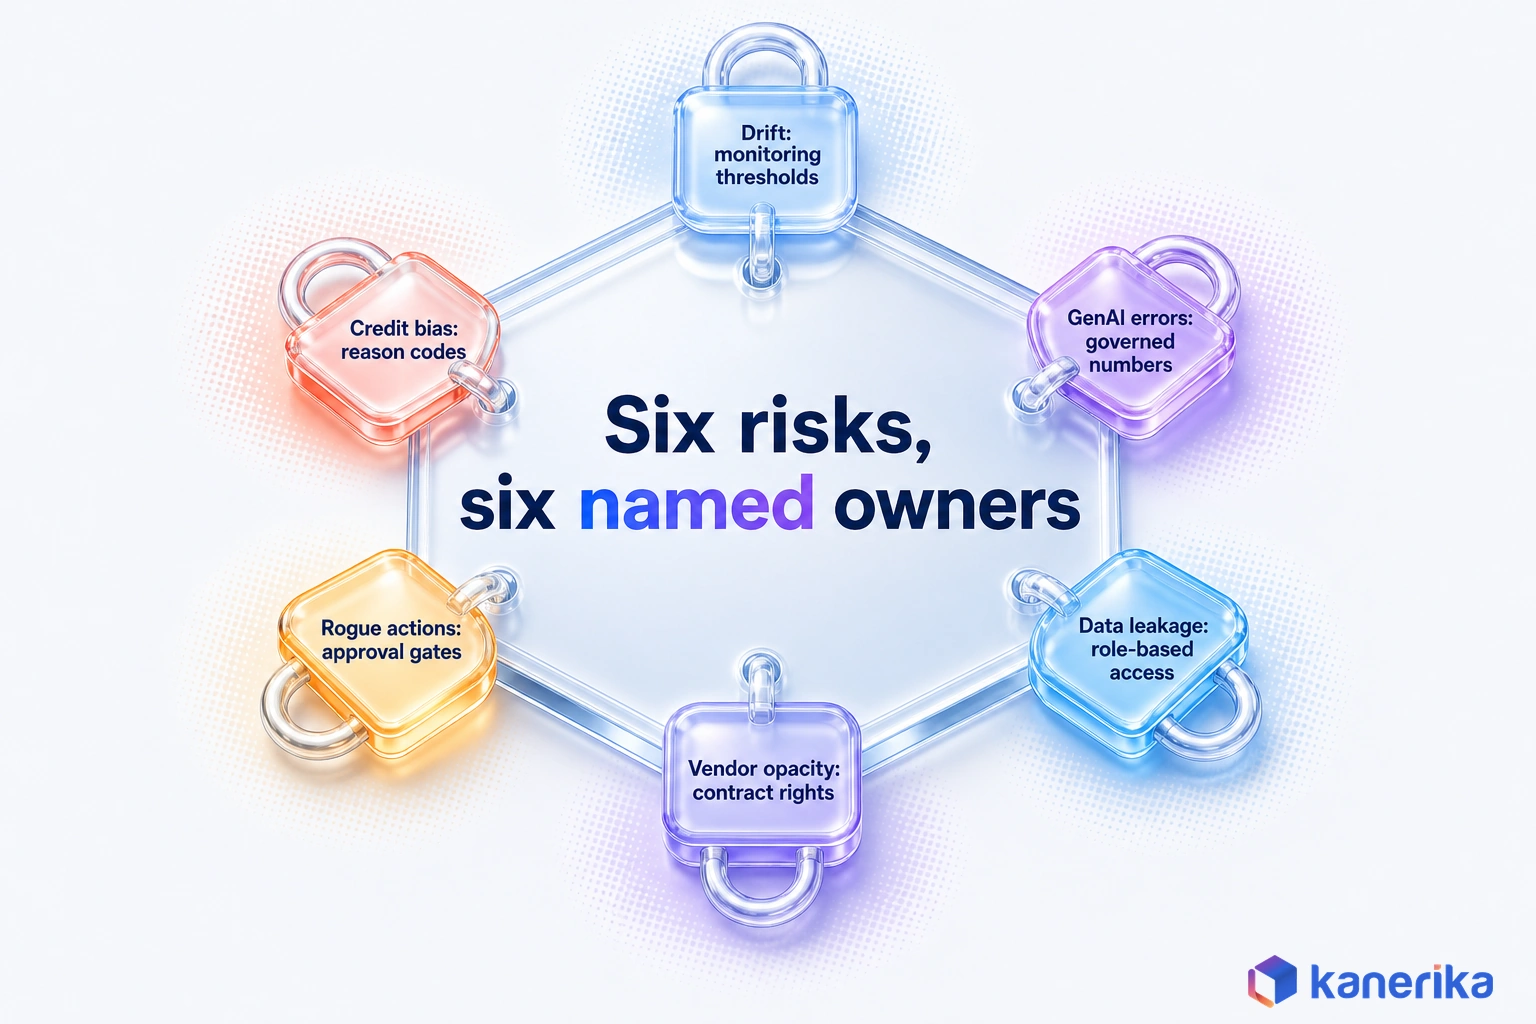
| Risk | Control | Owner |
|---|---|---|
| Biased or unexplainable credit decisions | Fair lending tests and reason codes | Model risk and compliance |
| Model drift | Monitoring thresholds and retraining triggers | Model owner |
| Generative AI errors in numbers or text | Numbers from governed data only, plus human review | Report owner |
| Unapproved automated actions | Approval gates and action limits | Process owner |
| Data leakage | Role-based access and no sensitive data in public tools | CISO and data owner |
| Vendor model opacity | Documentation and validation rights in the contract | Procurement and model risk |
The Rules That Apply in 2026
The risk table covers the internal side. Data leakage is the row teams underrate most, and our post on data security in AI covers the access controls that close it. Our guide to AI compliance also maps the wider set of obligations across sectors.
From the outside, four rule sets frame these controls for US firms and for anyone serving EU customers.
- SR 26-2. The Federal Reserve, OCC and FDIC issued revised model risk guidance on April 17, 2026. SR 26-2 supersedes SR 11-7 and is most relevant to banking organizations with over $30 billion in total assets. It also replaces SR 21-8, the statement on BSA/AML models, which matters for use case 2.
- Regulation B. Section 1002.9(a) requires a lender taking adverse action to give specific reasons, or to tell the applicant of the right to request them. That duty also applies to AI credit models.
- NIST AI RMF. NIST released the AI Risk Management Framework on January 26, 2023, and its Generative AI Profile, NIST AI 600-1, on July 26, 2024. Our AI governance framework guide shows how it lines up with the EU AI Act.
- EU AI Act. Per the European Commission, the Act entered into force on August 1, 2024 and lists credit scoring as a high-risk use. Transparency rules have applied since August 2, 2026. The AI Omnibus, in force since July 27, 2026, moved the Annex III high-risk rules, credit scoring included, to December 2, 2027.
None of these rules bans a use case outright. Instead, they ask for evidence that a model works, that its decisions can be explained and that people stay accountable. Our posts on AI governance in financial services and AI model risk management cover the frameworks in more depth.
Common Mistakes and the Fix
The same five errors show up again and again when finance AI pilots stall. Each one has a cheap fix if you catch it before launch.
- No baseline. Without today’s cycle time and error rate, nobody can prove the pilot worked. Measure for two to four weeks before building.
- Generative AI doing arithmetic. Compute every number in the governed layer and let the model write only the words.
- Skipping the approval gate. Put a named approver before any posting, payment or customer decision.
- A model without monitoring. Set drift thresholds and a named owner on day one, not after the first incident.
- Buying a tool before fixing data. Clean the vendor master, account mapping or customer records first.
Each of these has sunk pilots that looked strong in a demo. The fix costs little before launch and a great deal after it.
How Kanerika Delivers a Finance AI Use Case in Stages
Kanerika runs finance AI work in four stages, so that each stage earns the budget for the next one. The method comes from client work in banking and corporate finance, delivered through our AI services and our AI in banking practice.
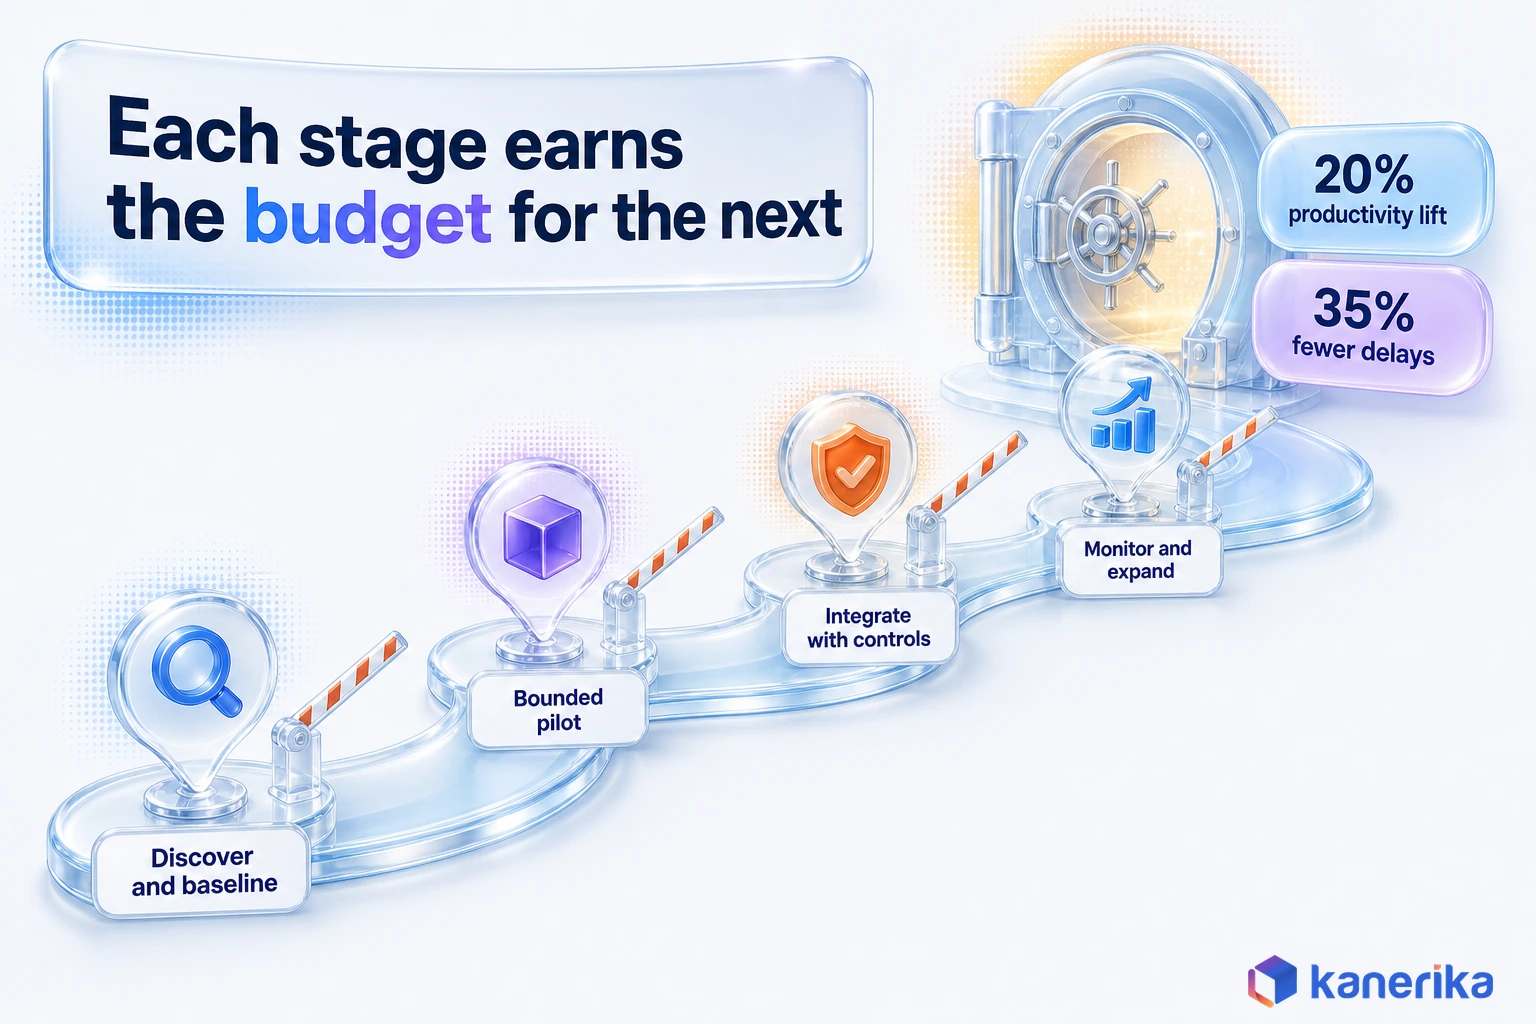
- Discover and baseline. Map the process and record current cycle time and error rate.
- Run a bounded pilot. Test one process with pass and stop criteria agreed up front.
- Integrate with human controls. Put the output into the system people already use, behind an approval gate.
- Monitor and expand. Watch drift and overrides, then move to the next use case on the same data layer.
A stage ends only when its exit test passes. For a pilot, that test is the pass criterion agreed in the first stage. For instance, it might be a touchless rate for invoices or an error band for a cash forecast. If the pilot misses it by the agreed date, the work stops or changes scope, so the budget for the next candidate stays protected. Our guide to moving an AI pilot to production covers what tends to break at that handoff.
Case Study: Treasury Forecasting for a Leading Bank
Treasury forecasting shows the stages in action at a leading bank whose funding team built daily cash forecasts by hand. The inputs sat in spreadsheets drawn from fragmented systems, so every forecast started with copying and checking data.
Kanerika built a predictive model for daily inflows and outflows and connected the sources into one input layer. Kanerika then embedded the forecasts in the bank’s Daily Funding Portal and automated the identification of surplus and retention amounts. Analysts could therefore review results instead of building them.
Afterward, the bank recorded a 20% increase in workforce productivity, 35% fewer processing delays and 40% more use of AI tools and data. Our treasury forecasting case study has the full detail, while finance teams outside banking can see our finance function work.
Two design choices matter for any team copying this pattern. The forecast appeared inside a tool the funding team already used, so acting on it took no extra step. The single input layer built for the model is also the foundation the fourth stage reuses for the next use case.
Kanerika Service
AI Services for Finance Teams
Kanerika takes finance AI use cases from baseline to monitored production, from AP and close automation to forecasting and fraud models with human approval built in.
Explore AI ServicesWhich AI Use Case in Finance Should You Start With?
Start with AP and invoice processing (use case 5) for a fast, defensible win. Document intelligence (8) and FP&A reporting (7) are equally fast alternatives, since Gartner puts data extraction and report creation in the 9-to-10-month payback group. Start with real-time transaction monitoring if fraud loss is the bigger number, but start with cash forecasting when liquidity is what keeps treasury busy.
Hold credit models and trading signals until validation, monitoring and approval gates exist, then reuse the data layer the first project built. Whichever you choose, baseline it first and write the stop criteria down. Among all the AI use cases in finance, the right first one is the one whose result you can prove.
Frequently Asked Questions
How is AI used in finance?
AI in finance detects fraud, triages AML alerts, scores credit, forecasts cash, processes invoices, speeds up the close, drafts reporting commentary, reads financial documents, powers grounded assistants and supports portfolio analytics. Banks and insurers use it on customer products, while corporate finance teams use it on back-office work. Most programs start with document-heavy, repeatable processes that pay back fastest.
What is the future role of AI in finance?
AI will take on more of the repeatable work in finance, such as matching, extraction, first-draft commentary and alert triage, while people keep judgment and approval. Agentic systems will chain more steps together, but regulators expect explainable decisions and human accountability. So AI is part of the future of finance, working alongside finance professionals rather than replacing them.
Can AI make credit decisions without human review?
Lenders can automate parts of credit decisions, but they must still explain them. Under Regulation B, a lender taking adverse action must give the applicant a statement of specific reasons, so an AI credit model needs reason codes that compliance has approved. Most lenders also keep human review for edge cases and validate and monitor the model independently.
How long does it take to implement AI in finance?
Gartner research found that data extraction, AP and AR automation and report creation generally return value within 9 to 10 months, while forecasting and data management take longer. As planning assumptions, a baseline takes 2 to 4 weeks, a bounded pilot 8 to 12 weeks and integration with approval gates 6 to 12 weeks, depending on data quality.
How do you measure ROI from AI in finance?
Measure the process before the pilot, then compare the same measures afterward. Useful measures include cost per invoice, cycle time, touchless rate, days to close, forecast error, losses avoided and analyst hours saved. Subtract the full run cost, including data engineering, validation, monitoring and licenses. Set pass and stop criteria in advance so results are judged honestly.
What US regulations apply to AI in financial services?
Banks follow model risk guidance in SR 26-2, issued in April 2026, which replaced SR 11-7 and matters most for banking organizations with over $30 billion in assets. Lenders must give specific reasons for adverse action under Regulation B, Section 1002.9. The NIST AI Risk Management Framework and its Generative AI Profile give voluntary guidance on AI risk.
Should a company build or buy finance AI software?
Buy where the process is standard, such as AP, expenses or a typical close, because packaged tools reach a pilot fastest. Build on your own data platform where your data or rules give you an edge, such as fraud models tuned to your book or credit scoring. Most enterprises combine both, keeping sensitive data inside their own platform.
What are the risks of AI in finance?
The main risks are biased or unexplainable credit decisions, model drift as markets and fraud patterns change, generative AI errors in numbers or text, automated actions nobody approved, data leakage and opaque vendor models. Each needs a named control and owner, such as fair lending tests, monitoring thresholds, approval gates, role-based access and validation rights in vendor contracts.
How do banks use AI?
Banks use AI to monitor transactions for fraud in real time, rank AML alerts and draft case narratives, score credit applications, forecast daily liquidity and read statements and loan files. Customer and advisor assistants answer questions from approved documents. Larger banks run these models under model risk guidance such as SR 26-2, with independent validation and ongoing monitoring.
Can AI be used for financial planning?
Yes. AI supports financial planning by forecasting cash, revenue and costs from historical data and business drivers, updating forecasts as actuals arrive and drafting variance commentary for FP&A teams. The forecasts work best when a person reviews them before decisions are made. Generative AI should write the explanation, while governed systems compute every number in the plan.
Can AI replace financial advisors?
No, not for regulated advice. AI assistants can prepare client meetings, summarize portfolios, answer product questions from approved documents and run robo-advisory portfolios for simple goals. The advisor still owns suitability, the recommendation and the client relationship. A well-designed assistant hands the conversation to a person whenever a question turns into personal financial advice that needs professional judgment.
What skills are needed for AI in finance?
Teams need finance process knowledge, data engineering to build a governed data layer, data science for model building and validation, and model risk or compliance skills to test fairness and explainability. Change management matters as much, because people must trust and use the output. Many finance teams also add a product owner who connects each model to daily work.
What are the top AI tools for finance?
The right tool depends on the use case. AP and expense automation, close and reconciliation platforms, fraud monitoring systems and FP&A planning suites each have their own leaders, and many teams also build on cloud data platforms. Compare tools on how they handle your exceptions and data controls, and see our AI finance tools guide for products by use case.
Which AI use case in finance should a company implement first?
Most companies should start with accounts payable automation, data extraction or report creation, because Gartner research found those generally pay back within 9 to 10 months. Start with transaction monitoring if fraud loss is the larger cost, or cash forecasting if liquidity is volatile. Score candidates on value, data readiness, risk, integration effort and time to value.
What is the difference between predictive AI and generative AI in finance?
Predictive AI estimates a number or probability, such as a fraud score, a default risk or a cash forecast. Generative AI produces text and extracts meaning from documents, such as invoice fields or a variance narrative. In finance, predictive models compute and score, while generative models write and read, and neither should be trusted to do the other’s job.