TL;DR
Digital transformation in banking works in 2026 when a bank fixes its core approach and data foundation first, then adds channels and AI. If your core still posts transactions reliably, augment it with APIs and a modern data platform instead of replacing it. If the core blocks instant payments or new products, replace it in components, one product line at a time. Full replacement fits only when vendor support is ending or patching costs keep climbing. In every scenario, move clean, reconciled data first, because fraud monitoring, reporting and AI all depend on it. Then phase the work behind measurable gates and build the 2026 OCC model risk and third-party guidance into the plan.
Key Takeaways
- Digital transformation in banking is measured by outcomes such as cost-to-serve, time-to-decision and straight-through processing, not by the number of tools bought.
- Mobile apps are the top channel for 54% of US bank customers, according to ABA research from November 2025, so the back office has to keep pace with the app.
- A 2024 Kansas City Fed briefing names three core options: full replacement, component replacement, or augmenting the existing core.
- The data foundation sits between the core and every AI use case, which makes migration and reconciliation the first real milestone.
- OCC Bulletin 2026-13 replaced the 2011 model risk guidance, and OCC Bulletin 2026-46 proposed new third-party risk guidance in September 2026.
- A phased roadmap with stop-or-continue gates protects the budget better than one long multi-year program.
The Account That Opens in Four Minutes and Funds Tomorrow
Picture a small-business owner opening a checking account in her regional bank’s app during a lunch break. The identity check, a selfie and an e-signature take about four minutes. A cheerful confirmation screen appears.
Then she tries to fund the account with a transfer, and nothing happens. The new account will not exist in the core system until the overnight batch runs. Her first taste of the bank’s digital product is a wait, followed by a call to the branch.
The app, in fact, did its job here. But the core and the data behind it did not keep up.
That gap is the real subject of digital transformation in banking. It is also why this guide starts with the core and the data foundation, not with a list of technologies. The sections below follow that order. They cover what transformation means, which core path to pick, how to build the data foundation and how to phase it so each step pays back.
What Is Digital Transformation in Banking?
Digital transformation in banking means changing how a bank serves customers, decides and operates, so more work flows straight through without manual steps. It is judged by outcomes rather than by projects. Lower cost-to-serve, a faster time-to-decision on a loan and a higher share of straight-through processing make up the scorecard.
Take lending as an example. A bank that adds an online loan form has digitized a channel. Another bank pulls the applicant’s data, scores the risk, records the reasons and books the loan without rekeying. That second bank has changed the process behind it.
Technology lists miss this point. Cloud, APIs and AI matter only when they move one of those outcome measures. The order in which a bank adopts them also decides whether they do.
Digitization vs Digitalization vs Transformation
People often use the three terms as synonyms, yet they describe different depths of change. The table separates them using the same lending process.
| Term | What changes | Lending example |
|---|
| Digitization | Paper becomes data | Loan applications are scanned and stored as PDFs |
| Digitalization | A process uses digital tools | An online form feeds a loan officer’s work queue |
| Digital transformation | The operating model and its outcomes change | Data-driven decisions with specific reasons, booked straight to the core |
Banks usually run all three at once in different parts of the business. The useful question is which processes are still stuck at the first or second level, and what it costs to leave them there.
Case Study
70,000 Bank Statements a Day with 80% Faster Processing
A leading bank automated consolidated statements from three application sources, cutting processing time by 80% and removing manual intervention and errors.
Read the Case Study →
Why Digital Transformation in Banking Matters in 2026
The pressure comes from four directions at once. Customers have changed channels, old cores struggle with real-time products, AI needs better data, and supervisors have updated their expectations.
First, customers moved. An ABA survey with Morning Consult, published on November 18, 2025, asked US customers how they bank most. For 54% of them, the answer was a mobile app. Apps came out on top for the sixth year.
| Channel US customers use most | Share of customers |
|---|
| Mobile app | 54% |
| Laptop or PC online banking | 22% |
| Branch | 9% |
| ATM | 6% |
| Phone | 4% |
Second, the core itself has become the bottleneck. A 2024 Kansas City Fed briefing notes that many core systems cannot fully support open banking and instant payments. When the core cannot post in real time, every new channel inherits its batch schedule, exactly as the opening story showed.
Third, AI raises the stakes still further. Fraud models, credit decisions and staff assistants need clean, current and governed data. A bank whose customer records are split across separate product systems cannot feed those models reliably, however good the model is.
Finally, supervisors moved as well. The OCC, the Federal Reserve and the FDIC issued revised model risk guidance in April 2026, and the OCC proposed third-party risk guidance that September. Both shape how a bank adopts AI and cloud services, so they belong in the plan from the first phase.
The Five Areas Banks Transform
A bank’s transformation work falls into five areas. Each has its own technology and its own measure of success, and the areas depend on each other more than an org chart suggests.
Consider a mortgage. The channel can offer a better app, yet the core still has to price the loan. The data platform has to give a single view of the borrower. Automation has to check the documents, and one owning team has to run the process from application to closing.
| Area | What changes | Typical technology | KPI that shows progress |
|---|
| Customer channels | Self-service for opening, servicing and support | Mobile and web apps, digital onboarding | Digital account opening completion rate |
| Core and product systems | Real-time posting and faster product launches | Modern or componentized core, product engines, APIs | Time to launch a new product |
| Data platform | One governed source for customer and transaction data | Cloud lakehouse or warehouse, data catalog | Share of reports built from governed data |
| AI and automation | Decisions and back-office tasks without rekeying | Machine learning, RPA, document AI, assistants | Straight-through processing rate |
| Operating model | Teams own products and processes end to end | Product teams, agile delivery, cloud operations | Release frequency and change failure rate |
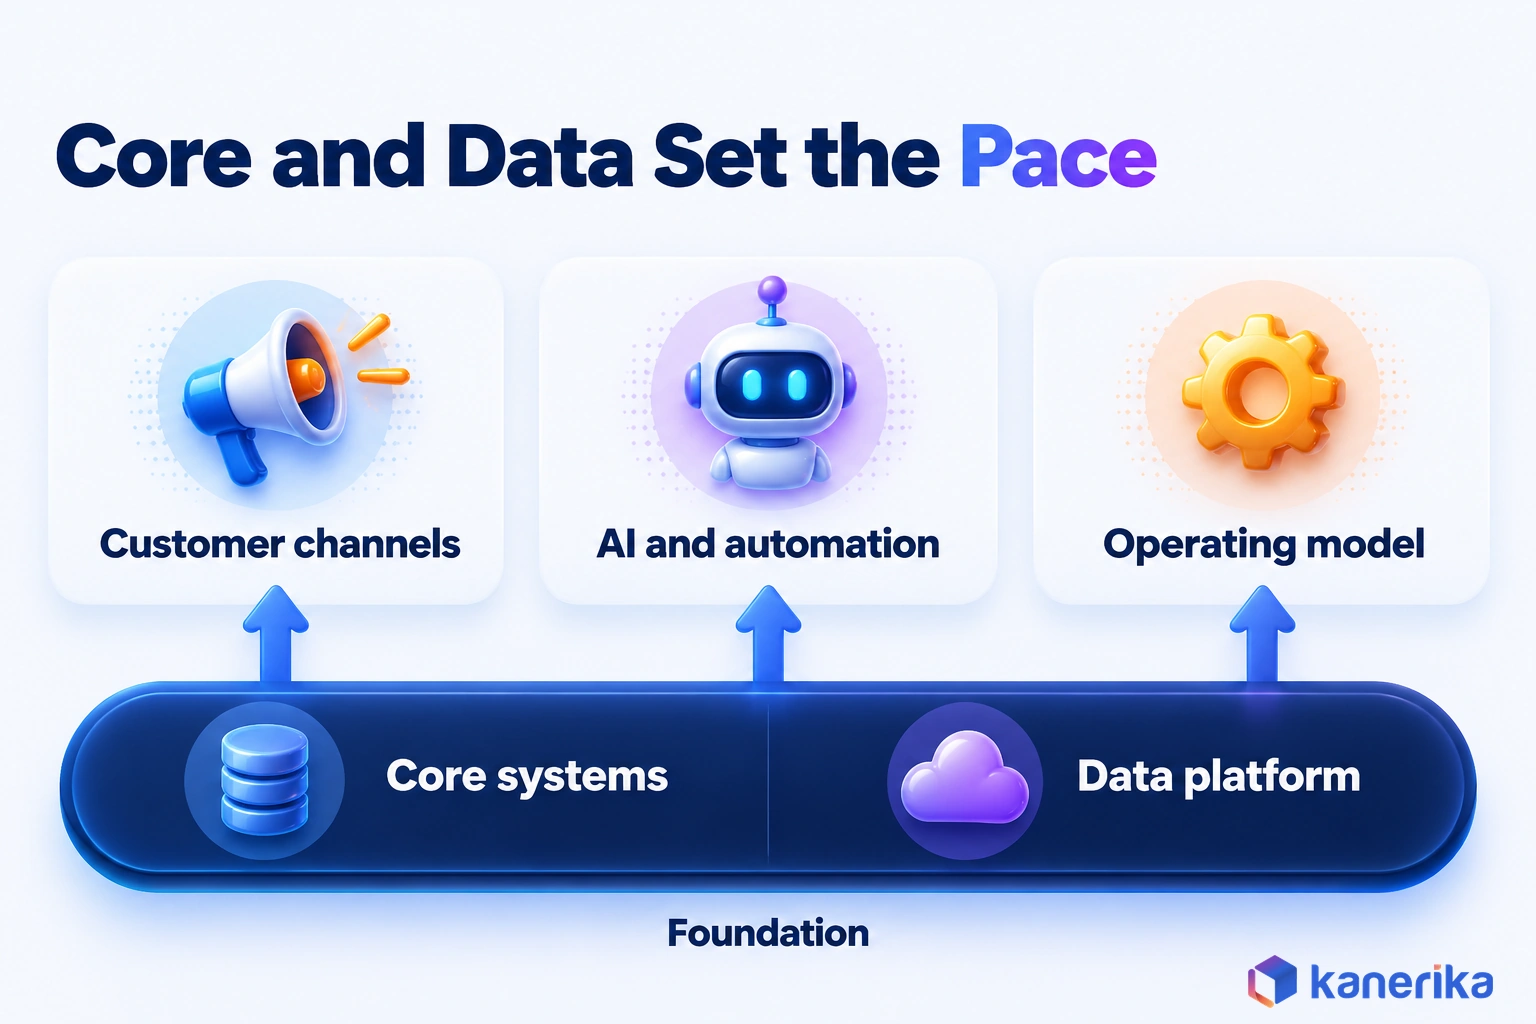
The core and the data platform deserve the most attention, because they set the pace for the other three. A slick channel on top of a batch core still makes customers wait. An AI model on top of unreconciled data still makes wrong calls, only faster. Blockchain and IoT show up on many trend lists, yet few banks need them to fix the problems in this table.
Kanerika Service
Banking Technology Consulting
Kanerika helps banks modernize core operations, risk and compliance with analytics, automation and data platform work tied to measurable outcomes.
Explore Banking Solutions
A Reference Architecture for a Digital Bank
A reference architecture is a map of the layers a bank needs and how they connect. It lets teams decide what to change first without redrawing everything at once.
Six layers cover most banks, and it helps to read them from the customer inward.
The channel layer holds the app, the website, branch tools and contact-center screens. It should carry no business rules of its own. Below it, an API and integration layer exposes accounts, payments and customer data as reusable services. A new channel then never needs its own point-to-point link to the core.
The core and product services layer keeps the ledger and the product rules. In a modernized bank this layer may be one new core, a set of components, or the old core wrapped in APIs. The next section covers that choice.
The data foundation is where many programs succeed or stall. It brings core, card and loan data into one governed platform with shared definitions and lineage, so every number has a known source. Reports, regulatory filings and AI models then read from this layer instead of from each product system.
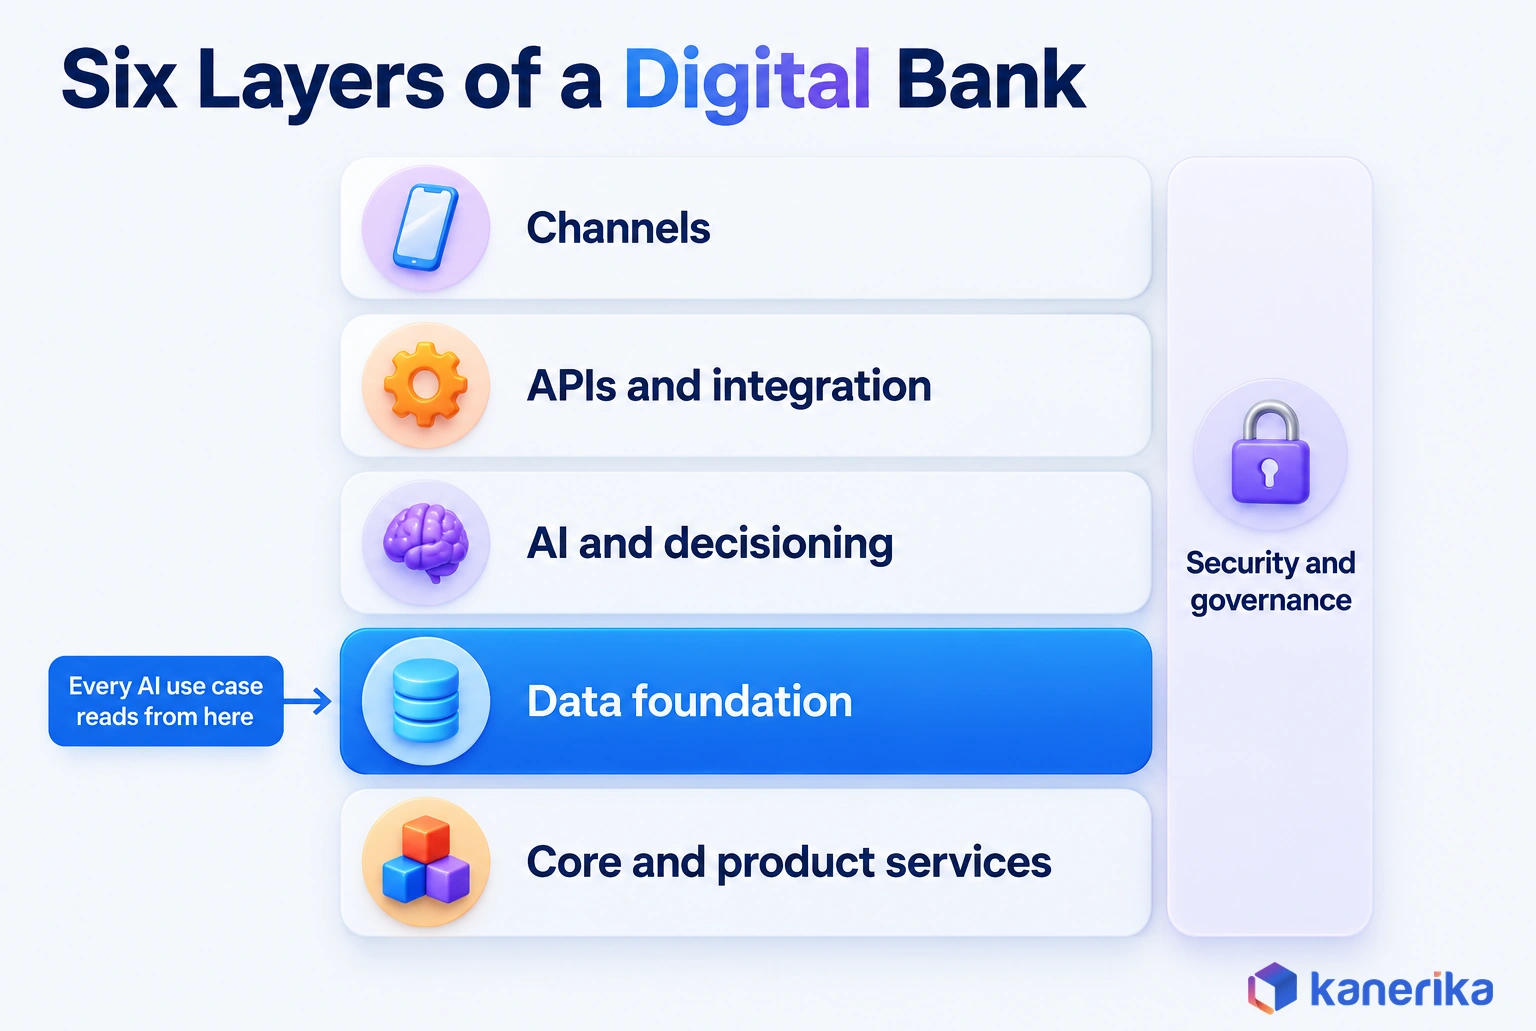
On top of the data sits AI and decisioning, which covers fraud scoring, credit models, document processing and assistants. Security and governance run through every layer instead of sitting at the end. That means identity and access control, encryption, a model inventory and vendor oversight, all designed in from the start.
The order of work follows the stack. A bank can refresh its channels quickly, but the gains only last when the data foundation underneath can be trusted.
Core Banking Modernization: Replace, Componentize, Augment or Build Alongside
The core banking system is the ledger that holds accounts, balances and transactions. Choosing how to modernize it is the largest single decision in the program. That choice sets the cost, the risk and the timeline for everything else.
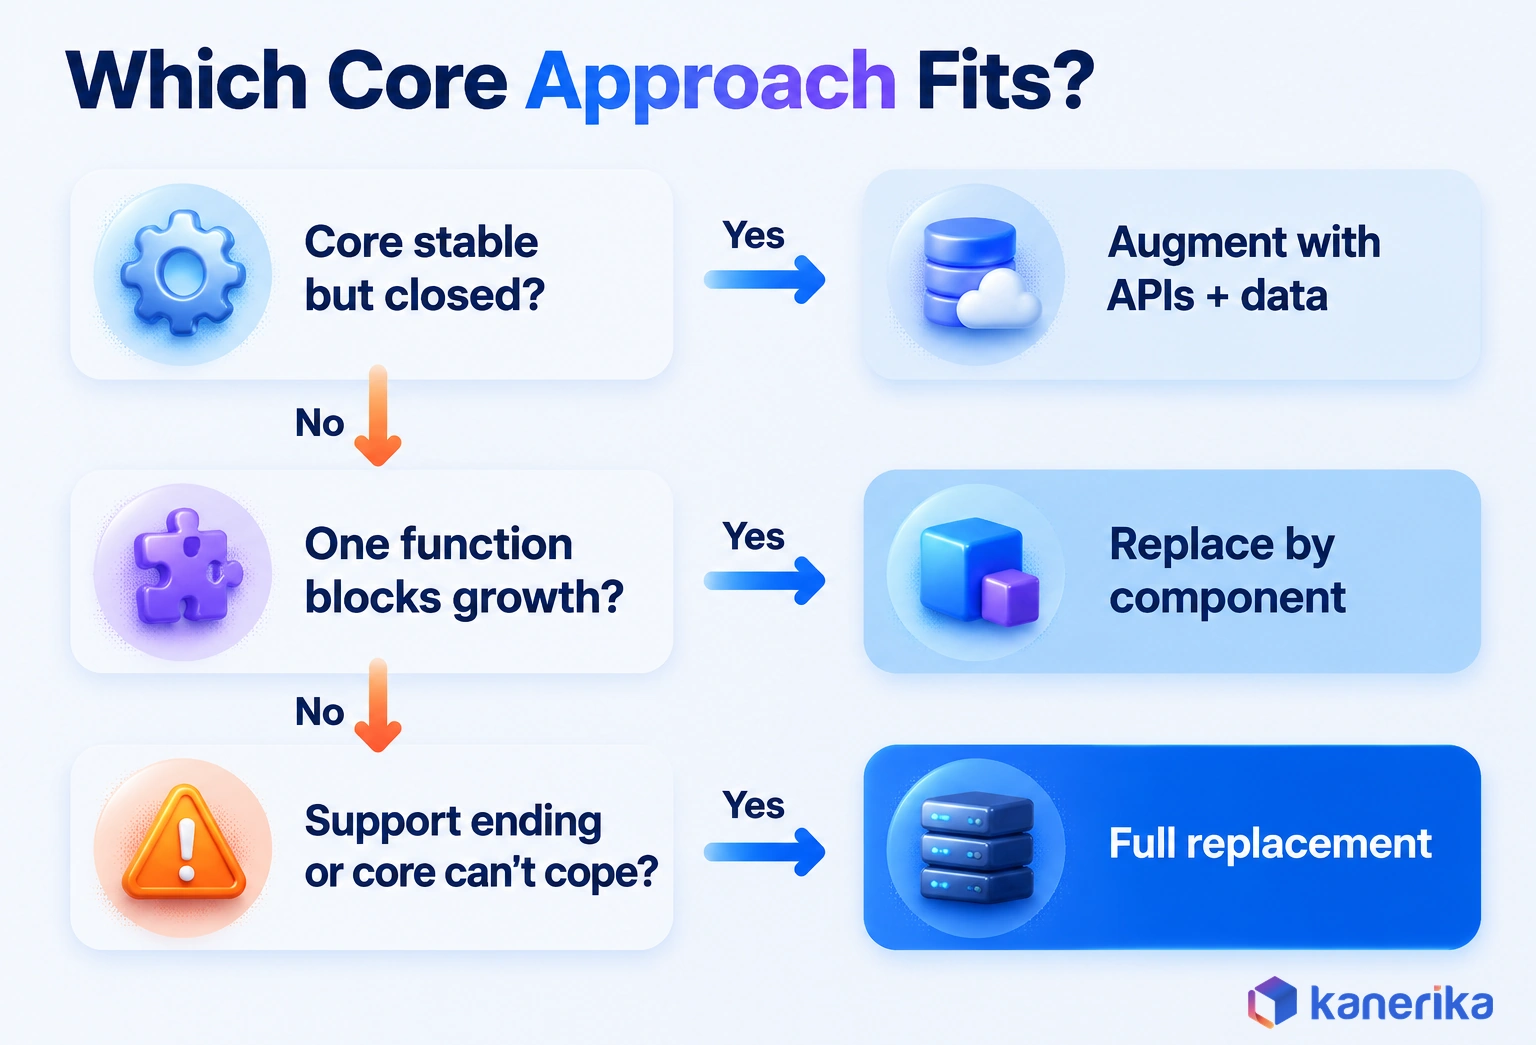
The Kansas City Fed briefing describes three options. A bank can replace the core in full, replace it component by component, or augment the existing system. A fourth path, launching a new digital brand on a separate core, is common enough to compare as well.
| Approach | When it fits | Main risk | Time to first value |
|---|
| Full replacement | Vendor support is ending, or the core cannot run required products | A long parallel run and one large cutover | Slowest; value arrives at cutover |
| Component replacement | One function, such as deposits or payments, blocks growth | Integration between old and new parts | Medium; each component delivers on its own |
| Augment the existing core | The core is stable but closed and batch-driven | Technical debt stays in place | Fastest; APIs and a data layer ship first |
| Build alongside (new digital brand) | The bank wants a new segment or product line quickly | Two cores to run and reconcile | Fast for the new brand, none for existing customers |
Still, no approach wins everywhere. The right one is the least disruptive option that removes the constraint that actually hurts your customers or your costs.
When Full Replacement Fits
Full replacement makes sense when the vendor is retiring the platform or the core cannot run the products the strategy needs. Rising patching costs are a third trigger. The Kansas City Fed briefing also calls it the most risky and expensive option. Its risks include core downtime, data migration and the reliability of the new system. Plan for a long parallel run in which both systems post the same transactions and the results are reconciled every day.
When Component Replacement Fits
Component replacement suits a bank when one function is the bottleneck. Deposits or payments might move to a modern component first, connected to the old ledger through APIs. Each step delivers value by itself, and the bank learns as it goes.
The same briefing cites Zions as an example. The bank upgraded its lending component first and then moved to deposits only after thousands of test simulations. During the switch it ran the old and new systems side by side and migrated branches one at a time.
The price, however, is integration work. A clear API layer has to exist before the first component moves, or every new piece adds another fragile link.
When Augmenting the Existing Core Fits
Augmenting suits a bank whose core is stable but closed. An API layer exposes core functions to new channels, while a data platform copies core data out for analytics and AI. This is often the fastest route to visible results. The old core’s limits remain, so treat augmenting as a bridge with a set date to revisit the replacement question.
When a New Digital Brand Fits
Some banks launch a separate digital brand on a new core. The goal is to reach a segment the main bank serves poorly, such as small businesses or younger savers. Because it carries no legacy products, the new brand can move fast.
The catch is that existing customers see no benefit. On top of that, the bank ends up running two cores whose data must be reconciled for finance and risk reporting. Some banks treat the new brand as a live test of a modern core before the main bank commits to it.
Whichever path you pick, the data has to move and it has to match. Mapping old product codes, cleaning customer records and reconciling balances take longer than most plans allow. That is why Kanerika’s guide to data migration treats reconciliation as a gate rather than a final check.
High-Value Use Cases
Use cases are where a program proves its worth to the business. The strongest ones remove manual steps from a process that customers or regulators already care about.
Digital Onboarding, KYC and KYB
Onboarding is usually the first process a bank digitizes, and the opening story shows why it needs a real-time core behind it. For consumers, it covers remote identity checks and sanctions screening. For businesses, it also adds company and ownership checks. The same automation, often built with robotic process automation, reaches into the branch, where staff time used to go on rekeying.
Digital transformation revolutionizes branch operations by automating routine tasks that previously consumed valuable staff time. Customer onboarding now happens through integrated platforms that instantly verify identities, check compliance databases, and populate documentation automatically. For business onboarding, banks also need to validate company registration details, confirm authorized signatories, and identify beneficial owners- steps typically handled through Know Your Business (KYB) to reduce fraud risk and meet compliance requirements. Transaction processing becomes seamless, with intelligent systems handling deposits, withdrawals, and transfers while staff focus on complex customer needs and relationship building.
Fraud and AML Monitoring
Fraud and anti-money-laundering teams adopted AI early, because the data is high-volume and the patterns shift fast. Models score card and payment transactions in real time, and alerts reach investigators with the evidence attached. Kanerika’s guide to AI fraud detection covers the model choices. For planning purposes the lesson is simpler: monitoring is only as current as the data feed behind it.
Digital Lending and Credit Decisions
Digital lending pulls application, bureau and account data into one decision. The speed gain is real, but the explanation has to keep up.
Under Regulation B, 12 CFR 1002.9, a lender that takes adverse action must give specific principal reasons. Saying the applicant failed the lender’s internal standards is not enough. The rule applies to model-driven decisions as well, so reason codes belong in the decision engine from day one.
Regulatory and Financial Reporting
Regulatory reports often depend on spreadsheets assembled from several product systems. Moving them onto the governed data foundation gives every figure a traceable source and cuts the late reconciliation before each filing. Banks that pair this with compliance automation can also route control evidence to auditors without building packs by hand.
Statements and Servicing Automation
Statements and servicing look routine until volume grows. Each statement pulls from several systems, and every manual fix adds delay and risk of error. Automating the assembly, checks and delivery frees operations staff for exceptions, such as a mismatched loan balance held for review.
AI Assistants and Agents in Operations
AI assistants help staff search policies, draft replies and summarize case files. Agents go a step further by taking multi-step actions, such as gathering the documents for a loan file. Both need tight permissions and human checkpoints. Kanerika’s guide to agentic AI in banking covers those use cases and their controls in depth.
Treasury and Cash Forecasting
Treasury teams forecast cash and funding needs from deposit flows, loan drawdowns and payment patterns. Machine learning models can refresh those forecasts far more often than a monthly spreadsheet cycle, provided the inputs come from the governed data platform. Funding and liquidity decisions then rest on current numbers with less manual work.
Case Study
20% Productivity Lift for Bank Treasury with AI Forecasting
A bank treasury team applied AI forecasting to cash and funding decisions and recorded a 20% productivity lift.
Read the Case Study →
Benefits of Digital Transformation in Banking
A benefit is only real when a number moves. The table pairs each common benefit with the KPI that proves it and the part of the bank where it shows up first.
| Benefit | KPI that proves it | Where it shows up first |
|---|
| Lower cost-to-serve | Cost per account or per transaction | Servicing and operations |
| Faster decisions | Time from application to decision | Lending and onboarding |
| Fewer errors | Exception and rework rates | Statements, payments and reporting |
| Better fraud control | Fraud losses and false-positive rate | Card and payment monitoring |
| Faster product launches | Weeks from idea to launch | Core and product teams |
| Stronger compliance evidence | Exam findings and time to answer requests | Risk, audit and reporting |
Take the fewer-errors row as a worked example. A statements team counts how many statements need a manual fix each week before automation goes live. After the automated checks start, the same weekly count shows whether the benefit is real. A steady fall is proof the business can see without a debate.
Some benefits arrive sooner than others. Error rates and cycle times usually move within months of a use case going live. Cost-to-serve, by contrast, drops only after old systems and manual queues are retired.
A Phased Roadmap With Measurable Gates
A phased roadmap breaks the program into stages that each end with a decision. The gate between phases asks a plain question: did this phase deliver what it promised, and is the next one still worth funding?
Long programs fail quietly when nobody is allowed to stop them. Gates make stopping, or changing course, a normal part of the plan instead of an admission of failure.
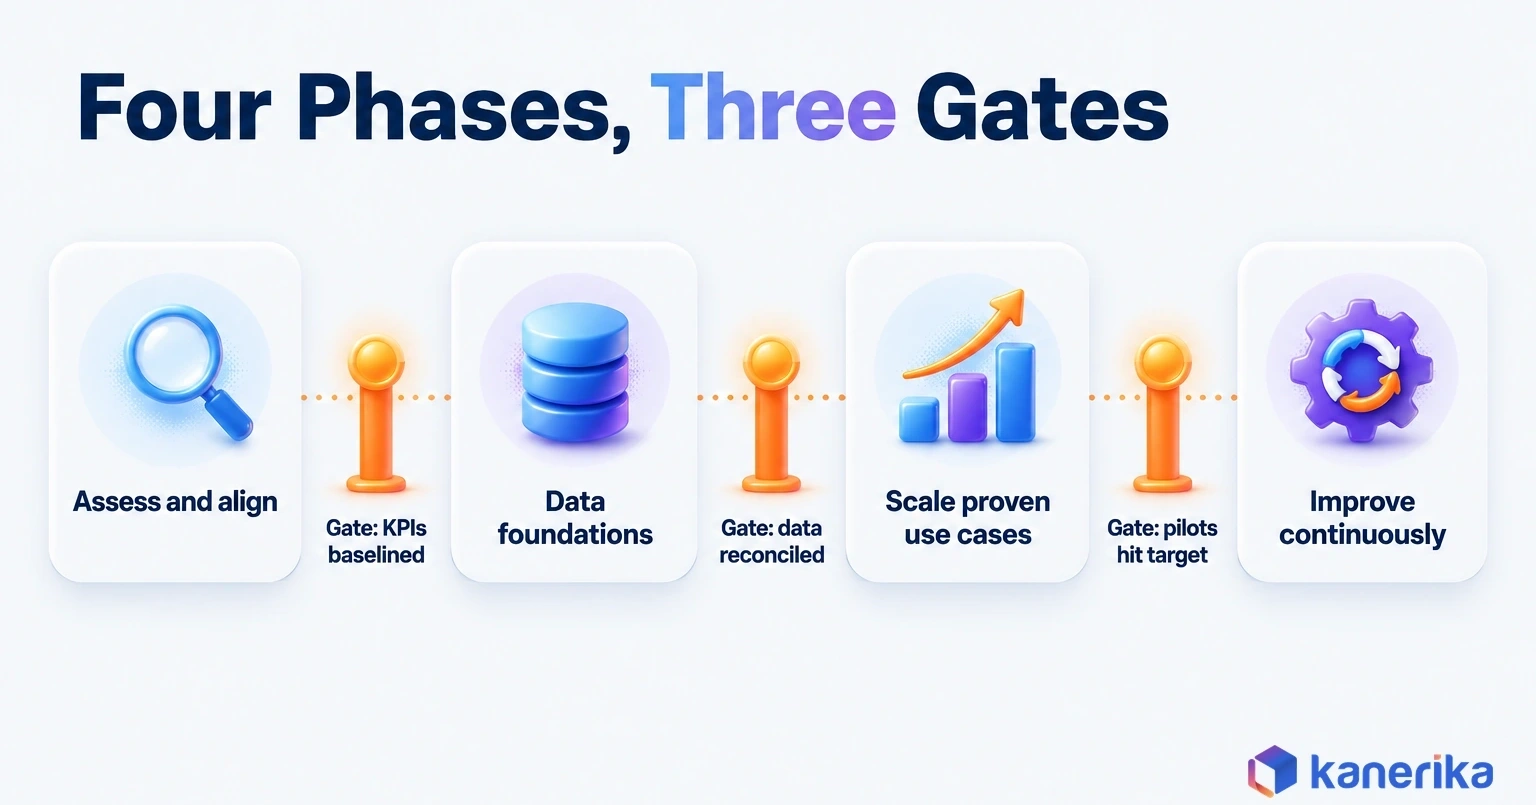
- Assess and align. Map processes, systems and data, rank use cases and choose the core approach. It ends when leadership approves a target architecture and baseline KPIs.
- Build the data foundations. Stand up the governed data platform, migrate priority data and reconcile it against the source systems. Compare record counts, ledger balances and totals per product, then log every break with an owner. The phase ends when priority reports run from the new platform and match the core.
- Scale proven use cases. Move two or three pilots, such as onboarding or statements, into production with named owners and targets. The phase ends when each one hits its KPI target in production.
- Improve continuously. Add use cases, retire old systems and tune models under monitoring. This phase has no end date, only regular reviews against the baseline.
Each phase also needs its own scorecard. The examples below are a starting point, so swap in the measures that match your baseline.
| Phase | Example KPI | Stop-or-continue question |
|---|
| Assess and align | Baseline cost-to-serve and cycle times recorded | Is the target architecture approved and funded? |
| Data foundations | Share of priority reports reconciled to the core | Do the numbers match the source systems? |
| Scale proven use cases | Straight-through processing rate per use case | Did each pilot hit its target in production? |
| Continuous improvement | Legacy systems retired and annual run cost | Are retired systems actually switched off? |
Risks, Regulation and Controls
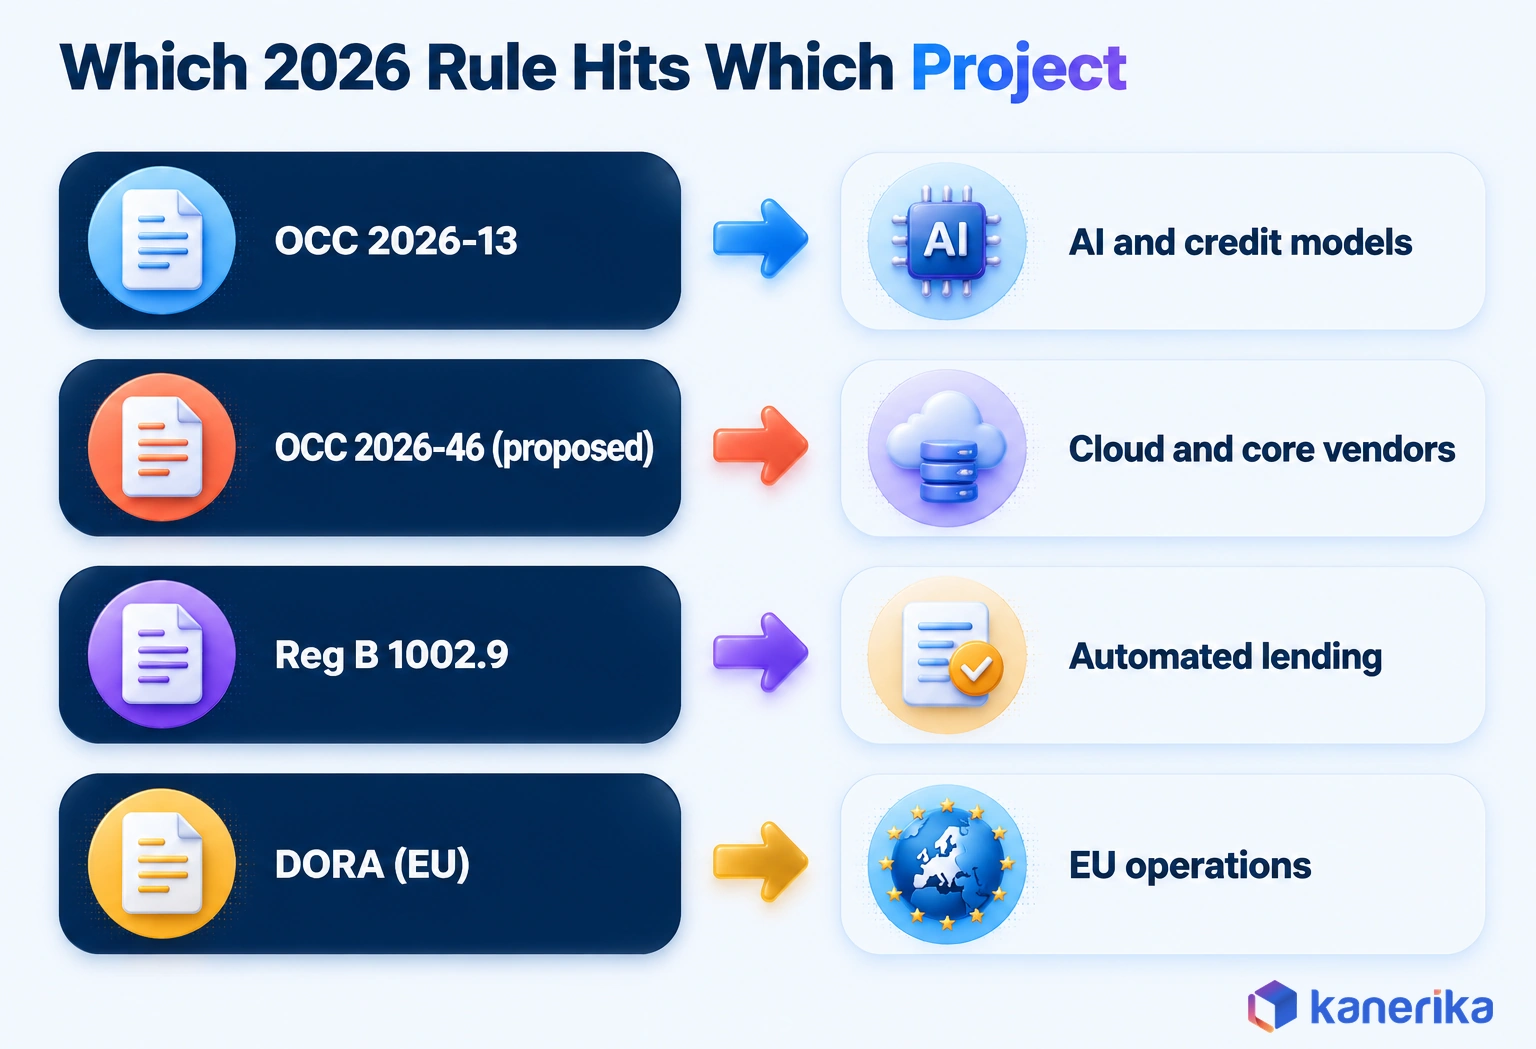
Every transformation adds new risks while it removes old ones. US supervisors expect banks to manage those risks in proportion to their size and complexity, and several 2026 changes affect how that works in practice.
Governance is the thread that ties these risks together. Kanerika’s guide to data governance in banking covers the framework in detail. The companion piece on AI in risk management also shows how models can support the risk function itself.
Model Risk
On April 17, 2026, the OCC issued Bulletin 2026-13 together with the Federal Reserve and the FDIC. The revised model risk guidance is risk-based. It also rescinds OCC Bulletin 2011-12 and the related Model Risk Management booklet of the Comptroller’s Handbook.
Generative and agentic AI models, however, are explicitly outside its scope. Banks using those tools therefore need to set and document their own controls, for example through an AI governance framework.
Third-Party and Cloud Risk
Cloud providers, core vendors and fintech partners all count as third parties. On September 11, 2026, the OCC published Bulletin 2026-46, proposed interagency guidance on third-party risk management that is tailored to risk. Comments are due 60 days after Federal Register publication, and the final guidance would also apply to community banks. Until then, plan due diligence, exit options and ongoing monitoring as if it already applied.
Fair Lending and Explainability
Automated credit decisions still have to explain themselves, and the lending section above sets out the Regulation B rule. The control question is who owns the reason codes. Compliance should sign off each code before launch. The team should then test the codes against a sample of real declined files, checking that each notice names the true drivers.
A generic code fails too. Under 1002.9(b)(2), saying an applicant failed to achieve a qualifying score on the creditor’s scoring system is not a specific reason.
Operational Resilience and EU Rules
If you operate in the EU, two more rules apply. The Digital Operational Resilience Act has applied to banks, insurers and investment firms since January 17, 2025. EU lawmakers have also deferred high-risk obligations under the AI Act, which cover credit scoring, to December 2, 2027.
Finally, the table below pulls these threads into one view of risk, impact and control.
| Risk | Impact if ignored | Control |
|---|
| Model risk | Wrong decisions repeated at scale | Risk-tiered validation and a complete model inventory |
| Third-party and cloud | Outage or data exposure at a vendor | Due diligence, contract terms and exit plans |
| Fair lending | Adverse-action notices without specific reasons | Reason codes designed and tested before launch |
| Data quality | Reports and models built on numbers that do not match | Reconciliation gates and named data owners |
| Operational resilience | Slow recovery from an incident | Tested recovery plans and incident playbooks |
What Digital Transformation in Banking Costs and How to Measure ROI
Cost follows three things a bank can see up front: the core approach, the number of products and the state of the data. Budgets copied from industry averages ignore all three, so they tend to mislead.
The practical step is to name the cost drivers and track each one from the first phase.
Kanerika Service
FLIP for Data Platform Migration
FLIP, Kanerika’s workflow automation platform, builds data pipelines with quality and governance built in, helping banks move legacy data to modern platforms faster.
Explore FLIP
| Cost driver | What pushes it up | How to contain it |
|---|
| Core platform contract | Licensing model, modules and term length | Phase modules to match the roadmap |
| Data migration | Number of source systems and poor data quality | Clean and reconcile before cutover |
| Integration | Point-to-point links that must be rebuilt | Build the API layer once and reuse it |
| Parallel run | Months in which both systems post the same transactions | Agree exit criteria before go-live |
| Change management | Training, process redesign and new roles | Fund it as a line item, not a leftover |
Total cost of ownership should cover the full life of the platform. That includes the run cost of old systems kept on during the transition. This cost often runs higher than planned, because those systems stay on until the last product moves.
ROI then comes from the KPIs in the benefits table, measured against the phase-one baseline. Count a saving only when a cost actually leaves the budget, such as a retired license or a smaller manual queue. That discipline also keeps the business case credible with the board.
Common Mistakes Banks Make
Transformation programs rarely fail from one big error. They fail from a few habits that looked reasonable when someone chose them.
- Moving data without cleaning and reconciling it. Moving messy data to a new platform simply moves the mess, a pattern our guide to data migration in banking examines. Duplicate customers and mismatched product codes break reports and models on day one. Balances and transaction counts must match between old and new systems before cutover. Teams that skip this check to save a week can spend months fixing errors.
- Pilots with no production path. A proof of concept with no owner, budget or integration plan stays a demo. Decide before the pilot starts what success will fund next.
- Treating augmentation as permanent. An API layer around a stable but closed core is a sound bridge, not a destination. Without a set date to revisit the replacement question, the old core’s limits slowly become the bank’s limits again.
- Leaving the operating model unchanged. Technology changes faster than the way people work. A bank can install a modern core and still push every change through a slow quarterly release board. Product teams that own a process end to end, with business and technology staff in the same group, close that gap. Early training and change management for branch and operations staff close it further, or the new platform simply runs the old process at a higher cost.
Migration problems in particular follow familiar patterns. The video below walks through why data platform moves succeed or fail, which applies directly to a core or data foundation project.
Watch on YouTube
Why Data Platform Migration Succeeds or Fails
Manisha Chowdari, Head of Business Analysis at Kanerika, talks through why data platform migrations succeed or fail, the same risks a core or data foundation move carries.
How Kanerika Approaches Banking Transformation
Kanerika works with banks on the layers this guide describes, with a focus on the data foundation between the core and AI. Its banking practice usually starts with an assessment of processes, systems and data, which produces a ranked list of use cases tied to baseline KPIs.
From there, the team modernizes the data platform with FLIP, Kanerika’s workflow automation platform for building data pipelines with quality and governance built in. Ownership, lineage and access controls are set up as the data moves. Kanerika’s migration services cover the move itself, and AI and automation use cases follow once the data can be trusted.
One project, for example, shows the approach in practice. A leading bank produced about 70,000 consolidated statements per cycle, drawing on accounts, deposits, credit cards and loans from three application sources. After automation, the results looked like this.
| Measure | Result |
|---|
| Manual intervention and errors | 100% reduction |
| Processing time | 80% reduction |
| Volume capacity | 2X headroom without added resources |
The same pattern applies beyond statements. Kanerika has applied AI forecasting to bank treasury funding, and every engagement starts from the same principle of trusted data first.
Talk to Kanerika
Plan Your Bank’s Transformation Roadmap
Talk to Kanerika about assessing your core, data and use cases, and leave with a phased plan tied to KPIs you can measure.
Book a Consultation →
Wrapping Up
Digital transformation in banking succeeds when the order is right. Start with outcome measures, then choose the least disruptive core approach that removes your real constraint. Build a governed data foundation before you scale AI, phase the work behind gates and plan for the 2026 model risk and third-party guidance. So what works in 2026? Fix the core and the data first, and the channels and AI built on top of them will pay back.
Frequently Asked Questions
What is digital transformation in banking?
Digital transformation in banking is the work of changing how a bank serves customers, makes decisions and runs operations so more processes flow straight through without manual steps. It covers channels, the core, the data platform, AI and the operating model. Success shows up in outcomes such as lower cost-to-serve, faster decisions and fewer errors.
What is a digital banking transformation strategy?
A digital banking transformation strategy is a plan that links business outcomes to specific changes in channels, core systems, data and operations. It names the core modernization approach, ranks use cases by value and feasibility, and sets phases with measurable gates. A good strategy also states which legacy systems will be retired and when, so savings become real.
What are the main security and compliance concerns in digital banking transformation?
The main concerns are model risk, third-party and cloud risk, fair lending, data quality and operational resilience. Banks need risk-tiered model validation, vendor due diligence with exit plans, specific adverse-action reasons for credit decisions, reconciliation controls and tested recovery plans. Identity, access control and encryption should be designed into every layer rather than added at the end.
How much does digital transformation in banking cost?
There is no reliable universal figure, because cost depends on the core approach, the number of products, the number of source systems and data quality. The main cost drivers are the core platform contract, data migration, integration, the parallel run and change management. Total cost of ownership should also include running legacy systems until the last product moves.
How long does core banking modernization take?
Duration depends on the approach. Augmenting an existing core with APIs and a data platform can show results soonest, while component replacement delivers in steps over a longer period. Full replacement usually takes the longest because of data migration and the parallel run. Plan by phase gates and exit criteria rather than a fixed end date announced up front.
How can banks modernize a legacy core without replacing it?
Banks can augment a legacy core. An API layer exposes core functions such as account opening and payments to new channels, while a data platform copies core data out for analytics, reporting and AI. Some functions can later move to modern components one at a time. Treat this as a bridge and review the replacement question on a set schedule.
How is AI used in digital transformation in banking?
Banks use AI to score transactions for fraud and money laundering, support credit decisions, read documents during onboarding, forecast treasury cash needs and help staff through assistants. Each use depends on clean, governed data. In the US, model governance follows the 2026 interagency model risk guidance, and credit decisions still need specific adverse-action reasons under Regulation B.
What is the difference between digital banking and digital transformation?
Digital banking describes the channels customers use, such as mobile apps and online banking. Digital transformation is the deeper change behind those channels, covering the core, data, processes and operating model. A bank can offer digital banking while still running batch processes and manual back-office work. Transformation removes those manual steps so digital channels deliver real speed.
How do banks measure digital transformation ROI?
Banks measure ROI by tracking outcome KPIs against a baseline set before the program starts. Typical measures include cost per account, time to decision, straight-through processing rate, error rates and fraud losses. Savings should count only when a cost actually leaves the budget, such as a retired license, a decommissioned system or a smaller manual work queue.
How can community banks pursue digital transformation on a limited IT budget?
Community banks can start by augmenting their existing core rather than replacing it, adding APIs and a modern data platform in stages. Focusing on two or three high-volume processes, such as onboarding or statements, delivers measurable savings early. Careful vendor oversight matters too, since the proposed 2026 interagency third-party guidance would apply to community banks once finalized.
Which US regulations affect AI and cloud adoption in banks?
Three are especially relevant. OCC Bulletin 2026-13, issued with the Federal Reserve and FDIC in April 2026, sets revised model risk guidance but excludes generative and agentic AI. OCC Bulletin 2026-46 proposes interagency third-party risk guidance that covers cloud and fintech vendors. Regulation B requires specific adverse-action reasons for credit decisions, including model-driven ones.
How does digital transformation improve fraud detection in banks?
Transformation gives fraud teams current, unified data and real-time scoring. When card, payment and account data flow into one governed platform, models can score transactions as they happen and send investigators alerts with evidence attached. Automation also reduces manual review of low-risk alerts. Results depend on data freshness, because a model is only as current as its feed.
Why is digital transformation important for banks in 2026?
Customers now bank mainly through apps, with 54% of US bank customers naming mobile apps as their top channel in a November 2025 ABA survey. Many older cores still struggle with real-time products, AI needs clean data, and US regulators updated model risk guidance and proposed new third-party guidance in 2026. Waiting makes each gap harder to close.
What are the main areas or pillars of digital transformation in banking?
Most programs work across five areas. These are customer channels, core and product systems, the data platform, AI and automation, and the operating model. The core and the data platform usually set the pace, because channel and AI improvements depend on real-time posting and trusted data. Each area needs its own KPI, such as straight-through processing rate.
What are the stages of digital transformation in banking?
A practical sequence has four stages. First, assess processes, systems and data and choose the core approach. Second, build the data foundation and reconcile migrated data. Third, move proven pilots into production with owners and targets. Fourth, keep improving by adding use cases and retiring old systems. Each stage ends with a stop-or-continue gate based on measured results.
What are the four types of digital transformation?
The four commonly cited types are process, business model, domain and cultural transformation. Process transformation redesigns how work gets done, business model transformation changes how value is delivered, domain transformation moves into new markets, and cultural transformation changes how people work and decide. Banks usually start with process and cultural change, because both support every other change.
What are the main types of digital banking?
Digital banking takes several forms. Traditional banks add mobile and online channels to an existing franchise, digital-only banks serve customers without branches, and some banks launch a separate digital brand on a new core. Banking-as-a-service lets non-bank companies embed accounts or payments through a licensed bank’s APIs. Each model places different demands on the core and the data.
What are the main digital banking trends in 2026?
Several trends stand out in 2026. Mobile apps remain the leading channel, banks are modernizing cores in components rather than in one replacement, and AI is moving from pilots into fraud, lending and servicing. Regulation is shifting too, with revised US model risk guidance, a proposed third-party risk framework and, in the EU, a deferred AI Act timeline.
What are the keys to a successful digital transformation in a bank?
Success depends on order and discipline more than tools. Define outcome KPIs and record a baseline, pick the least disruptive core approach that removes the real constraint, and build a governed data foundation before scaling AI. Fund change management as a budget line, give each use case an owner, and use phase gates to stop work that is not delivering.
Why do so many bank digital transformations fail?
Programs usually fail through a handful of habits rather than one mistake. Common causes include moving messy data without cleanup, running pilots with no path to production, skipping reconciliation during migration and leaving the operating model unchanged. Long programs without stop-or-continue gates also keep spending after results stall, because nobody has a clear point at which to reassess.














